News for hackers. Stuff that matters.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cammikebrown on Thursday April 28, 2022 @02:25AM (#31189318)
Seems like the bubble burst is going to be more sudden than we thought. 30 year mortgages are suddenly at nearly 5.5-6%, listings are sitting on the market for longer, and multiple cities are cracking down on Airbnb.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by hans1729 on Thursday April 28, 2022 @02:46AM (#31189440)
I mean, it's not really a burst, we're just hearing the hissing noise of the obvious leak.

The true demand from people with the intend to actually live in the estates has been constantly decreasing since around 2000; the real salarys dropped since then, so did the buying power.

The only reasons people found buyers at x3-x10 (!) prices were

a) that there is a class of people wealthy enough to still afford the purchase, even at those completely-out-of-touch prices, and

b) that people were given loans they should either never have gotten (2008) or that they shouldn't have asked for (because it's dumb to buy estates where the price is set by people and institutions that have n times your own income/net worth)

When 90 (?) percent of people simply lack the buying power to participate in the real estate market, but the other 10% happily sell each other estates, that's not a bubble, the real estate market just stopped interfacing with the vast majority of the population.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @04:37AM (#31190112)
I think you have missed a source of demand, and I think it's important.

As housing became more and more expensive to young professionals, some people in this group have worked harder and harder to buy property, even to the point where it no longer seems rational. For example, parents taking a lot of wealth out of their retirement savings or their own homes to assist children in buying. Professionals are working more than otherwise makes sense for their stage in life (young families with two full-time parents). They are committing a large share of their monthly budget, often right until the start of retirement.

They do this because they believe in the importance of owning property - beyond any reasonable narrow economic justification.

Of course, there is an inequality aspect to this - not everyone's parents have capital, not everyone can command a high enough wage.

But crucially, the presence of this group of people arguably turns the bubble into something else. These buyers put a floor on the market. If prices drop even a little, or something else changes to make mortgages slightly more affordable, they rush in and buy the dip. By doing this, they sustain the high prices for everyone else in the market.

This will probably happen now. Higher rates will make current prices unsustainable. As soon as they correct to the point where monthly payments are back to what they were last year, there will be buyers, only too happy to overextend themselves to get out of renting.

It's inaccurate to characterize these people as likely to default. They are actually very good mortgage risks - they have already shown themselves to be very committed to ownership. And the resources which got them into a position to buy mean they will keep on paying short of a disaster. The truly unrealistic borrowers of pre-2008 have never been let back into the market.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by hans1729 on Thursday April 28, 2022 @04:50AM (#31190173)
I did not miss those people, but my wording was loaded and so the point got lost in translation. I implicitly captured them under b) "[...] it's dumb to buy estates where the price is set by people and institutions that have n times your own income/net worth", where dumb is a loaded term for your >"to the point where it no longer seems rational".

>But crucially, the presence of this group of people arguably turns the bubble into something else.

I agree with this, it's not a bubble in the sense of 2008. I said so in the comment you replied to! We're in the same boat here.

By the way: I'm precicely in that demographic. I just turned 30 and do well for myself as an employed consultant, but I wouldn't consider buying the dip, unless the dip is at least ~100% of the current market prices (which I don't see happening, but who knows). Going in debt for 30-40 years has zero appeal for me, it just seems like a terrible move. The counter-argument I hear from people my age group is always the same "but then you'll never own anything!" -- then so be it, whats the point?! Even if someone gave me a million Euros, I wouldn't spend 600k of those on a house and then another 300k on renovations, that seems like a terrible waste of resources. With that kind of money, you can buy three small companies in Germany, or stop worrying about retirement, etc. Buying estate = de facto being in debt for the entire career and then some, plus having to pay all repairs, anything. I don't see how that would ease my life at all. If someone wants to give me a house, nice, but buying a house just for the sake of doing so reminds me of a signature I often read on market-ticker.org -- leave the rats race to the rats.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by itsoktocry on Thursday April 28, 2022 @05:45AM (#31190550)
>Going in debt for 30-40 years has zero appeal for me, it just seems like a terrible move.

Buying a house isn't for everyone, sure. But this is a serious misunderstanding of what "going into debt" is. You're not buying a TV you'll throw out in 5 years, you're buying an asset class that has a history of appreciating in value over 100+ years that you can get incredible leverage on. In the US and Canada, at least, buying a house for a decent deal (in "normal" times, not at insane prices) is a no-brainer investment.

You mention buying companies...that's just a different asset class, but the idea is the same. It's not valueless the moment you buy it, you now have an asset.

>Buying estate = de facto being in debt for the entire career and then some, plus having to pay all repairs, anything.

Do you think this is all happening for free as a renter? At what point in your life do you plan on not paying for shelter?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by agent008t on Thursday April 28, 2022 @06:27AM (#31190839)
>buying an asset class that has a history of appreciating in value

Correction - over a time period of decreasing interest rates. Housing, on its own, is a depreciating asset. It is a consumable like a TV. It deteriorates with time.

"Housing always goes up", without an understanding of why it has been going up, can be a dangerous belief and could be one of the reasons why housing at the moment is so expensive relative to rents.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by BirdieNZ on Thursday April 28, 2022 @07:01AM (#31191058)
Most of the housing bubble is actually a land price bubble. Land is only a long-term depreciating asset in shrinking cities, because demand for the land is decreasing.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by agent008t on Thursday April 28, 2022 @07:44AM (#31191360)
Simply put, house price is a function of rents for similar houses and the multiple of annual rent that houses sell for. The multiple is primarily a function of interest rates, and a significant proportion of house price increases in recent decades has been the increase in multiple. It is also a function of expected future house price growth - the higher the expectation, the higher the multiple, which is where psychology and FOMO comes into play.

The interesting thing about these ingredients that decide the multiple, is that they can turn sharply. If interest rates go up, and multiple starts to contract, at some point the belief that house prices always go up will be shaken, and instead of pricing in future house price growth, people will start pricing in future contraction.

Level of rents is a function of the state of local economy (broad salary levels, more or less) and house supply. Can probably broadly be approximated as GDP growth - so fairly low.

So at interest rates at very low levels and arguable on the way up, and growth expectations seemingly very positive, and economic growth looking shaky, it looks as if house prices may have more downside than upside.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by gbasin on Thursday April 28, 2022 @09:12AM (#31192038)
Housing [land] prices have been grinding higher long before the Great Decline in interest rates

https://fred.stlouisfed.org/graph/?g=kYEb

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by agent008t on Thursday April 28, 2022 @10:35AM (#31192966)
That chart seems to only go back to 1987, which is after the decline in interest rates started: https://fred.stlouisfed.org/series/REAINTRATREARAT10Y
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by gbasin on Thursday April 28, 2022 @11:08AM (#31193408)
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by eberkund on Thursday April 28, 2022 @12:39PM (#31194727)
According to this, home prices were mostly flat from 1900 up until the 1970s. The proves the opposite of the point you are trying to make.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by gbasin on Friday April 29, 2022 @10:01AM (#31205206)
This is adjusted for inflation
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rrrrrrrrrrrryan on Thursday April 28, 2022 @01:52PM (#31195775)
Residential real estate valuations haven't been based on the house itself for a while. Prices are based on:

1) the house itself (this generally depreciates)

2) land (this generally appreciates)

3) a retirement account with great tax benefits (this value can fluctuate based on local, state, and federal laws)

4) a ticket into a good school district (this value will fluctuate based on the the performance of local schools)

5) a ticket to partake in a thriving local economy (this value will fluctuate with the local economy, and has recently been shaken up by the rise of remote work)

Any speculation on real estate prices and whether or not we're in a bubble has to take these things into account.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throw8383833jj on Thursday April 28, 2022 @12:40PM (#31194744)
Interest rates for mortgages follow 30 yr treasuries which won't get very high. The Fed will come in with full on yield curve control at some point. 30yr treasuries are at almost 3%, already. I can't imagine they'll get higher than 4 or 5%, at least for not too long. The world is way too addicted to low rates. if interest rates rise for any long period, something will break, really badly, there will be a fear filled crash and the fed WILL come in: you can bet on that.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by milkshakes on Thursday April 28, 2022 @06:33AM (#31190877)
housing might depreciate, but the same is not generally true for the real estate it sits on
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ratsforhorses on Thursday April 28, 2022 @09:06AM (#31191978)
Is this also true for places like Detroit, small inner towns in the mid ? West... my impression was that once banks got involved lending money the prices took off, I was under the impression that getting a house loan directly contributes to the amount of money in circulation...thereby increasing ? inflation.... another myth?) I heard was that in China houses are leased for x years (80?) thereby leading to a lot of Chinese buying foreign Real Estate.... if RE has the reputation of accruing value surely it'd be a good thing to put the brakes on companies from investing in it? I mean seeing endless same housing is kind of mind numbing....

I also have a theory that high RE prices are a perfect vehicule for stashing/laundering large sums of money....

Also to what extent isn't it political cronyism with the construction industry that leads to such shitty urbanistic decisions like we have in Romania where people are pawns to short term greed ...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rfoo on Thursday April 28, 2022 @10:47AM (#31193113)
> in China houses are leased for x years (80?)

It's worse. It's the land being leased for 70 years. House usually can't last that long anyway. But not owning the land and no guaranteed usufruct after 70 years is big.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by neon_electro on Thursday April 28, 2022 @12:55PM (#31194921)
Thank you for teaching me a new word, "usufruct": https://en.wikipedia.org/wiki/Usufruct
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bombcar on Thursday April 28, 2022 @08:57AM (#31191888)
Land values can turn around, especially if desirability of the area changes.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by llampx on Thursday April 28, 2022 @06:49AM (#31190980)
Exactly. I believe interest rates bottomed sometime in 2020-2021. Those rates are not going to be seen for another few decades. It remains to be seen what this will do to house prices. What happened to most speculative tech stocks since 2021 can also happen to other asset classes.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by MGriisser on Thursday April 28, 2022 @02:13PM (#31196074)
It seems pretty premature to say that mortgage interest rates that happened barely over a year ago won't happen for a few decades.

You could have looked at interest rates below 3.5% in 2013 and said the exact same thing; that was the lowest interest rate in over 40 years!

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by llampx on Thursday April 28, 2022 @02:52PM (#31196650)
I am absolutely sure. Look at inflation, for one. We haven't seen these inflation numbers since the 1980s, and this is in just 2 years since the biggest central banks opened the money spigots. I'm a millenial so I don't relish it, but "you ain't seen nothin' yet."
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by fzeroracer on Thursday April 28, 2022 @02:08PM (#31196015)
>you're buying an asset class that has a history of appreciating in value over 100+ years that you can get incredible leverage on

This is precisely the problem. It's not just companies buying up homes, it's also private individuals buying up housing to relist on AirBnB or other sites in order to further extract value out of their purchase.

If you look at a country like say, Japan they don't have this issue because housing depreciates and is not treated as an investment.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by peyton on Thursday April 28, 2022 @07:25AM (#31191206)
Not sure I want to leverage up on housing through the boomer die-off. Plus, there are way better investments.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @07:35AM (#31191282)
Doesn't the boomer die-off mean that the boomers' children will be inheriting, not just homes, but piles and piles of liquid assets, much of which they will use to get into the housing market?

After all the boomer generation, on average, has over-provisioned for old age, whereas millenials are still underhoused.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lotsofpulp on Thursday April 28, 2022 @08:32AM (#31191712)
>After all the boomer generation, on average, has over-provisioned for old age, whereas millenials are still underhoused.

Have they over-provisioned? Everything I have read indicates meager savings for the vast majority of the population, who will need to rely on Medicaid and Social Security to eek out the remainder of their living costs.

Nursing home care is especially costly in the event one does not die quickly, and the government can and I assume will seek to reimburse itself from the estate once the elder dies.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @10:38AM (#31193015)
I think the reality is more subtle.

A large number of poorer elder people will be in dire financial straits, forced to work beyond their ability to do so and unable to pay for health care.

However there are also a smaller number of extremely rich baby boomers and a very large number of comfortable middle-class ones. The former will obviously pass on large amounts of wealth. The latter have been forced to save large amounts for their old age, because they have known since middle age that the state would not provide for them very well.

In some cases they have decent final salary based pensions and other very good retirement benefits, no longer available to younger generations. In other cases, they have invested significant sums over the last decades and also made large investment gains.

This group has tended to save for the 'worst case' scenario - a long retirement of leisure spending, followed by drawn out old age with significant care needs. Most of them will not need all this capital - they'll either die younger than expected, or have better health into their 80s and 90s than they feared. The excess will be handed on to their children - and will be a significant source of intra-generational inequality in the future.

Remember also that middle-class baby boomers remain an electoral 500-lb gorilla. Governments have been very reluctant to claw back their benefits and care provisions as fast as has happened to other groups. In some cases they will be provided for better than expected when they planned for retirement.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Arubis on Thursday April 28, 2022 @02:59PM (#31196740)
> This group has tended to save for the 'worst case' scenario - a long retirement of leisure spending, followed by drawn out old age with significant care needs. Most of them will not need all this capital [...]

Sure sounds like this group would have had happier, more rewarding life experiences, and at a macro level made a more appropriate investment of effort, had they been able to trust a social safety net.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lotsofpulp on Thursday April 28, 2022 @11:58AM (#31194166)
I think you might be referring to top 10% of households.

https://dqydj.com/net-worth-by-age-calculator-united-states/

75th percentile gets to only $800k by age 70, and that is including the equity in their home. Maybe the beneficiaries of the 70% to 90% households will end up with real estate worth a few hundred thousand, but I do not see much wealth being passed down beyond that.

Labor is only going to get more expensive as greater proportions of the population age out of the workforce and become labor buyers rather than suppliers. Unless many start dying younger than anticipated without using a lot of medical and nursing home care, I would not expect much if I was their descendant.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @12:50PM (#31194872)
A 'few hundred thousand' is a lot of money to inherit, and for lots of middle-aged people and young families it will go straight back into the housing market, typically in areas that are already quite hot.

Note that the upper quartile having $800k includes $500k which isn't in their primary residence. Older people tend to own cheaper houses than you might think, since they are more likely to live in more rural areas.

If you're 70 and have a house you might be able to live quite a few years on half a million. In practice, you have a decent chance of dying before you spend all your capital.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Clubber on Thursday April 28, 2022 @08:47AM (#31191808)
I believe the Boomer generation overspent. It's their parents that over saved (habits learned during the depression).
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by pjc50 on Thursday April 28, 2022 @05:21AM (#31190354)
> Going in debt for 30-40 years has zero appeal for me

Going into debt at the lowest interest rate you'll ever be offered to buy a leveraged asset that's likely to increase in price and reduce the overhead you pay on your largest expense, housing, and hedge against the risk of rent increases and security against the whims of landlords?

> Germany

Oh, Germany. Somehow Germany has escaped the constantly increasing house price effect, as has Japan.

If you owned a house in London its annual value increases would almost certainly out-earn your salary. And you don't have to pay tax on that.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by hans1729 on Thursday April 28, 2022 @05:43AM (#31190526)
>Going into debt at the lowest interest rate you'll ever be offered to buy a leveraged asset that's likely to increase in price and reduce the overhead you pay on your largest expense, housing, and hedge against the risk of rent increases and security against the whims of landlords?

Look, if I had enough money around, I'd maybe consider the gamble. But I don't want to buy property to sell it later, I just want to live somewhere. I'm not interested in placing bets on my salary, and I'm not interested in financial longterm-obligations. Maybe in 10 years I want a year off? What then? Maybe I want to change careers to something less intellectually demanding. Maybe I want to spend 50 hours a week with my kids. None of those are feasible if I need the salary. "No debt" is synonymous to freedom on so many levels in life design. The choice is not even close to me.

I make enough money not to worry about rent, even if it should substantially increase, which I don't see happening anyway, simply because then most people wouldn't be able to afford it and political change would become opportune in election-based systems.

>If you owned a house in London

Whats the point of even thinking about owning a house in London? Seriously. I come from uneducated parents that left me €0 and completely unprepared for life, so in my 20s, I first had to dig myself out of that crap. Now I make a good living, but I'm not rich, or filthy rich, or even wealthy. I have to actually make the money to pay that thing. Look at the development of real estate prices in the last 20 years and tell me that's a reasonable choice if I don't even intend to sell the property later (just to be stuck in the same situation again, with more cash, but in the same dilemma). It's pointless. I don't treat my lifetime-expenses as a game of assets, I opt for quality of life, which I don't achieve by giving it all to some property-owning entity who sells it to me at 3 times the price they paid a couple decades ago. I mean, you can justify doing so, but I don't see me being able to justify it.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ilammy on Thursday April 28, 2022 @06:16AM (#31190778)
> I'm not interested in placing bets on my salary

That's exactly what you already do if you're renting: you're betting that you will be able to work and earn enough salary to afford the rent, with your adjusted expenses. That's "pfft easy" when you're in 20's, easy in your 30's, okay in your 40's (kids need money, yo), doable in your 50's, oh shit when you're 52 because surprise! economic downturn / medical emergency / anything else that might happen. And now you don't have a place to live in and spending your retirement money to rent one, or take a dip in your quality of life.

If you're not paying for your mortgage, you're likely paying for one of your landlord.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @11:59AM (#31194177)
> And now you don't have a place to live in and spending your retirement money to rent one, or take a dip in your quality of life.

As you say, keeping up with rent is easy (not necessarily, but for those in professional careers) early in life, but as your income plateaus later in your career it starts to become harder to keep up with relentless rent increases.

But then it's in retirement that a lifetime of renting really hurts. Suddenly you have no income anymore other than whatever small retirement benefits if any, but rents keep going up.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ac29 on Thursday April 28, 2022 @02:46PM (#31196569)
> But then it's in retirement that a lifetime of renting really hurts.

That assumes that the mortgage (+tax, +maintenance, +etc) is the same cost or less than renting is. That almost certainly isnt the case at first - at least in the area I live, I see houses renting for far less than just the interest on the mortgage would be (if purchased today, presumably the owners bought at lower prices and/or lower interest rates).

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @04:00PM (#31197472)
> That almost certainly isnt the case at first

Agreed, at first the monthly cost of ownership is likely higher than rent. But my quoted comment was about retirement age, which is at the tail end, not at first.

It doesn't take long for rent to catch up and from there on rent will forever go up while the mortgage will either stay fixed or only go down via refinances. Even if refinancing doesn't work (in a rising rate market like right now) the mortgage is effectively going down via inflation while rents keep up with inflation.

In my case the first year of ownership was fairly painful as the cost was much higher than previous rent (although for a nicer place). By the second year was able to refinance so it wasn't bad anymore. By the third year, with rents rising, my mortgage was already about par with local rents.

Ever since then, rents have gone up massively (about 4x-5x) and my mortgage has only gone down (today about 30% of the inital monthly payment in absolute dollars, or effectively only about 15% considering inflation).

Most importantly, it will be paid off before I retire so once I'm on a limited fixed income that's one monthly cost I won't have to worry about. Having seen some forever-renter extended family reach retirement age with rising rents, it's a sad and painful situation.

My advice to anyone is that unless you hate your future self, buy a house in your 30s if at all possible.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by edmundsauto on Friday April 29, 2022 @08:50PM (#31212308)
Rent rises, your mortgage doesn't. I have locked in $3500/month current cost to have a home, which is about what rent would be (once you account for gains from investing the down payment to offset the rent).

Since 1980, in the US, rents have increased 9% per year. In 20 years, the rent will be 2-4x, whereas my mortgage will remain the same (modulo a lowered interest deduction).

Even if it's about as financially efficient (which I doubt), it's a very powerful feeling to have locked down a fixed cost of housing for as long as I want to live in California.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by matwood on Thursday April 28, 2022 @07:56AM (#31191440)
> I just want to live somewhere

Same. Which is exactly why I bought a house in 2011. In hindsight it was the perfect time, but at the time the market was still bumpy. At the end of the day, I had a stable job and needed to live somewhere.

> I make enough money not to worry about rent, even if it should substantially increase

The house next door to me rents for 2.5x my mortgage.

My salary has continued to go up, while my cost to live has continued to go down (I refied at the rate bottom). If I want to take a year off I can either rent out my house or just carry the cost at this point. Buying this house gave my wife and I more flexibility because with some decent certainty (+/- small amounts for taxes/insurance fluctuations) I can tell you what my cost to live will be next month or 24 months from now.

Finally, buying a house with a mortgage is best way for a normal person to protect against inflation. Housing is typically a families #1 or #2 expense, and being able to mostly lock that cost is a huge win 3-5-10 years out.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lotsofpulp on Thursday April 28, 2022 @08:43AM (#31191784)
>Same. Which is exactly why I bought a house in 2011. In hindsight it was the perfect time, but at the time the market was still bumpy. At the end of the day, I had a stable job and needed to live somewhere.

And you were more likely to be able to because it was 2011. Fewer people can do the same today, at least at a similar comfort level of cost of house to income ratio.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by matwood on Thursday April 28, 2022 @09:51AM (#31192431)
Sure, but what about 1-2-3 years ago? The person I responded to said they never saw the point of taking on 30 years of debt, so my response was in more general terms.

Also, 2011 was still very uncertain. Would the market continue to go down, and would I keep my job were all real questions.

Is today a questionable time to buy? Probably, but what type of correction is needed in a ~7% inflationary environment for it to shift into an ok time to buy? 10%? 20%?

The point is there is always uncertainty and only in hindsight did 2011 look like a great time.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by darrenf on Thursday April 28, 2022 @07:46AM (#31191369)
I spent most of my 20s thinking, man, fuck home ownership, I'm gonna rent forever (to my knowledge, no-one in my family had ever owned; I grew up in charity housing and inherited nothing at all). Then I got booted out of a place because the landlord wanted to sell. They offered it to me first, but I had no savings for a deposit. The same story played out amongst my friends, repeatedly, and it totally changed my mind. It wasn't rent increases that were worrisome or painful, it was being forced to move. I wanted to find somewhere I liked and bloody stay there, a literal impossibility all the while I rented. But if I could get a deposit together† then ownership would do it - plus it was revelatory to me that my mortgage payments would be less than the rents I'd been paying AND I could have them fixed for 10 whole years.

I didn't buy because it was a step onto the property ladder. I bought because it was less of a gamble than renting. I ended up staying in my first house for 17 years, whereas my record under a single landlord was 3.

> Maybe in 10 years I want a year off? What then? Maybe I want to change careers to something less intellectually demanding. Maybe I want to spend 50 hours a week with my kids. None of those are feasible if I need the salary.

During those 17 years I took at least two pay cuts, and multiple 2-6 month breaks between jobs, all affordable because I owned rather than rented. Lower outgoings made it possible to save more, plus my mortgage provider offers payment holidays. No landlord ever did!

> I opt for quality of life, which I don't achieve by giving it all to some property-owning entity who sells it to me at 3 times the price they paid a couple decades ago.

I mean, isn't "paying rent to a private landlord" doing just that? Except "sells it to me" is actually "allows me to live there, until they decide not to" and all the money you spent is gone.

† I lucked out with a lump sum/windfall through my employer; I'm making no claims that getting a deposit is easy/attainable

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @11:56AM (#31194120)
> and multiple 2-6 month breaks between jobs, all affordable because I owned rather than rented

Indeed! I've taken a long break from working to be with my child, which I could afford to do only because I'd bought a home years earlier. If I'd been renting with ever-increasing rents I never could have done that.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throw8383833jj on Thursday April 28, 2022 @12:43PM (#31194783)
house ownership is just a legal construct. you don't really own the house, even when it's paid off. even if you own, and pay off the entire house, you'll still have to pay "rent" in the form of property taxes, an unfortunate reality.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by olyjohn on Thursday April 28, 2022 @01:21PM (#31195286)
In some places that can be a lot of money. Like New York, I hear property taxes are close to half your mortgage. In places like Washington, property taxes amount to a few thousand dollars a year on a modest house. I'll pay that over $2000/mo in rent any time.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mrep on Friday April 29, 2022 @09:54AM (#31205107)
About a third of my mortgage payment here in chicago is for escrow.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ClumsyPilot on Thursday April 28, 2022 @02:01PM (#31195910)
> house ownership is just a legal construct

Stange argument, all rights are legal contructs - how do I know my employer will pay me for work done, or my neighbour won't rob be in my sleep and slit my neck?

If we don't trust legal constructs, we can't have a civilisation.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throw8383833jj on Thursday April 28, 2022 @03:28PM (#31197105)
You can trust them, that's not the point. the point is, you can keep your pen or your calculator without having to pay rent on them. You can't keep your land/house unless you pay rent on it to the govt. Considering that all humans require shelter to continue living (surprising: the homeless in the US die 30 yrs younger than the average), a case can be made that property taxes for a minimum amount of land necessary to live are unreasonable. otherwise it's a tax on life
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ak217 on Thursday April 28, 2022 @05:37PM (#31198518)
That case doesn't work because the property taxes mostly fund essential local services that are also necessary to live and have a functioning society - there are many locales in the US where the property taxes are zero but there are no improvements or people around you.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by darrenf on Thursday April 28, 2022 @01:17PM (#31195221)
I'm in the UK. AFAIK we don't have any ongoing property taxes to pay, at least not if I have bought the freehold. Leaseholders may have to pay ground rent, but that's often a peppercorn and anything above that is being legislated into oblivion this year[0].

Regardless, ownership is a useful legal construct the benefits of which seem to outweigh those of being a tenant.

[0] https://landlordknowledge.co.uk/ground-rents-banned-under-ne...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throwaheyy on Thursday April 28, 2022 @03:33PM (#31197175)
Do you pay council rates? That’s what are called property taxes in the USA.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by darrenf on Thursday April 28, 2022 @04:09PM (#31197591)
Ah yes, there’s council tax - but tenants pay that too, so it’s not a difference between the scenarios. Also I wouldn’t want or expect to stop contributing to local services just because I don’t have a mortgage!
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throwaheyy on Thursday April 28, 2022 @05:55PM (#31198679)
Tenants in the USA do not pay it directly but do so effectively by proxy, because they pay rent to the landlord and the landlord pays property taxes to local government.

Property taxes in the USA go towards local government services like garbage collection and street maintenance, just like council rates. So I believe property tax and council rates are still analogous.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by foobarian on Thursday April 28, 2022 @09:00AM (#31191924)
You seem like an engineer, so you should be able to start up a spreadsheet, put down a bunch of reasonable numbers, and project forward 20-30-40 years and see what makes sense for you. If a loan is involved, read up on the IPMT Excel/Google Sheets function! [1]

I don't know how things work where you are, but here in the US if you are renting, you are essentially helping someone else pay their debt. And they can kick you out when they please. The main benefit is that you can stop paying on a much shorter time scale (1yr lease contract?) or take time off, but if you don't rent you should require a smaller cash flow which should be possible to save up for.

One last thing, don't forget that you can sell the property in the future (or even rent it out, hence letting someone else pay YOUR debt). That should factor in your cost/benefit calculations. Even if it does not appreciate at crazy rates like the current insane market has led us to expect, it will very likely be a lot more than zero.

[1] https://support.google.com/docs/answer/3093175?hl=en

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Beldin on Thursday April 28, 2022 @06:10AM (#31190733)
Around here, monthly rent is as high as or higher than mortgage payments. With mortgage payments, you accrue ownership (for the "standard" mortgages around here). If you expect house prices to remain stable or increase during your residency in a property, ownership financially makes more sense.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by antiframe on Thursday April 28, 2022 @09:14AM (#31192051)
Why do people compare monthly mortgage amount and rent? It misses several big elements to housing costs: taxes, maintenance, closing costs, realtor costs, and opportunity cost of the money tied up.

Renting vs buying comparisons need to account for lot more than those two numbers but that's all I see posted most of the time.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Dave3of5 on Thursday April 28, 2022 @12:25PM (#31194541)
It's very hard to compare some of those things as they differ from home to home and country to country. Here in the UK most landlords will do extreme minimal maintenance and taxes on the house are paid directly by the tenant and not included in your rent.

"Realtor costs" are again different some estate agents in the UK charge a % of the sale price others a minimal fixed cost.

I'm sure that these things differ massively in different countries as well so it's hard to put an average number on that.

In terms of opportunity cost of the money again it depends on how you would invest that money you could put it in something very high risk and show a huge imbalance in buying a home vs investing in crypto or something like that. In the UK most low risk savings accounts will track lower than inflation on a property only the stock market will track higher but again that's higher risk and so not comparable. Also most savings accounts in the UK are capped at a max amount that can be saved per year.

As I said though if you try to compare mortgage vs something like stock market it's not really comparable. Also to note the large index funds in the USA track much higher on average than most other countries.

I've seen people use the S&P as an example that house prices don't track to the same amount and that you can compound any gains to make large sums of money. What's interesting about this is that the reason you make so much money with that model is that compound interest is non-linear in growth which means over say 40 years you make most of the growth at the end of the period (Literally in the last 20%). This also means that if the end of your growth curve ends on a bad few years for the S&P you'll do much worse than the average so the risk is still very high on even index funds.

Overall though my current mortgage cost is 2.5 x lower than rent for a comparable property. So you'd have to factor in the opportunity cost of that extra per month I save not paying into rent into your equation as well.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mbg721 on Thursday April 28, 2022 @09:41AM (#31192320)
Maintenance is a big one. When you pay for an apartment, you're also paying for the landlord to fix plumbing/electrical/whatever issues.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ChuckNorris89 on Thursday April 28, 2022 @01:22PM (#31195309)
>When you pay for an apartment, you're also paying for the landlord to fix plumbing/electrical/whatever issues.

Not always, in some EU countries, some rental agreements have the tenant pay for certain maintenance, plus insurance.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rchaud on Thursday April 28, 2022 @12:15PM (#31194382)
Many banks set up blended payments so your mortgage payments include property tax. Closing costs occur at the time of purchase and are one-time fees, not recurring. As for the opportunity cost, it's only relevant if your mortgage+taxes are higher than what you were paying in rent.

The big unpredictable element is home repair costs.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by almost_usual on Thursday April 28, 2022 @10:00AM (#31192550)
You can write off a good chunk of the interest paid on a mortgage come tax season. Saved me thousands of dollars in taxes this year.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by smugma on Thursday April 28, 2022 @09:38AM (#31192272)
Most places in the US, a mortgage from 5-10+ years ago will be less than renting an equivalent place, but a recent mortgage will be higher because prices have gone up so much.

This is generally true because prices generally go up. My brother almost bought a $200K condo in SF 30 years ago but it was slightly out of reach on his $60K Sun micro income, and his $500 room for rent was cheaper. The condo has gone up about 8X and rent (assuming market rate, it was under rent control) 5X. So as expensive as it is to rent in SF, it’s relatively more expensive to buy. It’s unknown if that trend will continue. It doesn’t seem rational but the city seems intent on continuing to severely restrict supply.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ac29 on Thursday April 28, 2022 @02:53PM (#31196669)
Where do you live? Mortgage rates are over 5% now, which means >$5k/year per $100k mortage just in interest.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @05:52AM (#31190615)
If in 10 years you want a year off is your landlord going to give you one?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bombcar on Thursday April 28, 2022 @09:01AM (#31191931)
I think he’s saying that in ten years he can stop renting and shove everything into a storage unit and go travel.

The rent/but dichotomy really comes down to what axis of “freedom” you want to optimize for, and if you want to stay in the house and area more than 10 years.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ClumsyPilot on Thursday April 28, 2022 @02:09PM (#31196021)
"think he’s saying that in ten years he can stop renting and shove everything into a storage unit and go travel."

He can rent out the house and travel. And probably make money.

Aibnb or estate agents, managed properties, whatever.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @11:51AM (#31194055)
> "No debt" is synonymous to freedom on so many levels in life design.

No debt is indeed great freedom in general.

But housing is different. Do you plan to live somewhere? You still have to pay for it. For as long as you live you'll need to live somewhere and that means paying for it. Whether you call it rent or mortgage, you're still paying, there's no escape.

So, within those constraints, it is better to invest in a house than to enrich someone else for the rest of your life.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by possiblelion on Friday April 29, 2022 @02:11AM (#31201960)
I just wanted to say that I agree 100% with your worldview. It's hard to explain it here often. Maybe it's a Protestant thing? From Estonia here.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ChuckNorris89 on Thursday April 28, 2022 @06:00AM (#31190672)
>Oh, Germany. Somehow Germany has escaped the constantly increasing house price effect

I hope that was sarcasm since housing in Germany has gotten super expensive.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by yurishimo on Thursday April 28, 2022 @05:59AM (#31190658)
Japan I think is a bit different. Over there, housing is seen as a real commodity. In Tokyo, housing is torn down and replaced with newer stock all the time, often without any additional occupancy. Houses in Japan do not appreciate the way they do in the rest of the Western world.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by JackFr on Thursday April 28, 2022 @07:35AM (#31191278)
> Going into debt at the lowest interest rate you'll ever be offered to buy a leveraged asset that's likely to increase in price

To a large extent house prices are sensitive to interest rates. A bank will look to your income and say you can make a monthly payment of $X. At historically low interest rates that’s gonna mean a bigger loan. As everyone’s ability to borrow goes up, so do the prices. As rates rise, for the $X dollar payment, the ability to borrow declines, and that puts a down draft on house prices.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by conanbatt on Thursday April 28, 2022 @12:27PM (#31194559)
> buy a leveraged asset that's likely to increase in price and reduce the overhead you pay on your largest expense

Oh boi. When you buy this you are giving all this benefit to the seller that takes these into account. You are not making a profit off of it unless the value increases more than the market expectation for it.

So its a leveraged bet that it will be better than expected by the market, and if it goes the other way you are toast.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @05:31AM (#31190434)
I own a house in London. Its total value increase since I bought it 5 years ago is much less than my salary.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by celticninja on Thursday April 28, 2022 @06:31AM (#31190867)
You bought near the peak of the market then. Definitely been some downward pressure on prices since covid as people sold up in London, took that premium price and moved to larger properties elsewhere. Not saying it was a bad investment, just that the return will take longer than it has in the past.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @07:37AM (#31191295)
It doesn't matter where I bought. If I haven't made much money in the last 5 years, nor has anyone else (on average), regardless of how long they've owned their property.

The suggestion that 'the return will take longer than it has in the past' is a prediction with no evidential basis.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by IG_Semmelweiss on Thursday April 28, 2022 @04:35PM (#31197889)
Isnt that exactly the scenario that op is describing?

Lack of flexibility at precisely the right time?

Owning in any large city + servicing debt during the pandemic when you must move elsewhwre that is sane (and less risky to your health) would seem to have a premium attached to it

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nly on Thursday April 28, 2022 @07:43AM (#31191350)
Then I guess your salary is amazing, because many house prices across London have doubled in 5 years.

If you somehow bought a house at a reasonable earnings multiple, say 4x earnings, then your house has appreciated essentially what you earned over the last 5 years. This is just math.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @09:01AM (#31191932)
Can you tell me an area where average house prices have doubled in the last 5 years? I can't think of one. Most expensive areas have gone sideways since Brexit, and risen a bit since the pandemic. Most cheap areas have grown slowly since Brexit.

https://www.bloomberg.com/graphics/property-prices/london/ shows the median as having gone up around 6% in total since 2017. Trying a mix of neighbourhoods in that tool, I can't see any which are close to 100% up.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nly on Friday April 29, 2022 @04:26PM (#31210206)
Me and my partner are looking for a house in zone 3-4 right now, and I can tell you that every single home we've looked at is on for an asking price (and they're selling) of between 50-100% more than they last sold for 5 years ago.

We looked at a home that sold for £415K in 2017 for example and we were outbid. It went for 865K

Flats aren't so hot, that's for sure, but there's been masses of price growth over the last 5 years on houses. There's a stunning lack of stock on the market.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by thiago_fm on Thursday April 28, 2022 @12:58PM (#31194965)
Berlin prices has been growing at crazy speeds, it might have doubled the last 5 years. Even with a lot government intervention(rent raises cap etc).

The situation is so bad that there isn't even housing stock available. You are generally better off moving out or buying whatever you can.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by blitzar on Thursday April 28, 2022 @01:49PM (#31195732)
London Prime Property: Our forecast for growth of 24% in the five years to 2026 means that by the end of the period, values will return to their previous 2014 peak level for the first time. [0]

[0] https://www.savills.co.uk/research_articles/229130/323909-0

12 Years underwater... optimistically given that its already not looking great for their 8% prediction for 2022

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @09:02AM (#31191944)
I mean the folks that bought homes in Detroit in 1960 probably feel a bit different in 1980.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by eadmund on Thursday April 28, 2022 @10:36AM (#31192988)
> I just turned 30 and do well for myself as an employed consultant, but I wouldn't consider buying the dip, unless the dip is at least ~100% of the current market prices (which I don't see happening, but who knows).

You wouldn't buy a house unless it was essentially free? A dip of ~100% means prices at ~0% their current level.

> Going in debt for 30-40 years has zero appeal for me, it just seems like a terrible move.

Debt on its own doesn't matter so much. You already know that you will need to live somewhere for the rest of your life, so that expense is unavoidable. The question is whether you want the amount of that expense to fluctuate according to the market, or if you want to lock in a steadily-decreasing expense with a 30-year fixed rate mortgage (steadily decreasing in real terms, because $100 in 30 years will be worth $50–60; yes, property taxes are likely to increase, and maintenance will move with the market, but mortgage interest and principal will decrease in real terms).

> Even if someone gave me a million Euros, I wouldn't spend 600k of those on a house and then another 300k on renovations, that seems like a terrible waste of resources. With that kind of money, you can buy three small companies in Germany, or stop worrying about retirement, etc.

$1.05 million is hardly enough to live on. That's just $35,000 per annum. It's not nothing, and I surely wouldn't sneer at a gift of $1.05 million, but it wouldn't let me retire today.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by thiago_fm on Thursday April 28, 2022 @12:45PM (#31194809)
35K year is a lot of money. It is close to the average yearly salary in Germany, the country he has mentioned, and this is not including taxes etc.

So is $1mi. For a lot of countries, this is money you could retire on.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @05:10AM (#31190280)
This is fair, you didn't miss those people. But I think it was worth me highlighting them because they are, as I argued, very important.

I somewhat agree with your argument. Housing costs more than other assets compared to its economic value, exactly because people have an emotional reaction to the idea of owning it - or the idea of not owning it.

However I have seen middle-class people overextend themselves to 'buy the dip', while their equally wealthy peers sit it out, for over 15 years now. Many of the people who did the former now consider themselves to have got a bargain, while many of the latter changed their minds and ended up buying several years later and at much higher prices.

I'm definitely not arguing that this makes buying right and renting wrong! Just that so far, this is how that choice played out.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by pooper on Thursday April 28, 2022 @05:34AM (#31190465)
A real estate investment newsletter suggests that for a successful real estate investment, as a rule of thumb you should be able to charge almost one percent of the cost of the house as rent because a rational investor shouldn't count on the value of the house going up.

I am curious what you guys think of this statement. I think the idea is if the potential rent you get out of your investment is too much under one percent, you might be better off investing in something else?

Now imagine a smallish 4 bed, 2 bath, 1,638 sqft built home on a 5,861 sqft lot in Longmont, Colorado (so not exactly a city but my preference because municipal fiber) that has a sticker price of USD 499,900. I can't imagine paying USD 4,999 every month in rent for this house at the moment. What gives? Is rent too low? My instinct is home prices are way too high but it can't just be "dumb money" keeping prices high, right? Eventually, there should be more supply causing prices to drop? Is something preventing this correction? If so, how do we fix it?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @05:45AM (#31190543)
An old rule of thumb was 'buy at 10, sell at 20'. That's the ratio of price to annual rent. So if you could get 0.86% of the house price in monthly rent, it was a big bargain. If you couldn't get more than 0.43%, then it wasn't worth owning.

The rule of thumb is now obsolete, and 30-40 times rent is perfectly common in lots of places.

The newsletter is quite a lot more aggressive than even the rule of thumb from the 'good old days' when interest rates were much higher.

I used to pay around 0.2% of the market price of my apartment per month. The landlord was a professional property management company, and this situation persisted through several new contracts.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bombcar on Thursday April 28, 2022 @09:05AM (#31191965)
House prices are kind of attached to rent, but not entirely - especially in areas where there are few rentals, or lots of them.

Actual rental revenue received can be significantly lower than calculated if there are vacancies, etc. It’s much easier to do on an apartment building with many units.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ddorian43 on Thursday April 28, 2022 @06:59AM (#31191049)
> A real estate investment newsletter suggests that for a successful real estate investment, as a rule of thumb you should be able to charge almost one percent of the cost of the house as rent because a rational investor shouldn't count on the value of the house going up.

Does this have all taxes(property,rent,etc) included in the cost?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by pooper on Thursday April 28, 2022 @07:31AM (#31191245)
As far as I remember, no. This is just the sticker price. This is a conservative estimate for people who are not real estate professionals, probably looking to buy a house to rent for the first time. Based on the other comment reply, it sounds very conservative to dissuade people from making stupid decisions.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @11:41AM (#31193909)
> Going in debt for 30-40 years has zero appeal for me, it just seems like a terrible move.

That's not the best way to look at it.

Unless you plan on being homeless, you're already inevitably committed to a monthly housing payment for most of your life.

So the decision becomes, do you pay someone else to enrich them and commmit to having to pay for the rest of your life? Or do you invest in something where you partly pay yourself and there is an end (even if far) to the payments, so when you're old you no longer have those monthly payments?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rchaud on Thursday April 28, 2022 @12:07PM (#31194274)
> With that kind of money, you can buy three small companies in Germany, or stop worrying about retirement, etc.

What are the closing costs of purchasing a whole company? How much would you pay for an accountant to go over the books and a lawyer to go over the forms?

I don't know how much homes cost in Germany, but surely if people have 600k to spend, they would buy companies too, would they not? Why do they buy homes instead?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mring33621 on Thursday April 28, 2022 @09:45AM (#31192365)
Thank you for your comment. I think this is interesting:

"Higher rates will make current prices unsustainable. As soon as they correct to the point where monthly payments are back to what they were last year, there will be buyers, only too happy to overextend themselves to get out of renting."

So, higher rates are effectively a transfer of wealth from homeowners to banks? How does this serve to combat the current inflation issue?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @09:59AM (#31192530)
I don't understand how you draw this conclusion from what I said.

Regardless of high or low rates, banks borrow low and lend high, and live on the difference.

High rates, if you want to express yourself in those terms, a transfer of wealth from people with debt to people with assets.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by stevenhuang on Thursday April 28, 2022 @04:22PM (#31197732)
This captures my assessment on the matter.

With the housing shortage and unmet demand, we are at the margins whereby the ones buying are well-off.

The question to ask is if the rate of new housing and the rate of capable buyers will diverge.

As long as supply is low enough that the supply of capable buyers keep outbidding each other, housing prices will keep rising or at least plateau.

Higher rates will have an affect on diminishing the rate of capable buyers entering the market, but if supply is still low and the demand for home ownership remains high, I don't foresee anything drastic happening to the housing market.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throwaway0a5e on Thursday April 28, 2022 @07:40AM (#31191316)
The real irony is that these people putting a floor on the market are mostly the same demographics screeching about how housing shouldn't be an investment.

Yet another case of how society would be better off if people practiced what they preached.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xadhominemx on Thursday April 28, 2022 @09:00AM (#31191915)
> The true demand from people with the intend to actually live in the estates has been constantly decreasing since around 2000; the real salarys dropped since then, so did the buying power.

> When 90 (?) percent of people simply lack the buying power to participate in the real estate market, but the other 10% happily sell each other estates, that's not a bubble, the real estate market just stopped interfacing with the vast majority of the population.

Nonsense. The home ownership rate is 65%, in-line with the long term average and the same as it was in the year 2000

https://fred.stlouisfed.org/series/RHORUSQ156N

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mirntyfirty on Thursday April 28, 2022 @10:44AM (#31193091)
I’d disagree in the sense that the home ownership population differs from those that have been buying or selling in the last few years.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xadhominemx on Thursday April 28, 2022 @12:52PM (#31194887)
If millennials were not buying homes at similar rates to their parents, the home ownership rate would be declining
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jeffreyrogers on Thursday April 28, 2022 @02:15PM (#31196111)
People still talk about millennials as if they are still in their 20s, but the oldest millennials are now 40. I'd guess that age of first home purchase has been trending up for a while.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ClumsyPilot on Thursday April 28, 2022 @01:43PM (#31195648)
There is no need for hypotheticals, we know for a fact they are not buying homws at a similar rate as their parents
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xadhominemx on Thursday April 28, 2022 @03:09PM (#31196863)
Home ownership rates for people under 35 is the same as it was in the mid-90’s and only a few % lower than it was at the peak of the housing bubble
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by petra on Thursday April 28, 2022 @02:16PM (#31196118)
More people are investing in real-estate, and less millenials are buying.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by alistairSH on Thursday April 28, 2022 @03:48PM (#31197344)
Millennials made up 43% of home-buyers in 2021, the largest of any generation. That's up from 37% in 2020.

https://www.nar.realtor/newsroom/nar-report-shows-share-of-m...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by eli_gottlieb on Thursday April 28, 2022 @11:30AM (#31193732)
>Nonsense. The home ownership rate is 65%, in-line with the long term average and the same as it was in the year 2000

The homeownership rate is counted in terms of households, no? So it can be kept artificially high just by having 20-somethings no longer move out of their parents' houses.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mminer237 on Thursday April 28, 2022 @12:02PM (#31194212)
That wouldn't count against it, but it wouldn't count for it either.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bogomipz on Thursday April 28, 2022 @01:41PM (#31195610)
The Baby-Boomer generation in the US is increasingly deciding to "age in place" rather than downsize and/or move to assisted living facilities. This is certainly a factor in the ownership figure you are quoting. There has been lots of coverage in this trend the last few years as well. See:

https://www.nytimes.com/2021/07/08/realestate/baby-boomers-r...

and

https://archive.ph/0LXQu

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by tzs on Thursday April 28, 2022 @07:09AM (#31191114)
> that people were given loans they should either never have gotten (2008) or that they shouldn't have asked for

I bought my house in early 2007 and mortgages were indeed crazy back then. My analysis said that at the mortgage rates for a 30 year fixed mortgage back then (a tad over 6%) said that my ideal home financially would be around $H or less, that I could go up to 1.25 $H without house payments being high enough to crimp my currently lifestyle, and maybe I could push it to 1.5 $H if the house and location were really great.

When I went to get a mortgage from the now infamous Countrywide Financial they looked at the same data I had and pre approved my for a loan of around 3 $H.

That was an absolutely ridiculous amount. I had the analysis to prove that, so just laughed and went back to looking at homes in the under 1.5 $H range [1].

A lot of people who didn't know how to do their own analysis thought that the mortgage companies would only approve them up to what they could reasonably afford, and so getting a pre approval for much higher made them think they could actually afford way more expensive houses than they actually could.

[1] In case anyone is curious, I found a house that was almost perfect as far as size, layout, and location for 0.9 $H and almost bought it, but then found that its water source was a well owned and shared by a group of 4 houses. I could not get satisfactory information on how maintenance and repair of the well was handled. I ended up with a place a little bigger, in a better location, but without quite as nice a layout for 1.16 $H.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by geoduck14 on Thursday April 28, 2022 @07:44AM (#31191362)
I'd like to provide some context around the approved amount. Countrywide (and other originators) get their rates from Fannie Mae and Freddie Mac. These two have guidelines set to approve X monthly payment based on your income (for instance, you can spend 28% of your income on your primary house).

These guidelines are set for BROAD populations - specifically very poor and "normal" people have the same guidelines. For poor people, a high threshold is important to "get them in a house" - they might genuenly need to spend 30% of their income on rent or mortgage. For "normal" people, that same percent is "way too much money" for "way too much house".

The result is that normal people get approved for a big fat mortgage. But we don't want a big fat house, we try and buy a normal house, but we really want it so we pay "just a little more than it is actually worth" and drive the price up "just a little".

Of note, FNMA and FDMC adjust their guidelines for high COL areas and some other guidelines. And also, their guidelines have moved over time. Also, it is a generally accepted "fact" that home ownership is good, and poor people should be encouraged to buy a house.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by tialaramex on Thursday April 28, 2022 @08:23AM (#31191628)
> Also, it is a generally accepted "fact" that home ownership is good, and poor people should be encouraged to buy a house.

Which has the undesirable effect that it makes it difficult for workers to move to where the good jobs are, so now you have situations where workers are stuck in place A, doing job 1 for $X even though they should probably go to place B, and do job 2 for $Y -- because to move from A to B they'd have to buy a house in place B, and sell their house in place A, which is both annoying and relatively expensive.

This varies culturally, IIRC Poland and Germany - despite being neighbours - have different cultural assumptions about whether it's "normal" to buy a home rather than renting.

Maybe a shift to more Work From Home reduces the problem by allowing workers to take more jobs in place B despite actually living in place A.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by _fat_santa on Thursday April 28, 2022 @09:39AM (#31192302)
> But we don't want a big fat house, we try and buy a normal house, but we really want it so we pay "just a little more than it is actually worth" and drive the price up "just a little".

The problem here is really with the supply of homes. If there was a good supply, issues like this would never arise, or would rarely arise, because there is always a house just as good down the street that you don't have to overpay for.

Part of the problem is the supply chain but I bet alot can be done by the govt to get out of the way. Of course the other side of the coin is activists that scream both: "We need more housing" and "how dare you build more housing" in the same sentence.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by brianwawok on Thursday April 28, 2022 @07:57AM (#31191448)
Imagine if billionaires used the 28% rule.

Important to compare like renting a modest Apartment. If that payment that works for you is X, maybe 3X is too much house? Houses also take a lot of repair, and need things like new roofs and HVAC.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by treeman79 on Thursday April 28, 2022 @08:21AM (#31191614)
Billionaires buy houses by the thousands and then rent them out.

There are a few areas of the country where you basically cannot rent from a private party anymore. 90%+ are one of a handful of mega rental corps.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by maxerickson on Thursday April 28, 2022 @08:17AM (#31191584)
Out of curiosity, would a new well have been possible for less than 0.26 $H?

(to separate the house from the group, not a maintenance hedge)

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bluGill on Thursday April 28, 2022 @08:48AM (#31191820)
Figure a well can be drilled for a few thousand. Depends very much on the area though, some locations you can get plenty of water from a small hole not very deep (you can pound a pipe into the ground - with a hammer, put a pump on top and get plenty of water). Other places you have to go very very deep to get water and even then you have to be careful not to use too much. And there is all kinds of in between. Worse, sometimes one side of the lot will have plenty off water and the other will not. Then you have to watch for local issues, keep the well far from the septic system (including your neighbors).
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by tzs on Thursday April 28, 2022 @08:56AM (#31191884)
Good question. It didn't occur to me to check. A bit of Googling suggests that in my state a new well would indeed have been less that 0.26 $H. At the high end of depth for this area maybe 1/3 of that.

I have no idea if it would have actually been possible, though. Wells aren't allowed to be too close to septic tanks and septic drain fields, and there are other spacing constraints too. From what I recall of the way the house was placed on the lot and where the septic tank and drain field were there may not have been anyplace on the lot acceptable for a new well.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bombcar on Thursday April 28, 2022 @08:50AM (#31191829)
Almost certainly-if any new well were allowed at all.

Could also have assumed that a well problem would entirely fall on you (worst case) and budget accordingly.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by darkerside on Thursday April 28, 2022 @08:51AM (#31191839)
Good luck rolling that into your mortgage
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by hibbelig on Thursday April 28, 2022 @07:42AM (#31191343)
Not familiar with this topic. What does $H mean? Annual gross salary?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by voidfunc on Thursday April 28, 2022 @08:02AM (#31191490)
$H is the price of the house in OPs post.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by brianwawok on Thursday April 28, 2022 @07:58AM (#31191456)
Just a number he made up for a story.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by frostiness on Thursday April 28, 2022 @08:55AM (#31191875)
I figured it was $100,000 but I could be wrong.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by misja111 on Thursday April 28, 2022 @04:57AM (#31190204)
> When 90 (?) percent of people simply lack the buying power to participate in the real estate market, but the other 10% happily sell each other estates, that's not a bubble, the real estate market just stopped interfacing with the vast majority of the population.

This. And it was not only happening in the housing market, but also in a few other markets such as arts and certain jewelry. What happened during the last ~10 years is that the huge loads of money pumped into the financial system by central banks ended up with only a select group of people, who just got richer and richer and were looking for ways to spend or invest their excess money. And that caused an inflation in the markets where they liked to spend it.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by chasd00 on Thursday April 28, 2022 @09:32AM (#31192223)
I think the bulk of the inflation we’re seeing is from the pandemic where we shut off production by making everyone stay home but then dramatically increased demand by writing everyone checks.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by alimov on Thursday April 28, 2022 @03:11AM (#31189592)
maybe one more interesting detail worth noting:

c) private equity firms are buying up insane amounts of real estate, being able to outbid regular home buyers and (don’t quote me on this b/c I’m not 100% sure) pay cash for the properties they buy.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by vmception on Thursday April 28, 2022 @03:44AM (#31189788)
Which they only did because they ran out of stuff to invest in (while still attracting so much other capital to invest at all), and the valuations of everything else was already stretched. not suggesting these firms were trying to do anyone favors by allowing people to afford homes the rest of the time, its more so that the math temporarily made sense with that much liquidity in the market so they jumped into real estate

(And yeah people would rather pay the government than invest in your startup so lets not pretend investing in main street was a real option)

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by IMSAI8080 on Thursday April 28, 2022 @07:06AM (#31191096)
Too much cash chasing too few decent investment opportunities is exactly the problem. The more cautious end of institutional investors have nowhere to go. Blue chip shares are at incredibly high valuations and bonds are returning next to nothing. Interest rates needs to be at about 3 - 4% to make government bonds broadly attractive, which will then make residential property uninteresting to this kind of investor without putting too much strain on the regular home buyer.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cascom on Thursday April 28, 2022 @05:23AM (#31190374)
There have been a lot of headlines about this, and in the handful of markets I’m sure this has a price effect, but in the us market as a whole, they are $10b-$100b? of a ~25T market, it just doesn’t move the needle
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by yurishimo on Thursday April 28, 2022 @06:21AM (#31190802)
It doesn’t need to be spread out to have an effect. If the investments are concentrated in cities, that raises the price of housing in the surrounding areas as there is more demand for rural properties from city residents trying to escape the higher prices.

Anecdotally, I’m seeing crazy numbers for “average” houses in the small towns surrounding the DFW metroplex. Hell, the house my parents built in 2006 for $140k is now selling for $350k. 1200 sqft mass produced trac home.

But it’s an hour drive to downtown Dallas (less if no traffic) so plenty of people are commuting but making city salaries. It’s the same in every city across America.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cascom on Thursday April 28, 2022 @06:52AM (#31190989)
There are 950k homes for sale in the us today (down from 1.05m a year ago)…if I sold $50b of homes tomorrow @ $430k median price = 120k that would bring inventory levels back to where they were a year ago and represent 2% increase in annual home sales (on ~5.8m), by your logic national home prices would drop…I don’t think that’s a large enough number for that to happen… maybe if I sold $0.5T?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by onlyrealcuzzo on Thursday April 28, 2022 @07:53AM (#31191414)
You're forgetting a.2) the "wealthy" people usually have high incomes, and the x10 houses are usually in high tax states, and housing is a huge tax break.

~20% or my housing "cost" is paid for by a tax break for owning a house. Another ~20% is principal.

When you also factor in that the Fed guarantees to devalue money at AT LEAST ~3% per year, and you have 5x leverage (or more) - that's another ~15% effectively subsidized by the government.

So when you have sufficient cash flow - it's easy to look at your housing "cost" as only ~40% of the actual payment.

Compared to rents, this is a steal.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cactus2093 on Thursday April 28, 2022 @11:46AM (#31193967)
With the SALT cap at $10k and the mortgage interest deduction cap limited to $750k property value, the ultra-wealthy are not really benefitting from this as much as you are saying.

Someone with a $750-$1M home is getting roughly the maximum tax break available, and someone with a $5M home is paying for everything above that first $1M themselves* without any extra tax incentives.

*Except in California due to prop 13 many of them are paying a tiny fraction of the property tax they should be paying, but that's a separate issue.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by onlyrealcuzzo on Thursday April 28, 2022 @11:52AM (#31194074)
Most "wealthy" people, by definition, are not "ultra wealthy". That's where the majority of the wealth is - but there's far better schemes to avoid taxes for that group.

Home buyers buying these x10 houses are pretty much limited to the top 10% in income - the vast majority of them are not ultra wealthy.
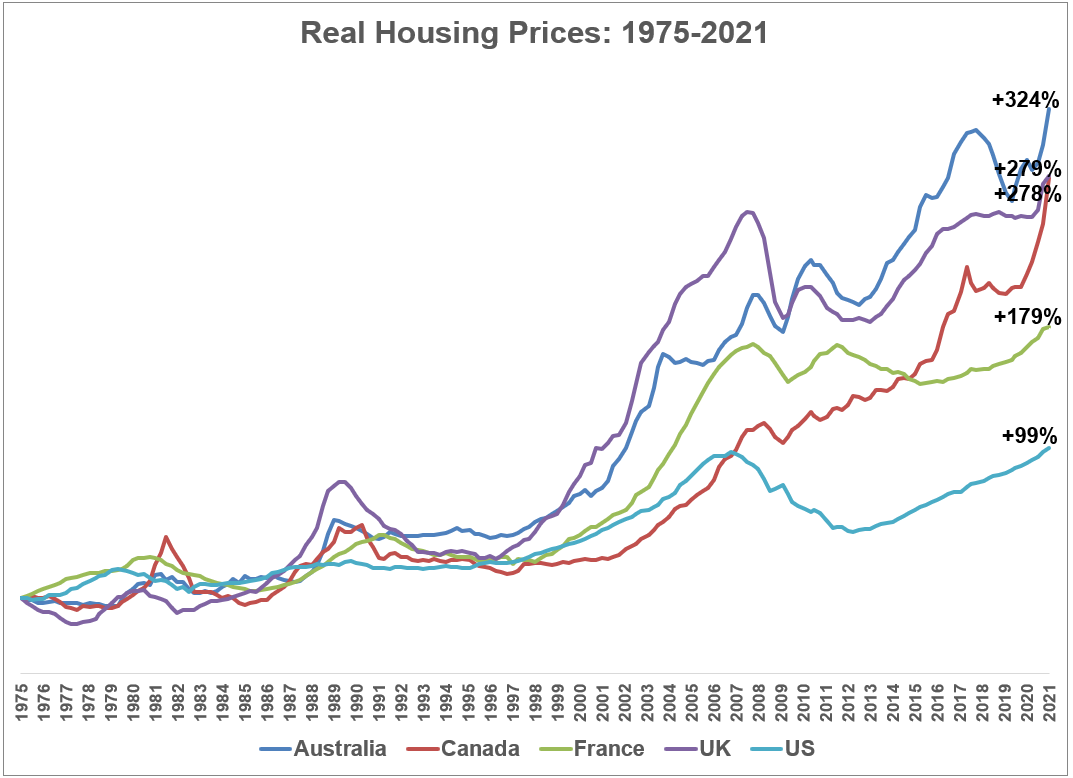
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cdiddy2 on Thursday April 28, 2022 @03:18PM (#31196968)
Its really not that bad in the US especially compared to its peers https://awealthofcommonsense.com/wp-content/uploads/2021/09/...
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by babypuncher on Thursday April 28, 2022 @01:02PM (#31195025)
And it will probably stay a leak, even if it grows. People keep expecting another collapse like 2008 but that does not seem likely to me. People need houses to live in, so demand will always be there. And unlike 2008, banks aren't handing out sketchy loans en masse to people who cannot reasonably afford them.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rvba on Thursday April 28, 2022 @03:33AM (#31189726)
Due to QE central bank bought stock from private equity - and private equity used thia money to buy homes.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xadhominemx on Thursday April 28, 2022 @08:56AM (#31191882)
What you wrote is complete nonsense
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by rvba on Thursday April 28, 2022 @02:14PM (#31196093)
So where did the QE money go?

It causes bubble after bubble while central bank holds the bag.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by crate_barre on Thursday April 28, 2022 @03:02AM (#31189538)
Housing legislation is something that few politicians have been talking about in the last decade. We have spent a lot more time talking about healthcare, and student debt, but not the number one financial factor which is housing. You really can’t leave it alone with legislation every 20 something years, you sort of have to keep evaluating and reevaluating it. Otherwise while we let the current systems in place fester, what you get is side effects that we simply can’t address until decades later (e.g Canada banning foreign buyers, ok great, the damage has already been done).

Many of the investor class had the first mover advantage where they simply bought a house before everyone else and can now leverage those gains into more investment/rental income property. Couple that with foreign investment. Couple that with home equity and margin loans. Couple that with the private sector collecting houses. Couple that with mortgage fraud where people don’t pay investor taxes and continuously buy homes as a first time home owner. Couple that with with all kinds of things. I know a home owner that owns multiple homes, stopped paying taxes on one and had a tax lien discharge. They go on to sell that other home at profit and pay off the IRS. They never took the hit on their first home in any way. Multiple ownership is a problem, period.

We finally end up to where we are today and the only powerful entity that modulates this is the Fed, but not a single politician is taking up the battle over the fact that the multiple home ownership is killing our society at the moment.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jwilber on Thursday April 28, 2022 @03:07AM (#31189570)
Couldn’t agree more. Another issue: home owners are incentivized to see their assets appreciate.

Makes passing meaningful legislation hard, especially if it will actively hurt a substantial number of voters (and every politician).

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:07AM (#31189568)
That's really high compared to Europe!

I just bought a new house with 2% on the interest-only part and 1.6% on the annuity part!

In the month after rates grew by about 0.5% though. Seems like we hit the bottom and are climbing very slowly.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oliwarner on Thursday April 28, 2022 @03:33AM (#31189720)
And compared to a couple of years ago, that's really expensive.

The mortgage we took out two years ago (2 year fix, ~60% LTV) had a introductory rate of 1.2%.

That falls back to 3.something variable in September. We'll probably look for another fixed but current 2yr fixed rates seem to be around 2.3% (plus a £1k application). That's an uncomfortable increase on a big loan.

What's interesting is the rates on bigger loans (eg 90% LTV) aren't much more (2.4%+application). That's not what I'd expect a bank to offer if they expected a bursting bubble.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by 2ion on Thursday April 28, 2022 @03:59AM (#31189880)
That's really interesting. Is it normal in UK (thinking £) to get such an extremely short (introductory) loan and then refinance every few years? In Germany, most people take a 10y fixed rate at least to reduce such risk.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nsteel on Thursday April 28, 2022 @04:27AM (#31190056)
Yes, here 2 and 5 years is the norm. There's talk of longer terms becoming more popular but that's probably just talk due to the current climate of rising rates. I've spoken to a few brokers lately and not one even mentioned anything longer than 5.

It feels like there's a few signs now that the so-called "18-year property cycle" is due to be cut short this time around. I've only recently heard the idea so I'm not sure how it's real it is (outside of their circles that have a vested interested in the timeline it predicts). UK lenders seem to be now toughening lending rules rather than relaxing them as they were "supposed" to. Not sure it's a good time to invest or not!

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @04:40AM (#31190126)
7 and 10 years are quite widely available now, although they're still not particularly popular.

Not sure why brokers didn't mention them to you. Perhaps they like to show people low headline rates, or perhaps they see longer initial terms as bad for the broking business?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nsteel on Thursday April 28, 2022 @05:44AM (#31190537)
I think it's both of those reasons. Collecting commission on one 10-year mortgage, or five 2-year mortgages... I doubt they get 5x for the longer term, if anything.

I'd like to understand how people think about a longer-term fixed deals. How do you know where you'll be in more than 5 years? If you need to move don't you get hammered by the ERCs? Can you really rely on transferring products?

Habito One is an interesting product, that seems to be a lifetime fix (Which I have personally never seen before the UK but maybe it exists) with no ERC! Obviously the rate is less attractive but rates are still so low and I think you can offset as well.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lmt55 on Thursday April 28, 2022 @05:51AM (#31190598)
You will get hammered by the ERCs, but with a few caveats:

  1. Often if you move house they will let you transfer your mortgage (actually take out a similar product and avoid the refi costs).
  2. If you win the lottery, or otherwise are in a situation to prepay your whole mortgage? Well you might care much less about the 5% early fees in that case.
  3. You can prepay usually 10% a year, at their discretion, without any early fees. If you just become a fair bit richer than you expected, prepaying at this level will reduce the mortgage quite quickly.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by thrwyoilarticle on Thursday April 28, 2022 @03:42PM (#31197284)
IME we had other confounding factors reducing the number of lenders available to us. It might be that they just didn't offer it.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by robga on Thursday April 28, 2022 @04:58AM (#31190212)
Not only that, it’s popular to get “tracker” mortgages. It’s the Bank of England base rate plus a fixed rate. So it’s never actually fixed. My “Lifetime Tracker” is BOE+1.29% for 25 years. So it’s varied from 1.39% to 2.04% total charge in the last 10 years. If you bought a lifetime tracker today it would be BOE+2.7%. 20 years ago they were as good as BOE+0.25%
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:39AM (#31189766)
Mine is currently 105% LTV, haha.

We will drop 0.4% once we get below 66% LTV or so. Also, ours is 20 years fixed. The variable or 5 year fixed was even lower still, around 1.5% at 100% LTV.

It's still ridiculously low, which is why we're happy to pay a bit more to get it fixed for 20 years.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by HWR_14 on Thursday April 28, 2022 @05:40AM (#31190511)
US rates tend to rise more quickly, because the standard US mortgage quoted is fixed for the life of the loan (often 30 years). Whereas a lot of European loans are variable rate, where the interest is only fixed for the first 5 or so years of the loan and then floats based on central bank rates.

So, obviously, US banks have to price more risk into their rates.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by PinguTS on Thursday April 28, 2022 @04:20AM (#31190008)
Less then a year ago the interest rate in Germany was less than 1%. Now we are over 2%. The most increases are since about February. It is not slowly growing. The speed of growing is increasing right now.

I got mine with about 1% interest two years ago and do almost 5% redemption, fixed almost over the whole time. Just 2 years or so left at the end.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by switch007 on Thursday April 28, 2022 @03:09AM (#31189582)
Is that rate fixed for 30 years?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:21AM (#31189650)
No, 20 years fixed rate on a 30 year mortgage.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by smcl on Thursday April 28, 2022 @03:30AM (#31189697)
Which country, if you don't mind me asking?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:32AM (#31189715)
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jdasdf on Thursday April 28, 2022 @03:21AM (#31189651)
It's practically impossible to get fixed rates in europe.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by colinb on Thursday April 28, 2022 @03:33AM (#31189725)
No. That’s not the case. I had a fixed rate mortgage in the UK. Now I have one in Ireland. Two of my colleagues have taken them in the last couple of months. They’re very common. But.. in both countries such terms are for a relatively short period. E.g 5 years fixed changing to SVR for the remainder of the loan. I haven’t heard of loans fixed for the entire duration. I would’ve got one if I had found it.

I can’t speak for the rest of Europe. It’s a big place you know.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xyzzyz on Thursday April 28, 2022 @04:07AM (#31189924)
That’s not what Americans mean by “fixed rate”. In US, that means 30, or more rarely 15 year mortgage, where the rate is fixed for entire duration. The mortgage where it’s only fixed for some initial period is called “adjustable rate mortgage”. Your comment just supported the person you replied to being correct, that fixed rate (in US sense) mortgage market is nonexistent in most of Europe.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by IMSAI8080 on Thursday April 28, 2022 @07:24AM (#31191197)
They're often called "lifetime fixes" or "fixed for term" in the UK. You can easily get them. The term customers choose is typically 25 years rather than 30. However they are currently running at an interest rate of a little under 4% which is much higher than the rate offered on a typical 5 year year fix. This makes them unattractive when you can just perpetually keep re-mortgaging on 5 year fixes.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @12:17PM (#31194412)
> However they are currently running at an interest rate of a little under 4% which is much higher than the rate offered on a typical 5 year year fix. This makes them unattractive when you can just perpetually keep re-mortgaging on 5 year fixes.

Renewing after 5 years will presumably get you whatever rate is then? Which might be much higher.

It's always better to get a fixed rate (for the life of the loan) mortgage. If rates go up, you're protected. If rates go down, you can refinance to cheaper rates.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by IMSAI8080 on Thursday April 28, 2022 @01:37PM (#31195542)
Well it's an unknowable gamble. You might also be locking in an excessively high rate. The flexible approach of continuously re-mortgaging would have been the better strategy for the last 10 years with interest rates that went down. In the next 10 years, who knows.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @03:33PM (#31197176)
> Well it's an unknowable gamble. You might also be locking in an excessively high rate. The flexible approach of continuously re-mortgaging would have been the better strategy for the last 10 years with interest rates that went down.

There is no gamble, that's why it is almost a free lunch. If rates keep going down as last ~10 years, you're never locked in, you keep refinancing to a lower and lower rate. If rates go up, you stay put with a fixed rate that can't ever go up. You win both ways.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by IMSAI8080 on Thursday April 28, 2022 @03:52PM (#31197385)
I didn't correctly read your comment sorry. I don't know about the US system, but here the fixes normally do have a lock-in typically on a ratchet system where they are expensive to exit in the early part of the loan and cheaper later. For example one I just checked charges you 5% of the loan to exit any time in the first 5 years and then 3% to exit any time in the next 5 years. There is also a significant discrepancy in the interest rates charged for different term lengths e.g. the offer presented may be 3.7% for a lifetime fix or 2.4% for a 5 year. So you're paying 1.3% extra for the lifetime fix right out of the gate. So the gamble is will 5 year fixes cost more than 3.7% in 5 years time? If not, then you won on the 5 year fix.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @04:14PM (#31197644)
I see, interesting! Agreed, on such a system it becomes more of a gamble to pick what might be best long term.

In the USA there is no penalty to pay off a loan and refinance (there might be exceptions but never seen one) so you can do it at any time as frequently as you like and keep ratcheting the rates down.

There's also not such a huge difference. Looking at zillow today, 30-year fixed shows 4.95% and a 7-year adjustable at 4.81%

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ericd on Thursday April 28, 2022 @04:03PM (#31197511)
30 year fixed mortgages in the US typically allow prepayment with no penalty other than some relatively nominal origination costs on the new loan, so you have a free option to lower by taking out a new mortgage when rates drop, while being protected on the other side. That combined with a few other features make them an extraordinarily good deal (especially when they have a strongly negative real rate, like now).
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by the_mitsuhiko on Thursday April 28, 2022 @05:32AM (#31190439)
You can absolutely have a 30 year mortgage that is fixed all the way through. It's rare that people take it though, most opt to 5-10 years fixed with variable late afterwards from my own experience (Austria). The standard product used to be fixed rate.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by namdnay on Thursday April 28, 2022 @05:47AM (#31190565)
In France 99% of mortgages are fixed rate, for the entire term.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by sokoloff on Thursday April 28, 2022 @04:11AM (#31189949)
In the US, the standard product for many decades was a 30 year, truly fixed rate mortgage. Any of the adjustable rate products with an initial period of fixed rates are still called adjustable rate mortgages (ARM) and are short-handed as the fixed period stroke the adjustment frequency. A 7/1 is fixed for 7 years, then adjusts every year. (Annoyingly, a 5/6 is 5 years fixed and adjusting every 6 months.)

When people in one market talk about their fixed rate mortgages adjusting rates, it sounds strange to people familiar with other markets, just reinforcing the “real estate is local” adage.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by vladvasiliu on Thursday April 28, 2022 @04:07AM (#31189927)
As others have said, "Europe" doesn't exist for things like mortgages.

In France, for example, the standard mortgage is fixed rate, for the whole duration of the loan, which is usually 20 to 25 years.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by room271 on Thursday April 28, 2022 @03:32AM (#31189710)
In the UK it's very common, albeit not for 30 years - more often 2, 5, or 10. See e.g.

https://www.bankofengland.co.uk/bank-overground/2020/why-are...

(In 2020, more than half of new mortgages were fixed for 5 years or more.)

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by moonchrome on Thursday April 28, 2022 @03:44AM (#31189791)
That's not fixed rates, that's just variable rate with a delay, it's impossible to get a 30 year loan with a fixed rate in Croatia.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:24AM (#31189668)
It's not in the Netherlands. Practically everyone has fixed rates here. Especially in the past few years with the low interest rates.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by smcl on Thursday April 28, 2022 @03:30AM (#31189694)
Fixed for the entire duration of the mortgage, and at the rate the commenter mentioned?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @03:35AM (#31189733)
Mine is fixed for 20 on a 30 year mortgage but you can always choose between variable, 10 year fixed, 20 year or 30 year.

Mortgages are (almost) always 30 years duration.

I don't know what country in Europe you can't get fixed rates but it's not the Netherlands, that I know for sure. (Also there really isn't a 'Europe' for these things, every country is different)

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jason-phillips on Thursday April 28, 2022 @03:55AM (#31189852)
> Mine is fixed for 20 on a 30 year mortgage

In the United States we don't call that "fixed". We call that an adjustable rate mortgage. For example, my mortgage is fixed at 3% for its entire 30 year term and can properly be called "fixed".

People in the United States are leery of ARMs after what happened during the mortgage crisis in 2006-2011 so proper labeling is more important.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by apexalpha on Thursday April 28, 2022 @04:01AM (#31189891)
Ah, right.

I could also have picked 30 years for a 'real' fixed mortgage. It just gets a bit more expensive. But it's definitely possible to get 30 year fixed if you really want to, every bank offers it.

In the Netherlands an 'adjustable rate mortgage' means monthly, quarterly or yearly variable rates.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @04:07AM (#31189929)
Adjustable rate mortgages aren't quite the same.

Canada is similar to the UK - you amortize (pay back) the loan over 25-30 years. However, your mortgage is either variable (interest rate floats over time) or fixed (interest rate does change), but the loans are only for 1 to 5 years. At the end, you either "renew" your mortgage with the same lender or you "refinance" entirely.

So you can have a "fixed" mortgage, but not for the entire amortization period. But you're correct, it's more similar to the ARM mortgages in the US (potentially fixed for 5-10 years, then floating after).

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by smcl on Thursday April 28, 2022 @04:23AM (#31190033)
Ah so what I meant is that in Czech Republic I have a 30 year mortgage with a rate that is fixed at 1.99% for 5 years, and is then variable (or more likely renegotiated) after that period. I am sure I could have instead gotten a 30 year mortgage with a single rate for the duration, but I suspect it would've been higher than the rate. But if you're at a 2% for 20 years that is pretty great IMO - given that our rates are currently through the roof.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by modo_mario on Thursday April 28, 2022 @04:09AM (#31189944)
what? I got a fixed below 1% rate in Belgium last year. With historical lows on those everyone gets a fixed rate.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jgb1984 on Thursday April 28, 2022 @04:09AM (#31189941)
Uhm my brother just signed a fixed rate of 1.8% for the entire 20 year duration of his home loan. Belgium.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by davio on Thursday April 28, 2022 @09:45AM (#31192363)
Refinance applications were down 70% compared to year ago. Combined with low home inventory, the mortgage industry looks pretty grim.

I'm expecting rates to reverse at some point. Mortgage companies will either need to compete to get some business or just give up.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by s1artibartfast on Thursday April 28, 2022 @12:27PM (#31194564)
Last years rates were a historic low, lower than the last 40 years at least. How do refinances compare to 3, 5, or 10 years ago
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by theferalrobot on Thursday April 28, 2022 @02:29AM (#31189334)
I’m seeing 5.0% most places (see ally bank). Still higher than its been but not pushing 6% by any stretch.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cammikebrown on Thursday April 28, 2022 @02:36AM (#31189374)
It's pushing 6% if you have worse credit (700-750). But don't worry about that, NINJA loans are back: https://i.redd.it/wnzuveooo5w81.jpg
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oblio on Thursday April 28, 2022 @03:52AM (#31189835)
That looks like a crash waiting to happen.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by llampx on Thursday April 28, 2022 @07:25AM (#31191202)
No Income, No Job anything?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by lotsofpulp on Thursday April 28, 2022 @09:02AM (#31191946)
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by onlyrealcuzzo on Thursday April 28, 2022 @09:46AM (#31192375)
I would hope if you have no income you don't have a job!
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by syntheticcorp on Thursday April 28, 2022 @06:08PM (#31198823)
I suppose you could have income from interest on capital or stock dividends
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cbanek on Thursday April 28, 2022 @04:12AM (#31189956)
As Tobias said in Arrested Development: "NINJA please!"
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by broken8ball on Thursday April 28, 2022 @02:33AM (#31189357)
Allegedly 6 more rate hikes from The Fed this year too, so this could just be the beginning.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by anm89 on Thursday April 28, 2022 @02:45AM (#31189432)
I personally do not believe they have a shot in hell at making it through 6.I think there is going to be some serious chaos in markets well before then. We haven't seen chaos in markets without immediate fed support for decades. It's going to get bad IMO.

It will be surprising if Powell doesn't do a second pivot and go Dovish well before 6.

Obviously I'm not a fortune teller and many people disagree.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by paxys on Thursday April 28, 2022 @02:33AM (#31189363)
And it is still relatively easy to get ~4-4.25% with a little bit of negotiating.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by crysin on Thursday April 28, 2022 @02:49AM (#31189458)
By negotiating do you mean taking points? I can’t imagine many lenders are willing to go below prime for a 30 year conforming loan.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by s1artibartfast on Thursday April 28, 2022 @12:29PM (#31194606)
I'm in escrow with less than 4% today w no points. Took some negotiating
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ab_testing on Thursday April 28, 2022 @11:06PM (#31200919)
How to negotiate rates? What do you usually tell them in the phone ?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by s1artibartfast on Friday April 29, 2022 @12:43AM (#31201541)
Shop around. Ask about relationship deals for assets under management. Ask about getting closing costs credited towards points. Tell them if you have a better offer and ask if there's any discounts the underwriter can offer
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oliwarner on Thursday April 28, 2022 @03:39AM (#31189763)
Whole-term-fixed rates are pretty uncommon in Europe. Fixes of 2, 5 sometimes 10 years are products most providers offer, but as the term increases, the rate shoots up, to offset rate uncertainty.

My question is: why would you fix for 30yr when you know you're paying multiple points to offset market uncertainty? Remortgaging every couple of years takes a bit of time, and shopping around, but is much cheaper.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by runeks on Thursday April 28, 2022 @03:49AM (#31189814)
> My question is: why would you fix for 30yr when you know you're paying multiple points to offset market uncertainty?

To fix your monthly payment for the next 30 years.

Furthermore, with a fixed rate mortgage you can benefit from interest rate volatility since you can always buy back the debt at par. In practice this means you can:

1. Take out a fixed rate loan for $n at x%

2. If the rate doubles (to 2x%) you can refinance and you now only owe half ($n/2)

3. If the rate falls to x% again you can refinance again and now you owe the original amount ($n/2) at the original rate (x%)

This ignores the cost of refinancing the loan, so you’ll be paying some fixed sum for that (which is lost), but if rates moves sufficiently this is a huge benefit that you don’t get with a variable rate mortgage loan.

* This is based on how the Danish Realkredit mortgage works. I’m not certain, but I believe fixed rate mortgages work the same way in other countries.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by shawabawa3 on Thursday April 28, 2022 @04:05AM (#31189916)
Can you explain point 2?

Why do you refinance if rates go up? Surely the point is that if rates go up you've locked in a better rate

How does half your debt disappear if rates go up?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by runeks on Thursday April 28, 2022 @05:21AM (#31190357)
Sure.

> Why do you refinance if rates go up? Surely the point is that if rates go up you've locked in a better rate

You don't have to, but you can choose to either (a) keep the same rate and owe the same amount, or (b) get the new (higher) rate and owe less.

> How does half your debt disappear if rates go up?

It doesn't exactly. However, the market value of your mortgage loan halves if the rate doubles (roughly). This means you can:

1. Take out a loan for half the original amount, at double the interest rate

2. Buy back your original loan

3. Destroy the original loan (which is fine since you are both creditor and debtor for that loan)

This leaves you with the loan taken in step 1.

To understand why it works this way it's instructive to think of a loan as an exchange of wealth for income. One party has some savings (wealth) and would like to exchange it for an income (e.g. to pay recurring expenses). Another party has an income and would like to trade it for wealth (e.g. to buy a house). Viewing a loan in this way, the interest rate is nothing more than the current price of a certain income stream (measured in percent per year).

For example, let's assume that the current market price for an income of $2 per year is $100. This is equivalent to an interest rate of 2% per year. I have $100 that I'm willing to part with for an income of $2 per year, and you have an income of at least $2 per year that you're willing to sell for $100. We make the deal. Now, the day after we shake hands to make the deal, the current market price for an income of $2 per year falls to $50. This is equivalent to a doubling of the interest rate (from 2% per year to 4% per year). I still have the income of $2 per year that I paid $100 for yesterday, but if I want to sell this to someone else I can only get $50 for it. And if you were to ask me to buy back the loan for $50 I would have nothing against that, since I could go out immediately after and buy the same $2/year income for those $50.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Khoth on Thursday April 28, 2022 @05:32AM (#31190437)
At the start of the post you were the person taking out the loan but by the time you got to the explanation at the bottom of the post you were the bank.

If you've sold your $2/year income for $100 yesterday, why on earth do you want to buy it back and resell it for $50?

e: Oh wait I see. You want to go to the bank and say "I know I owe you $100+interest over the life of the mortgage, but what if I just pay you back $50 right now and we call it even?" Does that actually work?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cascom on Thursday April 28, 2022 @05:46AM (#31190552)
Except no bank (at least in the us) will cut that deal, because they don’t mark those loans to market.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by SilasX on Thursday April 28, 2022 @08:31AM (#31191704)
Yeah, that was my reaction too. But ... why not? It still seems possible. I mean, between banks they definitely have to mark it to market in order to sell the mortgage, so they would take a big hit to sell when interest rates go up.

So, why can't you put on a funny hat and glasses, get a new mortgage at the higher rate, and then go buy your existing one at a discount?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cascom on Thursday April 28, 2022 @06:04PM (#31198772)
If you’re “trading” the mortgage, you mark to market, but if you hold it for investment then you don’t (this is driven by bank capital requirements - if I need to go raise capital every time interest rates went up that would create huge problems (despite the credit staying the same (if not improving))
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Gareth321 on Thursday April 28, 2022 @09:04AM (#31191958)
The person is describing a bond loan. They're not offered in most countries.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by ilammy on Thursday April 28, 2022 @04:54AM (#31190191)
The rates usually don't go up because the lender got greedy and felt like screwing you harder. If the mortgage rate doubles, that's because your money is now worth less than it used to be. This also likely means that your income is going to grow soon enough, so you wouldn't have much trouble repaying your loan. While your remaining loan is still nominally $N, if you took a loan today for the remaining part using the paid-off equity as collateral, you could likely get twice as much and the lender would proceed accordingly.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by matsemann on Thursday April 28, 2022 @05:33AM (#31190453)
Danish loans are a bit special, though, as in most people don't pay them down, but just use them as a way of having a fixed rent. At least that's my experience, all my danish family own their houses, but have almost done no real payments on the loans. Whenever they've paid down a bit, that is just refinanced to a new loan so they get cash, aggressively promoted by the banks. Or the equity is just based on a hope that the loan will stay the same but the value of the property increase. Which it certainly has not.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by maxerickson on Thursday April 28, 2022 @07:06AM (#31191097)
I wonder if the way I use "homeowner" differently than the phrase "own their home" is particular to me. I wouldn't say someone with a mostly unpaid mortgage "owns their home" even though they are a homeowner.

It is "their house" and things like that also, but I hesitate to directly say that they own it.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by kube-system on Thursday April 28, 2022 @12:55PM (#31194927)
In the US, liens are encumbrances to title but aren't transfers of title. It's a legally important distinction because the law often recognizes that even in a foreclosure, equity belongs to the homeowner ...among all of the other rights that come along with property ownership.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by pjc50 on Thursday April 28, 2022 @05:17AM (#31190325)
> To fix your monthly payment for the next 30 years.

Sure, but .. nothing else is fixed for those 30 years? Not your salary, the price of fuel, your place of work, life circumstances? And you're paying a premium at the start for this.

It's more apparent in the UK where you can choose how long you want the fix for and see the interest rate you're offered go up.

> you can benefit from interest rate volatility since you can always buy back the debt at par.

Obviously the bank knows this and charges you a small premium over the spot rate so they don't lose money.

> If the rate doubles (to 2x%) you can refinance and you now only owe half ($n/2)

I don't understand this: the amount outstanding - the redemption value - of a fixed rate mortgage is known in advance at every month throughout its term, regardless of what the market interest rate is?

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by sokoloff on Thursday April 28, 2022 @09:17AM (#31192085)
The differences are apparent in the US as well. The bank is making offers to a broad population without knowing their life plans. The borrower has a better idea of their individual life plans. I was buying my “lifetime home” 15 years ago and so took a fixed rate. When I first refinanced, I still had the same plans. When I second refinanced, I still had the same plans.

Even among fixed rate products, there’s an option to buy down the fixed rate. Those usually have a point in the future where all choices are about the same, shorter favoring not paying points and long favoring buying discount points (this crossover point varies over time by current and expected rates, but is in the 4-8 year range typically).

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by simulate-me on Thursday April 28, 2022 @08:56AM (#31191879)
In the US, you can refinance your loans. Essentially taking out a new loan to pay off your old mortgage. The new loan has the new market interest rate. In the US, you’re typically allowed to pay off additional principal without any penalty, so you can end a loan by paying off the outstanding principal without needing the pay the remainder of the interest on the loan.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nsteel on Thursday April 28, 2022 @09:14AM (#31192049)
As I understand it, it's this refinancing that leads US citizens in the UK ending up with a surprising US capital gains bill after they re-mortgage their UK property. And we also (normally) have ERCs in the UK so as usual, the rest is the worst of both worlds.

Ideally one could renounce the citizenship, oh wait...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by simulate-me on Thursday April 28, 2022 @09:26AM (#31192164)
The IRS does not consider a refinance (even a cash-out refinance) to be a capital gain. The IRS also allows for 250K (500K if married) of tax-free capital gains on the sale of a primary residence. Maybe you misunderstood your friends’ situations.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by tristor on Thursday April 28, 2022 @10:20AM (#31192787)
This is only true for a primary residence located in the US. If it’s a foreign asset, it’s taxed normally. The IRS deeply screws expats.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by simulate-me on Thursday April 28, 2022 @11:02AM (#31193319)
I just looked this up and you're right. If you're subject to the expatriate tax then you're automatically disqualified from the exemption. From my reading, it seems like there is a small loophole. You can sell a foreign property if you move back to the U.S. and meet all the other primary residence conditions.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by nsteel on Thursday April 28, 2022 @11:25AM (#31193661)
Exactly. And what's even more brilliant is that it entirely depends on the exchange rates at the start and end of the period. So a zero gain (or even a loss) over that period in the UK can still result in US tax owed.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Gareth321 on Thursday April 28, 2022 @09:07AM (#31191984)
> If the rate doubles (to 2x%) you can refinance and you now only owe half ($n/2)

FYI you're describing a bond loan. Most countries, including America, don't really offer these, so most people won't understand what you're talking about.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by spand on Thursday April 28, 2022 @10:41AM (#31193042)
Your math is wildly off in point 2. Rates are now above 3% and ie. a 0.5% bond is trading at 77 [1]

[1] http://www.nasdaqomxnordic.com/bonds/denmark/microsite?Instr...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @04:11AM (#31189951)
The 30-year fixed mortgage (the entire amortization period is at one fixed interest rate) is a government created product. It would never be offered by banks, at the low rates they are, if they had to hold them on their books. The "normal" mortgages in the US prior to the FHA were 50% down and 5-year terms.

https://bebusinessed.com/history/history-of-mortgages/

Fannie and Freddie basically agree to "back" those new mortgages (typically buying them from banks and selling them off later) as long as they conform to certain requirements - 15 or 30 year terms, 10-20% down payments, etc.

It's a massive subsidy for the housing market in the US, but also addresses the social goal of making housing accessible. You can get a mortgage and the monthly payment (interest + principle) never changes over the 30 year life of the loan.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oliwarner on Thursday April 28, 2022 @11:02AM (#31193313)
> at the low rates they are

Low rates?! BOA is offering me 4.9% on 400k/800k, fixed for 30yr. But they still want 4% for a 5year ARM. Even after income tax deductions, how the hell do Americans afford houses with this sort of nonsense.

I guess that's what TFA is really driving at. It's getting hard to lend money on housing in the US.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bluedino on Thursday April 28, 2022 @09:10AM (#31192023)
Back then you could order a house from the Sears catalog for $1,495
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by cascom on Thursday April 28, 2022 @06:25AM (#31190824)
“Remortgaging every couple of years takes a bit of time, and shopping around, but is much cheaper”

This is an incorrect statement. It is true only if short term interest rates (on average) remain flat or decrease over the next 30 years.

Put another way, by getting a fixed rate loan you are paying for insurance against rising interest rates (+inflation), you’re saying it’s ALWAYS cheaper not to buy insurance - but the honest answer thsts probably been true recently, but not always historically, and may not be true in the future.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oliwarner on Friday April 29, 2022 @01:31PM (#31208226)
Well this way of doing things has been a vastly cheaper way of borrowing in the last 50 years, in the UK.

If the interest rates tip up for an extended duration, yes, it's possible that longer term fixed rates could be cheaper, but of course the banks insulate themselves against that possibility with even higher rates if they suspect it's likely.

It's possible they won't insulate enough. IME, betting against banks looking out for #1 is foolish.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by justincormack on Thursday April 28, 2022 @03:52AM (#31189832)
If you can afford it then you are likely to continue vs in Europe when rates go up people default. So it should improve default rates. In the US you can refinance when rates go down for free while European fixed rated have early repayment penalties usually. So its a free option. So it has a number of advantages even if rates can be high if long term rates are high.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by wil421 on Thursday April 28, 2022 @09:33AM (#31192230)
So I don’t get screwed when the rates go up. My current rate is 2.75% if I had to renew this year it could almost double. That could easily be $400-500+ a month. When the rates are low nothing can stop me from refinancing like I did a year+ ago from nearly 4%.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by modo_mario on Thursday April 28, 2022 @04:16AM (#31189985)
>Whole-term-fixed rates are pretty uncommon in Europe.

Here in Belgium I think most people got those.

>why would you fix for 30yr when you know you're paying multiple points to offset market uncertainty?

Because my rate was 0,98% fixed for 20 years here in Belgium. I'd have done the same if I needed 30 (which is rare here as 20 or 25 is more common) The chances of coming out ahead long term starting out with a higher variable rate are rather slim

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by s1artibartfast on Thursday April 28, 2022 @12:32PM (#31194659)
>why would you fix for 30yr when you know you're paying multiple points to offset market uncertainty

Because you are leveraged to the gills and a rate hike could lose you your entire principal.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jjav on Thursday April 28, 2022 @12:25PM (#31194538)
> why would you fix for 30yr when you know you're paying multiple points to offset market uncertainty?

At least in the US it is always better to get a fixed rate loan (meaning fixed for the life of the loan, typically 30 years).

This means your mortgage payment can never go up no matter how high rates climb in the market.

But if rates go down, you can always refinance to a lower rate and ratchet your payments down and lock them there.

It's as close to a free lunch as thing come. Your housing payment can never go up but can only go down.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mrep on Friday April 29, 2022 @10:36AM (#31205710)
> At least in the US it is always better to get a fixed rate loan (meaning fixed for the life of the loan, typically 30 years).

I don't know about that. I recently got a 10/1 ARM at 3.75% for my second home and it was a full 1.125% below a 30 fixed due to FHFA changes [0].

[0]: https://www.ezhomesearch.com/blog/second-home-mortgage-rates....

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by syntheticcorp on Thursday April 28, 2022 @06:11PM (#31198850)
I can’t believe you can get 30 year fixed in the US , that’s amazing. The longest terms I can see where I live are 5 year fixed.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by PinguTS on Thursday April 28, 2022 @04:23AM (#31190034)
What is your reference of Europe?

In Germany, 15 years, 20 years, and up to 30 years is common. I took 20 years.

A close friend of mine working at a bank has an internal benefit, that the 10 year fixed rate applies for her as a fixed rate for however it takes to pay-off.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by egeozcan on Thursday April 28, 2022 @04:35AM (#31190100)
I'm also in Germany, which bank is that? I didn't find any fixed-rate offer for a 450K flat.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by PinguTS on Thursday April 28, 2022 @07:43AM (#31191353)
I was in negotiations with HVB and Commerzbank. I choose Commerzbank, which had a slightly higher interest rate but way much better communication with me. I was communicating with the guy in charge of the wealth management, this may also helped a lot. ;)

Loans lower 400k are easier to issue, I learned in the process. Because >400k has much more requirements for the bank on collateral required by the regulation authorities.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by the_mitsuhiko on Thursday April 28, 2022 @05:35AM (#31190467)
I'm not in Germany but an acquaintance has a 20 year fixed rate mortgage in Germany from one of the Sparkassen (Flat in Berlin).
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by oblio on Thursday April 28, 2022 @03:49AM (#31189818)
They're not uncommon, Europe is a big place.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by xphilter on Thursday April 28, 2022 @03:38PM (#31197231)
Sure, but there’s still no supply of homes. There are presently 2 houses for sale in my neighborhood of about ~750 homes. I don’t have historical data, but 0.002% seems very low for spring.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by elevaet on Thursday April 28, 2022 @02:45AM (#31189430)
In Canada rates are creeping up from really low, often under 2% still.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @02:54AM (#31189497)
And a median sale price that has hit ~$800,000, which is double the US.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by elevaet on Thursday April 28, 2022 @05:34AM (#31190460)
It's nuts. Canada has a lot of good things going for it, but housing affordability is at a crisis point.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @07:47AM (#31191373)
It is. You can just look at the US and Canada over the same time period to see how out of wack Canada is.

Canada is basically the US minus the 2008 crash. It's just price inflations non-stop for 20 plus years.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by onlyrealcuzzo on Thursday April 28, 2022 @09:53AM (#31192460)
Isn't it 40 years??

My understanding is prices crashed hard in the 70s, there was a slight decline in 1990 and 2008, and other than that they've been going up 5-10% per year.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by refurb on Thursday April 28, 2022 @10:42PM (#31200792)
The last big crash was 1990 in Toronto. Price dropped and didn't recover until the early 2000's.

https://urbaneer.com/blog/when-dreams-of-domesticity-became-...

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jbay808 on Thursday April 28, 2022 @02:53AM (#31189490)
That's probably because Canadian mortgages are essentially all adjustable rate.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by mensetmanusman on Thursday April 28, 2022 @07:15AM (#31191143)
This is also what the pushback against asset price inflation looks like.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by taf2 on Thursday April 28, 2022 @06:49AM (#31190975)
It seems like interest rates need to get to maybe 9% to bring down inflation… see: https://www.federalreservehistory.org/essays/recession-of-19...
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by gowld on Thursday April 28, 2022 @01:27PM (#31195388)
Which bubble?

A refi bubble? Maybe (but that's more of a fad than a bubble)

Real estate bubble? Sort of.

Housing affordability bubble? Not really. Interest rates move profits from home sellers to banks.

Housing affordability is driven by supply+demand. Housing prices are driven by" Affordability minus Interest Rates: Low Rates + High Price = Monthly Payment = High Rates + Lower Price

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by alexb_ on Thursday April 28, 2022 @02:26AM (#31189323)
"Cracking down on Airbnb"... you say this as if Airbnb is a horrible thing or something LOL
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by woodruffw on Thursday April 28, 2022 @02:30AM (#31189340)
I don’t know about other places, but Airbnb has been a mixed bag for NYC: I’ve seen it used to keep housing stock off the market, to dodge the obligations associated with keeping a property livable, and to essentially run entire illegal hotel businesses without attracting regulatory (including safety) scrutiny.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by bobthepanda on Thursday April 28, 2022 @02:57AM (#31189513)
Also, tourists are the absolute worst to have as neighbors.

Warnings for noise complaints and rubbish don't really work if the person is just going to be gone by the time a third strike happens.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by raverbashing on Thursday April 28, 2022 @03:19AM (#31189626)
AirBnb in NYC is also a fertile ground for scams
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by crate_barre on Thursday April 28, 2022 @03:24AM (#31189667)
Explain. I thought finding a high rated host is enough?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by raverbashing on Thursday April 28, 2022 @04:31AM (#31190086)
https://www.vox.com/2019/11/14/20961972/airbnb-scam-how-to-s...

Or just google it, there are plenty of examples

[dead]
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Balero on Thursday April 28, 2022 @06:37AM (#31190904)
So it's ok if someone moves next to you, plays music all hours, leaves rubbish everywhere, and are generally annoying to live next to. And then the next week a whole new group of people move in forgetting any requests you made, but act the same way because they are specifically there for a fun weekend.

Also this stops you getting to know your neighbors and form a community and friends that live around you. Any improvements you make to the local area and street have the owner uninterested or pushing back because they do not want to invest in the area.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by raesene9 on Thursday April 28, 2022 @04:04AM (#31189911)
AirBnB (and similar) has been really bad for the property market in the Scottish Highlands. Lots of people buying up scarce housing stock to use for holiday lets, means that locals who work in the area (where a lot of local employers can't pay stellar rates) can't afford to buy.

Combine that with the fact that these areas are often in National Parks which have restrictions on new-builds and you'll inevitably reduce the amount of people actually living in the area.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by Raed667 on Thursday April 28, 2022 @02:28AM (#31189333)
Airbnb is a horrible thing if you (like me) live in a tourist city and making rent inaccessible to the local residents
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by dominotw on Thursday April 28, 2022 @12:21PM (#31194469)
why do you live there though. Can't you ask your employer to match the deficit.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throw8383833jj on Thursday April 28, 2022 @12:56PM (#31194938)
employers could not care less about your housing problems because employers have greater bargaining power than workers. places like CA think they can control where people live by depriving people of housing but it's not true. people just become ever more desperate, paying more and more for shelter. It's employers who decide where people are. this is because we've created a world where people can't live without money. so he who controls wages, controls where people live.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jimbob45 on Thursday April 28, 2022 @04:08AM (#31189934)
Think about a hypothetical city where 100% of the properties are AirBNBs. There will be no source of employees for any local businesses because there are no long-term residents. There is no vested interest to improve the city via taxes and volunteerism, because no one truly lives there. No one will move to that city because the property rates are so absurdly inflated thanks to AirBNB rates.

It’s an absurd example but cities frequently see these effects when they let AirBNB and rental properties run wild.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by itsmejerry on Thursday April 28, 2022 @01:36PM (#31195529)
Other than perhaps zoning restrictions, how does this differ from traditional hotels/motels in extreme tourist areas, like Niagara Falls. If people don't want to live permanently in a city for whatever reason, of course the city will suffer.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by jimbob45 on Thursday April 28, 2022 @01:47PM (#31195699)
Hotels/motels are dense enough that they don't take usable land away from residential housing while still allowing for short-term residents to enjoy the city.

However, AirBNBs and rental houses suck away the usable land such that you begin to meaningfully remove potential long-term residents from the city. The flipside of this, of course, would be apartments/duplexes, which would add more long-term residents than single-family zoning would allow, even with the problem of AirBNB proliferation.

Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by dominotw on Thursday April 28, 2022 @12:21PM (#31194479)
this is basically all mountain towns now.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by throwaway578309 on Thursday April 28, 2022 @02:31AM (#31189346)
It is if you live next to a landlord that houses loud guests. Is this even a question?
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by broken8ball on Thursday April 28, 2022 @02:30AM (#31189338)
It’s my understanding that Airbnb is pretty bad when it comes to gentrification and driving city natives out of affordable housing.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by globalise83 on Thursday April 28, 2022 @03:29PM (#31197120)
Mixed bag if you live next door to one. We had one guy wake us up early in the morning on a Sunday because he locked himself out. Another time we were gifted half a cooked spiced lamb from a Saudi Arabian family.
Re:Rocket Mortgage to trim 8% of workforce as home-loan mark... by justsomeguy123 on Thursday April 28, 2022 @02:37AM (#31189378)
AirBNB, like Uber, lives on sucking externalities. They are the modern Oil that sometimes spill and kill some ecosystem, but because the ecosystem is far away nobody cares.

Like a pimp, AirBNB is the helpfull middleman for the desperate or the sociopaths.

So, yes, at it's core AirBNB is horrible.