Adjusting for inflation using shadow stats, you'd still have lost money.
With the Florida land bubble - you're also forgetting property taxes.
That's because shadow stats is a joke. If you adjust US GDP using their inflation figures, you'd find that the US economy has been on a continual decline for the past few decades.
Today families need dual incomes just to purchase a modest home and carry health insurance. How is this not a decline in standard of living from a few decades ago?
Where's our new airports? New rail transit systems? New infrastructure? Everything in this country is old and getting older.
What's your point.
> sweeping linear statements like "decline"
Who are you talking to? When did I make any statements of that nature?
I was pointing out the provided example was stupid. Smart phones are "cool" and all, but it'd be a tough sell to argue successfully that connectivity has increased societal cohesion, education, information dispersal, or any of the other virtues you might hope for.
Instead, iPhones and virtual doctor appointments are like bandaids on a societal-wide decline, where increased privatization combines with government inflation to create a caste system they disguise as capitalism. Inflation-adjusted salaries are lower than ever across the board, housing prices are skyrocketing both absolutely and as a function of salary-years, corporate control of information has reached unprecedented levels, and the "relative value story" of now vs 40 years ago makes it pretty clear it's tougher to have a good life now even if you can have fancy toys to interact with corporate-controlled data-mined ad-laced entertainment
The naivety is almost making me feel better, but I don't think you understand what capitalism has done to our world's power structures if you think we stand a chance to change anything
Now, my plan is to accept that even with a good salary securing a future at good QOL costs a lifetime, so I will try to enjoy myself and hopefully buy a home that doesn't get burnt down in the increasingly frequent and devastating forest fires of my native home.
Hooray for 2022!
That claim sounds reasonable given what I've observed happening in this country over the last few decades. Without question people seem to struggle much more to obtain the same level of lifestyle as many enjoyed decades ago.
You seem to claim that this is such an obvious falsehood that there's no more room for discussion, but I think there's much more room for discussion that you are implying.
https://www.census.gov/data/tables/time-series/demo/income-p...
It's primarily the labor-heavy working-class white male (in the white male demographic) that has been brutalized by changes in the US and global economy. They have been left behind to drown in a pool of fentanyl.
> It's primarily the labor-heavy working-class white male (in the white male demographic) that has been brutalized by changes in the US and global economy. They have been left behind to drown in a pool of fentanyl.
That sounds like most people are actually more negatively affected by the economy compared to decades prior.
Let me say very clearly: It's far too many people. I don't care if it's less than a majority, and I don't care if it swings the overall statistics. It's still too many people that are being economically destroyed.
Outside of housing everything is dirt cheap nowadays.
> Based on my conversations with Williams, I think I now understand what he’s doing: he’s misinterpreting a cumulative 20-year change in the measured price level as a change in the measured annual inflation rate. And that caused him to overestimate that annual change by at least an order of magnitude.
It did? According to https://fred.stlouisfed.org/series/USMANNQGSP, it's been steadily going up. The only thing that's shrinking is its proportion of GDP. https://fred.stlouisfed.org/series/VAPGDPMA
> and almost no one can afford housing until they're middle aged
...except that shadowstat's inflation figures outstrips even housing prices[1]. Eyeballing their chart, we've been experiencing 9% growth between 2000 and 2020, translating to a 460% increase. By comparison the housing price index has only gone up 184%
that sounds quite reasonable to me, considering the vast decrease in material living standard in the US for the last several decades. there was an interview with someone who lived through the 70s that was saying a painter back then could afford to buy his own home, have a wife that didn't work and six kids! today, a single painter can barely afford to rent a single bedroom, let alone support a whole family and have a house.
I don't know when this practice died out, but it used to be routine for homeowners to take in boarders.
People could generally meet their basic needs because those were the only things they spent money on. Life was exceedingly bare-bones. Houses were small. Your life revolved around your job. You cooked all your own meals. You entertained yourself. The list goes on.
All of that said, house prices are alone just bad example. If you went somewhere with cheap land and no red tape, you could get a 70's house at 70's prices (adjusted for inflation) still.
One thing is that mom cooked all the meals. People rarely ate out. I know that was true in my family at the time. Eating out was a major, major treat. Entertainment was going out the door and joining up with the neighborhood kids. The house was tiny.
It all was perfectly normal.
Food has also gotten much cheaper relative to what it was in the 1970’s. Some would argue that it has also reduced in quality.
But if you add up all the plusses and minuses the two income family today has less disposable income then the single income family in the 1970’s when you exclude the cost of transportation, healthcare, childcare and housing.
It turns out one of the biggest drivers of home prices is school quality and income potential. So two cars for two jobs in a place you can find them and housing and childcare to ensure that children are safe.
The starter homes of the US Boomer generation are out of reach of the Millennials even though they are the same houses but now 50 years old.
Most of the houses have had additions built in by now, and extensive revisions and upgrades.
There are plenty of homes in the US that can be afforded on a single salary of a blue collar laborer.
Are these in the highly desirable coastal cities? Of course not.
People used to move to LA post-WW2 because it had cheap and plentiful land. It no longer does.
It is possible that you're just so rich their income wouldn't contribute to the family, but income is always useful - otherwise neither of you would be working.
[1] http://www.shadowstats.com/imgs/sgs-cpi.gif?hl=ad&t=16497710...

GDP since 2000 went from 10.5T to 24T (2.285x). Adjusted for 3% inflation, that's a 26% increase.
Your point remains.
4% inflation would mean a 4% increase over 20 years.
5% inflation would mean a 14% DECREASE over 20 years.
6% inflation would mean a 29% DECREASE over 20 years.
7% inflation would mean a 41% DECREASE over 20 years.
8% inflation would mean a 51% DECREASE over 20 years.
The problem is - the way people experience inflation is dramatically impacted by whether they had a 30-year fixed mortgage.
If your house PRICE went up 400% since 2000 and your housing cost went DOWN 20% since 2000 - inflation would obviously seem low.
If your rent went up 400% since 2000, it obviously feels different.
67% of people are homeowners - and the Fed's measure of inflation seems largely targeted to this group of people. The true rate of inflation is almost certainly higher - but probably nowhere close to ShadowStats.
1. using country level GDP gets you a 63% drop, hardly any better
2. The argument I was making was with respect to living standards (ie. there's no way that our income/living standards dropped 67% in 20 years). In that context it makes sense to use GDP per capita rather than GDP for the entire country. If US population grew 50% over some time period, and GDP only grew 25%, that's actually bad because that means the average person is actually worse off than before.
Theoretically, everything can be expressed in dollars - and GDP often is - but I think you're oversimplifying things.
It's not, but the GDP figures I was looking up was in USD, so it should be factored in.
>but I think you're oversimplifying things.
Perhaps, but can you think of a plausible model for why our GDP would have dropped 67% in real terms, but somehow our living standards haven't dipped to that of a developing south american/african country? The only explanations I can come up with are:
1. the real GDP drop doesn't exist, or at least is vastly overstated
2. every other country (or at least the worldwide average) GDP dropped by approximately the same amount, so comparatively speaking we're still in the same place relative to other countries
That could explain a large portion of the gap...
Doesn't look like it's in decline here: https://fred.stlouisfed.org/series/GDPC1
Or here: https://tradingeconomics.com/united-states/gdp-constant-pric...
For others: http://www.shadowstats.com/alternate_data/inflation-charts
Major red flag -- shadow stats is a hyperinflation fantasy. Of course it looks like you'd lose money if you think inflation is orders of magnitude higher than it actually was.
I remember vaguely a chart of total inflation-adjusted return, including dividends. Forgetting dividends leads some people to be much more pessimistic than they should.
If I can find the dang chart I'll post it.
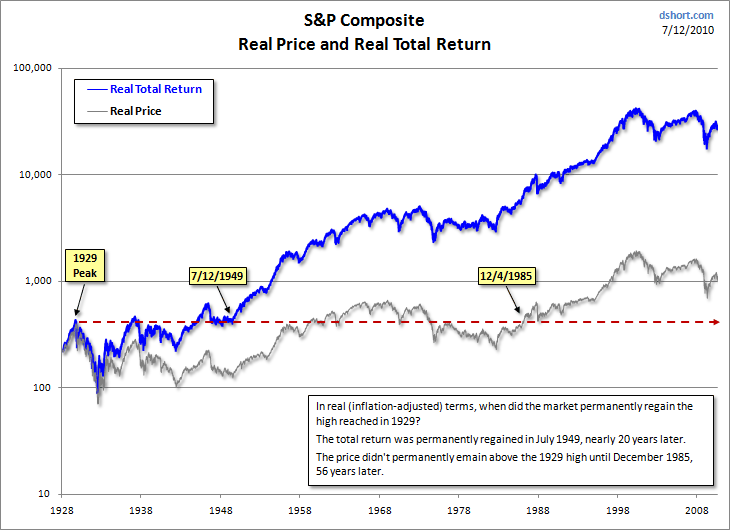
and turn on or off "Reinvest Dividends" to compare
https://www.nytimes.com/2009/04/26/your-money/stocks-and-bon...
The evidence for shadow stats should be going up every year but we haven't seen that at all.
I know there are limits, like in 1920 I couldn't buy a 1gbps internet connection or a Moderna vaccine. But despite inflation's flaws, it is useful as part of a discount rate for measuring returns.
In 1929 pig iron was 18.43$ per ton, it was $640-650 per tonne on March 7. Inflation calculator suggests it should be ~309$/ton which is fairly close across 92years but low. It also spiked to 1000+$/ton a few months later. https://www.usinflationcalculator.com/
Gasoline on the other hand was 0.21$/ gallon in 1929 plug into the inflation calculator and you get $3.53 much closer.
Chicken was 42¢/lb in 1929 New York same inflation number gives $7.06/pound today which is high.
What really messes things up is when goods stop representing the same thing across time. A new house in 1929 house was likely though not guaranteed to have indoor plumbing but AC was rare even though both where available back then. Of course 1929 AC was often focused on humility control not just temperature so again not apples to apples but in the other direction. Look for a comparable home base on floor space, number of bathrooms etc and housing prices are rising much slower than many charts suggest.
We all know that efficiencies have driven down the cost of many manufactured goods (like TVs) and scalable services (like ATMs and online banking)
We also all know that cost disease has driven up non-scalable services (healthcare, higher Ed, govt) and supply-constrained good/assets (price of land)
The basket is still useful for understanding whether an investment clears your hurdle :)
Crypto, NFT .. who knows, only time will tell who was right.
The tulip bubble ended because the bubonic plague killed all the speculators and didn't even affect the spot market of tulips, so we don't even know what would happen. Worst bubble example.
There were several great, rational, trades with beanie babies as well that has nothing to do with the latecomers that hoarded them and acted surprised and delusional when they were holding the bag.
Out of all the famous bubbles, I think equities bubbles are more useful examples of irrecoverable irrational exuberance than any commodities/product bubble.
If porn is the bellwether, then use cases have arrived.
The CC companies withdrew from PornHub because their business model was paying for the production of child pornography.
Crypto pops up its ugly head yet again. Not a coincidence given the other "killer apps" are extortion, money laundering and greater fool farming.
Sure, the people that are able to cling on and wait it out for 2 decades might say 'this wasn't so bad after all!' but the people who lost their jobs or lost their families, went into bankruptcy, etc...well...you won't hear from those very often and if you do, you'll probably just say 'better luck next time'.
This also assumes you put no new money in the market and ignoring dividends. Buying the dip in the 30s, 40s would have cut this time to breakeven significantly. Also, we're talking a once in a 100+ year event. We may never see a repeat of a similar sized crash again in our lifetimes.
The 2008 financial crisis was also a once in a 100+ year event.
So was the 2020 Covid-19 pandemic.
And the 2022 Russo - Ukrainian war.
And now I wonder what "once in 100+ year event" we'll have next year.
That is absolutely not a once per century event. WWII was 80 years ago.
- Mort, by Terry Pratchett
Which actually plays out often, birthday-paradox style.
2008 was closest to 1929.
The market only "recovered" because the government intervened and infinite money got printed and poured onto it. Otherwise it would have crashed.
The greatest wealth transfer in history is not "the free market recovered" but a rigged game.
What actually happened is Gates and Bezos lost half their wealth, but everyone's still complaining! Just get all the other rich guys to get divorced.
If you picked ten stocks in 1928, many of them were bankrupt or near zero in five years. Same for dot-com stocks in 1999.
So now you have maybe 10% left of your original capital. You could go conservative, invest it in the index and wait. Assuming a 8% annual gain it’s going to take you 30 years to make back the money you lost (not accounting for inflation). Or you could continue picking stocks and maybe increase the risk level to make the 10x gain you need to get even.
The average bubble investor probably isn’t successful even over a period of decades.
The only essential axiom you need for this to be true is infinite growth on a finite planet.
Unfortunately it looks, from multiple perspectives, like we are hitting the limits of growth.
There's a reasonable argument to be made that the true bubble we're in is an "industrial civilization bubble". All of that growth you're seeing can be boiled down to expending vast amounts of non-renewable energy. As we approach the environmental limits of that behavior, the trend you've observed over the past 250 years might not hold true.
But while your point stands, there are some wrinkles when we're considering things on a human scale. We probably can have (for human purposes) infinite growth in PDF's, MP3s, apps and browser games... we just won't want to pay for them with the same currency that pays for scarce resources. And while exponential growth is impossible, there is more solar radiation hitting the planet every year and will be for a time span close enough to infinity for planning purposes. So steady growth might be possible indefinitely (again, for human purposes).
Going back to the moon, going to mars, making cities more livable, building Cathedrals, healing cultural trauma, making healthy families, creating better ways of life, enhancing health and lifespan, teaching and learning how the world works, figuring out consciousness, determining the secret to a good life, eliminating pain and creating ideal adventures… that is all possible with enough dedication on a long enough timescale and with enough forward thinking and endurance/adjustment.
I get that ending deprivation in the now is important, but I can’t help but feeling we’ve been sacrificing the future to a decades long hedonic treadmill to satisfy base and immediate needs rather than future oriented striving.
And if someone tries to propose something longer term, it'll get shot down by someone who says "how about not and we spend the money on partying instead" or the equivalent.
More and more I feel that we have to "sneak" long-term projects past people without them noticing.
and the CPI figures underestimate inflation by at least 2-3% with all their hedonistic adjustments. it used to be that economists would get a basket of goods to measure inflation. there's hardly any need for that anymore. Now that housing makes up 60%+ of everyone's (at least the latest generation of house buyers/renters) expenses, you just use housing as a proxy for inflation.
Is that actually true for the median US resident? I have a really hard time believing it. I can believe it's the case in SF and some other big cities maybe.
I think a better measure might be # of hours worked to afford 1 sq ft. (1970 vs 2022)
The stock market is one thing, but anyone with a mortgage is leveraged to the tits, which is why real estate is so cyclical and the downturns can be so devastating.
https://en.wikipedia.org/wiki/Florida_land_boom_of_the_1920s
But after 1935, Florida took off and grew like crazy. Even if you bought at the peak of the bubble, by the 1940s you had still gained some value.
The USA stock market went through one of histories greatest bubbles from 1927 to 1929. Afterwards, it took the stock market 24 years to recover. But by the mid 1950s, the stock market was rising to new heights.
The DotCom boom was clearly a bubble in 1999, but eventually many of the ideas became far more valuable than the heights of 2000.
If the bubbles form because investors are looking too far forward into the future, eventually the future does arrive, and then you see a period of sustained growth. That is exactly what happened in Florida, with the bubble in the 1920s, and sustained growth beginning 15 years later, at the end of the 1930s, and lasting for several decades.
My point is, if you wait long enough, the economy will often grow beyond even stupidly famous disasters. To be sure, you can probably find better investments. Buying into the stock market in 1929 and then waiting 24 years to get back to that level is not great for growing your wealth. But given time, many assets do grow beyond even the bubbles.