http://www.concretethinker.com/solutions/Disaster-Resistance...
Some friends of mine built a house this way in Montana, and the firefighters told them that if all Montanans built their wilderness homes that way, their job would be a lot easier.
You can find a lot of information on this by googling for "fire resistant home".
Quick and dirty approach is to use a controlled burn to clear brush near property and then just use a sprinkler system.
Granted these are far from 100% effective, but even a 50/50 shot at saving a property is worth a fair amount of effort.
Societies subsidize people who live in flood plains because of agriculture, infrastructure and logistics. Essentially, we get far more OUT of people living in MOST flood plains than we put in with respect to subsidies.
Consider MOST of the coastal cities. We, obviously, get WAY more OUT of Houston, Galveston and New Orleans, for example, than we put in. Those three ports are enormously important to us. If they disappeared tomorrow, you would discover why they were important the hard way.
Similarly for people living in midwestern flood plains. We will typically get far more out of them than we put in. Try feeding the world, with currently known agricultural technology, while not using any land in flood plains and you'll see what I mean. Even if you could somehow manage to do it... and I don't think you could.... but even if you could, you would cause enormous damage to the ecological tapestry of the continent. You would have to move MATERIAL amounts of water and soil at a minimum. It's best to subsidize the farmers to do what they do and make sure they're not disturbed in their endeavors. And, yes, many of those farmers and agribusinesses will be in flood plains.
Now I'm not saying ALL flood plains in the midwest or on the coast are critical infrastructure. New York, Houston and New Orleans are far more critical to our survival than... say... Miami, Myrtle Beach or Malibu. So obviously, I'm not saying that ALL port cities or ALL midwestern flood plains are critical. But there are definitely some places in this nation that merit sizable subsidies to keep people living and working there. It's the nature of the beast when you're talking about engineering an empire.
The efficient thing to do is end the subsidy, and have all the less valuable activities whose benefits don't exceed the costs relocate or cease.
The market doesn't always know what is right. To be more specific: the market is short-sighted and greedy, and can self-destruct an economy if left unregulated. We need to subsidize activities that have large costs in the short term, but return more over the long run to society. Or else they won't happen.
State funded 'generic' scholarships simply rise the cost of tuition. Good state schools are a much better use of funds as they drive down for profit education costs to be cost competitive. Schools can easily offer scholarships at minimal costs as a form of price discrimination, but public scholarships tend to simply result in administrative bloat.
Should we discontinue subsidies for solar energy companies?
Yes, instead we should tax CO2 production instead of subsidizing two industry's. see: https://en.wikipedia.org/wiki/Externality
How about the billions in R&D tax subsidies that we give to pharmaceutical/industrial/healthcare companies each year to develop new drugs, treatments, and machinery?
These should also be stopped, it's fine to fund public R&D but private R&D has terrible ROI. Drug companies spend more on advertising than R&D and really don't need help. For a solid example, the US could have a 10 year strategic food reserve for 1/10th the cost of current agro subsidies that directly result in massive health issues.
PS I agree that markets are often inefficient, but subsidies then to be horrible ways to correct them. Taxes tend to be much more efficient.
I won't address your specific points as everyone has different opinions on policy, but no one has the data to rigorously defend their opinions.
I simply want to refute the notion that we can allow free markets to allocate all resources within the economy.
Taxes are much more scalable than subsidies. AKA if A is better for society than B but B is cheaper to produce then taxing B can balance things fairly easily with consumers paying society for the external costs. But, subsidizing A is an unbound cost, adds administrative overhead, and promotes consumption of A and or B.
The downsides of Taxes is there often regressive, but for something like alcohol, pollution, or speeding societal costs are often independent from a persons net worth.
Sure, let me count them... OMG "It's Over 9000!!!"
PS: Ask a dumb question... http://dragonball.wikia.com/wiki/It's_Over_9000!
If you want more R&D, you should subsidize R&D.
If you want more people living in burn zones, you should subsidize living in burn zones.
I think I join most Americans in saying that I'd rather more people be educated, I'd rather have more R&D, and I wouldn't rather more people live in burn zones.
I'm sure other people have thought this through much better than what I just said. But it seems to me to be a reasonable argument.
If your goal is people living in flood zones, you should subsidize living in flood zones (e.g. by insuring it, which we also do).
We need an answer to the latter question in this case, not the former. And one is readily at hand: the political interest of those who live in flood zones. Maybe there's some other justification, but I'll confess I'm skeptical that this outcome is globally utility maximizing relative to alternative policies.
http://realestate.heraldtribune.com/2014/02/15/bubil-facing-...
What stood out, literally, was one farm house high and dry that had been built on a bulldozed mound.
There are ways to mitigate the risks of living in a flood plain while still reaping the benefits.
That's a weird definition for "natural" you're using. I think you mean something more like "typical". Unless you're making a theological point, an "act of God" is quite literally as natural (in the sense of un-artificial) as you can get.
But the grandparent's point was economic. Disaster insurance can't work: the whole idea behind insurance is that "bad stuff" happens rarely to some people, so everyone pools money together to pay for the few who actually needed. Disasters happen broadly, and to everyone who needs it in the affected area. A "correct" insurance scheme there would be tantamount to everyone having to just save money on their own, there's no efficiency. And of course in practice the insurance companies cheat and don't save enough, so people don't actually get paid.
As a society, we cannot ignore the cost of the "Act of God" level disasters when summing up the cost of said disaster. If an insurance companies might be able to avoid paying out on a claim doesn't mean property (or lives) did not get lost.
In my mind the issue is pretty simple: if you buy a house in a wild-fire prone area, you should expect a wildfire at some point. Whether or not you want to prepare by a) purchasing insurance or b) wild-fire proofing your house is your prerogative. If you're not willing to take/mitigate the risk, then live somewhere else.
Or changing conditions throw off their actuarial tables, making the company insolvent when reality intercedes. Those changes could be as obvious (at this stage) as climate change, or as subtle as a long-standing practice of preventing forest fires, which while seemingly preventing property loss to fire is actually creating an unstable system which has the capability for much larger destruction than the typical fire.
Life insurance spreads out risk over a large span of time for the same person. Life insurers have to be more careful. They have to invest the premiums wisely, so that they will have exactly enough cash on hand to pay out the amount of the policy on the expected date it comes due (along with some profit). If the person dies earlier than expected, they could lose money. If the person dies later, they could get more profit. Furthermore, if the investment market is unexpectedly good or bad, that affects the insurer's ability to pay the benefit. Life insurers can rely on the fact that while all people eventually die, they don't all croak at once. There's actually a predictable rate, so if you get enough people to buy policies, you're never paying out more than you take in.
Disaster insurance is more like life insurance, but even harder to pull off, because all those benefits are probably going to be paid at exactly the same time. So what insurers have to do is take that gigantic, elephant-choking payout and let each underwriter take a little bite of it, until it's all accounted for. They're spreading the risk over multiple people, long periods of time, and multiple investors. And even so, thanks to the fact that it is essentially an enforced savings scheme, a big enough disaster would be a shock to the financial markets.
But there's no way around that. If a storm destroys one of your windows, you're going to be buying a new window, instead of some other thing that you may have wanted more. If it destroys your whole town, a lot of money is going to shift from savings and investments into construction.
There is some advantage to having disaster insurance. First off, ordinary people are absolutely horrible at reasonably judging risks. Second, we are also pretty bad at compartmentalizing our savings and investments. If you have a 100-Year Flood fund, and a Yellowstone Goes Kablooie fund, and a Bad Tornado Season fund, and your grocery budget stands at $20 for this month, would you have the fortitude to eat nothing but beans and rice for four weeks? And third, institutional investors manage money better than a lot of individuals, and can take better advantage of the tax laws. It isn't hard to just dump everything into the Fideliguard Some of Everything Index Fund, but some people still put all their money in an ordinary commercial bank savings account, where the interest doesn't even cover the monthly service fees, but it still gets taxed.
But as you say, a lot of those advantages can disappear to just one bad actor in the insurance company trying to cheat a little for some personal gain. The best thing people can do to manage disasters is to be aware of their own risks, and to plan ahead only for those scenarios that have a reasonable likelihood of occurring.
there isn't a ton of flood preventation infrastructure that has been built with tax money.
All flood prevention infrastructure outside of the dirt berm at the local pond was built with tax money. Been to, say, New Orleans recently?
All of the premium non-hurricane, non-forest land, is taken already by rich people. Isn't it subsidising rich people if we allow them to live on the best land, while others contributing to society elsewhere observe no benefit?
It is interesting that some of the poorest, white-trash areas of the country are the safest. At least in Maine, the only natural disaster I can remember is the ice storm of 98, which, aside from knocking out power for a week, mostly amounted to an extra week of school vacation that winter.
I guess if you ignore the entire midwest?
Almost every region comes with its own set of possible natural disasters. Maybe we are better off pooling everything and just have natural disaster insurance that covers fire, flood, tornado, hurricane, earthquake, blizzard, and so on.
I'm not saying home insurance needs to be the same cost for everyone, but the current situation of specialized policies that vary house to house in each region is overly complex. Plus climate change is changing the risk profile for everyone and the results of which are not yet clearly understood by climate scientists let alone random homeowners.
I actually think it's not complex enough. How else do you accurately price natural disasters into existing homes, whose ownership is often measured in decades? I think any area with a chance over a certain percent of a natural disaster that could cause catastrophic loss of property should require insurance, and the insurance cost should be as accurate as possible to the reality of living in that location.
10. southeast michigan*
9. denver colorado
8. chicago illinois*
7. allentown pennsylvania* (actually east, not midwest)
6. dayton ohio*
5. bethesda maryland
4. buffalo new york
3. akron ohio*
2. cleveland ohio*
1. syracuse new york
Hmm, maybe you're thinking of the central US? also known as 'tornado alley'?
The definition of various 'areas' of the US are ill defined, but its clear, at least from my experience living in the midwest and having never experienced a single disaster in the 25 years I've been here, that the midwest is definitely the safest from natural disasters.
It is also worth noting that almost all of the cities listed are heavily impacted by snow which it doesn't sound like it was factored in to the ranking. Dealing with large snowfalls have a huge costs although it might not be factored in to normal home insurance since there is generally minimal property damage. It might be interesting to see a cost comparison between dealing with large snowfalls and other less frequent but more damaging weather phenomena like hurricanes or tornadoes.
Finally, Ohio certainly sees less tornadoes than most of the midwest, but it still receives a lot compared to the western US. Here is a nice visual summary of recorded tornadoes [1]. This one [2] is of especial interest and shows all tornadoes that have caused $50+ million in damage which would be important when talking about insurance. Tornado alley certainly gets more tornadoes, but Ohio is right up with them in terms of damage mainly due to the comparative development of the various areas.
[1] - http://uxblog.idvsolutions.com/2012/07/interactive-tornado-t...
[2] - http://1.bp.blogspot.com/-HlfovbQeMvg/UBFIgq0rAPI/AAAAAAAABP...
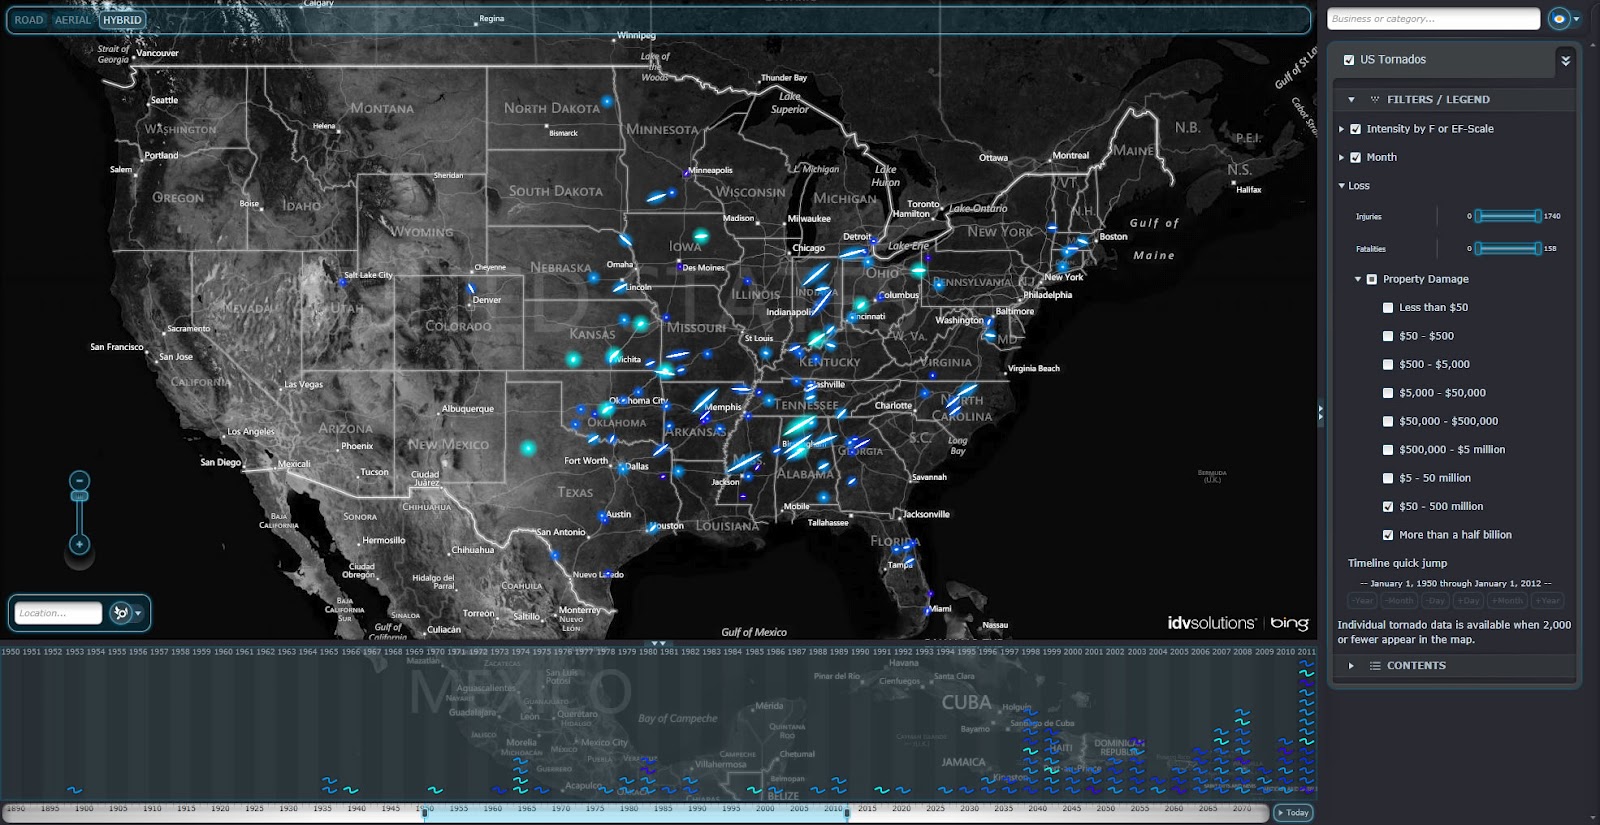
As for ohio, I count 6 tornados on there, maybe 7? (i might be reading it wrong)
since 1950?
I'd say thats pretty low risk.
How many earthquakes have we had in that time?
How many hurricanes have caused billions of damage in that time? Floods/draught/etc
> which it doesn't sound like it was factored in to the ranking.
I dont think it was, it was ranked by natural disasters - so unless its a major blizzard it probably wouldnt be measured. (oh they probably didn't include hail either, which is uncommon, but more damaging to property)
I also dont think snow is on the same level as a natural disaster from an insurance risk perspective, but it likely results in greater or at least similar fatalities overall so i think its a fair point.
I'm not arguing the midwest is immune to all danger, i'm only saying living there puts you at lower risk of being affected by a natural disaster - /and/ - that the land there isn't already owned by 'rich people' (to take us back to why i commented in the first place)
Also - i wish that tornado map was interactive, would be great to see more of the filters
Doing the math, it's pretty easy to guess that all that midwestern land is probably owned by "rich people", too.
I put that in scare quotes because there is some element of circularity involved. If you own 120 acres of cornfields, you have over $500k worth of property. So do you own the land because you're rich, or are you rich because you own the land?
Now do that math with land values in Detroit.
I think its well accepted that land values are generally quite higher on both coasts than the midwest. Agricultural land values are not very useful for estimating the cost of residential land
Edit:removed some snark
Ted Turner didn't get to own 2M acres of land by buying in Atlanta. Much of that is bison ranches.
There are a lot of people out there that own no more than 0.25 acre, which is pledged as security for a mortgage.
If you own land outright, free of liens and mortgages, whether rural or urban or in between, you're already way ahead of most people. You may not be actual rich, but "rich" by comparison with your neighbors.
Peering under the covers of agribusiness in the U.S. was somewhat enlightening. It would appear that one should not attempt a farming start-up without at least $1M in the bank, and you will only get about an 8% return on it per year, on average. Small farms simply do not make money; you cannot run a small farm as your sole source of income and expect to earn the equivalent of minimum wage.
So the natural conclusion I reached from my cursory research is that the vast majority of raw acreage in the U.S. is probably owned by investment trusts, who lease it for farming, mining, ranching, and logging, to people who barely earn a profit, and mostly just immediately spend 70% of everything they earn on expenses.
There's a good reason why YCombinator invests in tech start-ups instead of plows and cows.
[0] http://bigthink.com/strange-maps/291-federal-lands-in-the-us
http://www.wsj.com/articles/SB100014240527023043150045793833...
As for floods... I dunno, maybe insurance requiring some portion of the house that is higher than the flood plain and that the house is not in danger of becoming unmoored for any sort of sane rates. I imagine that would make housing in places way under the flood plane or that face both floods and hurricanes expensive to build in, which is the point.
Property/Casualty insurance (auto, home, work comp, etc.) are priced by analyzing recent loss experience, then trending loss costs forward (as medical costs & replacement costs go up over time).
Hazards that are infrequent and spatially-correlated (hurricane, tornado/hail, fire) are often priced by using simulations, which take into account the nature of the event, engineering simulations, and insurance policy terms.
Flood insurance is incredibly politicized, as it's handled at the federal level. Floods are typically considered an "uninsurable event" given that if you live in a flood plan, there's a high likelihood that you'll have a loss due to flood--less of an "if" than a "when".
Flood insurance is sold & claims are handled by insurance companies, but it is effectively reinsured 100% by the federal government. Actuarial studies have show the premiums to be highly inadequate, but there has been legislation that aims to reduce that inadequacy.
The article says that the portion of the budget dedicated to fighting fires keeps increasing, giving less money to land management decided to prevent a lot of the fires we are fighting. Seems to me that continuing on this path will just result in ever increasing costs. We have to let it burn, on our terms.
Typically, the way you would cut a piece of land is by selectively cutting out the species and grades of lumber that are actually worth money. So one winter you go in and cut the big, high-quality pine, or spruce and fir for saw logs. Another season you might cut out the high-quality veneer-grade hardwood trees. Of course, when you do this, you would also cut a bunch of the junk that is never going to grow into profitable timber, and sell that as pulpwood for making paper, or low-quality logs for making pallets, or sell it as firewood. If you selectively cut like this, it's not particularly difficult to rotate through a series of stands and continue to harvest them indefinitely, and you maintain a variable-age forest that sustains the local wildlife, to boot.
At least on the East coast, it's not really necessary to replant cut sections, even if you do go in and clear cut them, since there is so much residual seed on the ground already, and many of the species will even sprout again from stump. You go through a short cycle of black/raspberries and other scrub growth to fix the soil, then the young softwood/hardwood whips come up through, and within ten years you've got a stand of wood that's ready to be thinned out again, to clean out the junk and let the good wood grow up into profitable timber again.
On the West coast, as I understand it, replanting is more important, since many of the species won't grow from seed UNLESS there has been a forest fire.
The United States is also more forested now than it has been in a hundred years, since so much land formerly cleared for agriculture has grown back as forest. If you could look at Google Earth imagery of New England from 1900 and today, the difference would be astounding.
Second growth is only a step in the ecological process of producing a mature forest. Most of the east coast's regrowth is not representative of the original species, though it is often farther along in the process compared to the west coast. These places take multiple centuries to come back to their former pristine state.
Why does it take so long? Plant species are sensitive to available light and moisture. Canopies regulate this on the ground, but also rely on established plants for their development. Immature, modified or non-existent canopies cannot support the same life.
Selective cutting modifies the canopy. Established growth underneath does not survive, even if it is still alive when the crew goes home. When the canopy recovers in a single century the lower plants can thrive once again.
Secondly, the question was "why don't they thin things out". Not "why don't we let them thin things out". Implying a change to normal behavior.
Thinning is more expensive and difficult than clear cutting, which is why we don't do it often.
In the US, we are succeeding in reducing the rate of growth in CO2 emission. We're not yet succeeding in reducing total gases. We'd be a lot more successful if we stopped subsidizing the production and consumption of oil and coal. In 2013, the IEA estimates US$548 billion (annually) of global subsidy to fossil fuel. And the IMF calculates that including external costs (pollution), US$5.3 trillion of subsidy in 2015.
On what do you base the statement that a fire is typically "slow-moving"? It can certainly be fast. Here's an example. [1]
[1] http://www.thisiscolossal.com/2011/09/the-speed-of-fire/
More here: https://en.wikipedia.org/wiki/Native_American_use_of_fire#Hu...
Does lightning stop happening if people are gone?
If people did that, you couldn't buy fire insurance any more.
Let's look more positively at the problem. Use robots to fight fires. Use robots to manage fuel stocks. Learn more about firefighting as a species. I think we can get a lot better at fighting fires than we are right now.
EDIT: of course, if your house was left standing in the middle of a fire wasteland, you might want to live there anymore.
They have to be very large (and therefore expensive. Both in terms of land and in terms of maintenance) to protect your house against a mega fire though.
Of course, they could be created in preventative fashion to limit the fires so that the size of the forest fires is limited.
Source: I'm a wildland fire fighter. Have seen awesome and terrible uses of fireproofing property.
But as this article alludes to, it has to burn. It does naturally. We have to let go - we are wasting valuable resources to fight these fires. People have _died_ fighting these fires. And for what? So your house doesn't burn down?
I'm sorry, but a fire is typically a slow-moving natural disaster. It rarely strikes without a fair warning. I've been saying for years now that if you live in a potential burn area, know where your irreplaceables are, carry fire insurance, evacuate and LET IT BURN.
We can't keep fighting nature and winning.