News for hackers. Stuff that matters.
Re:U.S. interest rates have soared everywhere but savings ac... by azth on Saturday April 23, 2022 @12:01PM (#31135460)
Serious question: inflation seems to only be getting higher (is it 8%+ now?) the Fed's increasing of the interest rate is causing a stock market crash. So if one puts their money into assets, those are decreasing in price due to the fed, and if someone is holding cash that's also going down in value due to inflation. What's the solution?
Re:U.S. interest rates have soared everywhere but savings ac... by throw0101a on Saturday April 23, 2022 @12:37PM (#31135805)
Have a diversified portfolio. Rational Reminder went over the data in "The Ultimate Inflation Hedge":

> Is it possible to hedge your investments against different levels of inflation? This is the question we ask in today's episode, as we run through a variety of different investment approaches and commodities. While the answer may not come as a huge surprise, it is definitely worth the walk-through and getting to grips with what the literature can tell us in each scenario. After rounding up some news and a few reviews relevant to our usual subject matter, we dive straight into this topic, tackling the performance of stocks and bonds, gold, international stocks, value stocks, and more! We also share some general thoughts and questions to ask during periods where inflation is high, before positing our view that there is no single successful hedge against inflation, but rather our usual position of an adjusted and diversified portfolio will serve you as well in this regard as in others. We finish off this episode with a few of our usual quick cards, and this week's disturbing bad advice! So tune in to hear all about what you should know about expected and unexpected inflation and a whole lot more!

* https://rationalreminder.ca/podcast/150

Stocks generally bounce back, them going down isn't a big deal given the idea of 'buying low'.

Re:U.S. interest rates have soared everywhere but savings ac... by busterarm on Saturday April 23, 2022 @06:37PM (#31139336)
Also invest where you know/have an edge.

I've made judicious purchases in sealed Magic: The Gathering product. In just under 3 years, my initial 6-digit investment is up over 200%. Some purchases are wildly up and nothing so far has been a losing bet.

Other areas in collectibles I am also doing really well, like statues, classic cars, etc. Obviously a limiting factor is storage space.

I've lucked out due to some black swan type events but I can't see anywhere else where my investments are performing nearly as well.

Re:U.S. interest rates have soared everywhere but savings ac... by MisterMower on Sunday April 24, 2022 @11:58PM (#31150618)
I think this is the manifestation of the current inflationary environment. Anything fungible and easily transferable is gaining value because no one wants to hold dollars right now.
Re:U.S. interest rates have soared everywhere but savings ac... by coderaptor on Saturday April 23, 2022 @01:28PM (#31136273)
When everyone’s settled on maximizing the diversity of their investments, I wonder if the strategy loses viability as an effective hedge.
Re:U.S. interest rates have soared everywhere but savings ac... by throw0101a on Saturday April 23, 2022 @03:24PM (#31137546)
There will never be a point of time when "everyone" will do it, viz /r/wallstreetbets.

It's been known that trying to pick individual stocks is generally a sucker's bet since (at least) 1973, but people still try to do it:

* https://en.wikipedia.org/wiki/A_Random_Walk_Down_Wall_Street

Re:U.S. interest rates have soared everywhere but savings ac... by medvezhenok on Saturday April 23, 2022 @10:26PM (#31140748)
Same with gambling.

You will never get really rich (100M+) without stock picking but you’re going to be better off in the average case by sticking to the index.

Similar to working for a startup vs working for a large corporation - working at a startup is like stock picking:)

Re:U.S. interest rates have soared everywhere but savings ac... by poof131 on Saturday April 23, 2022 @02:12PM (#31136744)
If able, perhaps focus on your earning potential. We’ve had a forty-year run of asset price inflation relative to wage inflation. We may have hit the end of this period and will see a realignment with wages increasing at a faster pace than capital assets, similar to what happened in the 1970s. The Asset Economy is a somewhat dry but interesting book that presents a more academic take on the economic patterns of the last forty years.[1] The increase in unionization efforts, anti-trust, and the inability of the FED to manage inflation seem to point in this direction.

Otherwise, monopolies still seem strong for now with pricing power. Areas the government will print money to fund also seem like a decent bet: defense, climate, …? And you can try to maintain purchasing power with gold or crypto or real estate (in non-bubble areas). But we may be entering some challenging times for those with assets.

1. https://www.wiley.com/en-us/The+Asset+Economy-p-978150954345...

Re:U.S. interest rates have soared everywhere but savings ac... by pdog on Saturday April 23, 2022 @12:40PM (#31135836)
If you have inflation, something is going up in dollar terms. The answer is "real" assets: physical assets that have an intrinsic worth due to their substance and properties. Real estate, infrastructure, and commodities are all examples.
Re:U.S. interest rates have soared everywhere but savings ac... by kobalsky on Saturday April 23, 2022 @12:28PM (#31135707)
Bumping because I'm really interested in this answer.

For me the obvious answer is, if the fed actions means it's more expensive to borrow now, then lend your money. The question is how and where. Bonds? Which bonds? TIPS don't seem to have a rate that would protect me from inflation.

Gold? There's enough volatility there to lose more than 2 years worth of inflation with a badly timed entry, and I if I have to time my entry I'm trading, and I'm not a trader so I don't like it.

I know mentioning cryptos is sometimes taboo on HN, but if I lived in the US/EU I would convert a some portion of my savings into stablecoins and spread them out into some interest accounts to try to minimize counterparty risk. Their APY is running along inflation for the time being. At least until the dust settles and it's clear where to put your money.

Re:U.S. interest rates have soared everywhere but savings ac... by JumpCrisscross on Saturday April 23, 2022 @12:41PM (#31135845)
> TIPS don't seem to have a rate that would protect me from inflation

The TIP yield is a real yield. It's indexed to CPI-U, same as Series I bonds. (TIPs adjust monthly; Series I bonds semiannually.)

> would convert a some portion of my savings into stablecoins

This is probably the worst choice one can make. It's accepting a 0% nominal yield against an unregulated counterparty. A Bank of America savings account is literally a better choice.

Re:U.S. interest rates have soared everywhere but savings ac... by ericd on Saturday April 23, 2022 @01:01PM (#31136016)
This. Also, max put your Series I allocation ($10k/yr/SSN iirc, must be purchased from TreasuryDirect) before bothering with TIPs. If you have kids, the inflation adjustments can be used tax free for educational expenses, which would already make them the best inflation adjusted bond, but on top of that, you can cash it in whenever you want for nominal value rather than selling them on the secondary market, which makes them so much better than TIPs in the scenario where interest rates soar and inflation actually gets beat back (fwiw I don’t think this is as likely as currency devaluation).
Re:U.S. interest rates have soared everywhere but savings ac... by piotrkaminski on Saturday April 23, 2022 @01:33PM (#31136325)
Note that the tax-free educational expenses apply only to higher education and have an AGI cut-off, though. Read the fine print!
Re:U.S. interest rates have soared everywhere but savings ac... by ericd on Saturday April 23, 2022 @01:48PM (#31136480)
Ah thanks for the clarification! Have a link to a good explanation of the limitations?
Re:U.S. interest rates have soared everywhere but savings ac... by piotrkaminski on Saturday April 23, 2022 @01:53PM (#31136529)
I just poked around the Treasury site. It's a maze of little corridors all alike, but this one has some relevant info: https://www.treasurydirect.gov/indiv/planning/plan_education...
Re:U.S. interest rates have soared everywhere but savings ac... by ericd on Saturday April 23, 2022 @04:10PM (#31138025)
Had a bit of a hard time finding the actual AGI limit, but I found it here: https://www.irs.gov/publications/p970

Unfortunately, not that high:

You may be able to cash in qualified U.S. savings bonds without having to include in your income some or all of the interest earned on the bonds if you meet the following conditions.

- You pay qualified education expenses for yourself, your spouse, or a dependent.

- Your MAGI is less than $98,200 ($154,800 if married filing jointly).

- Your filing status isn't married filing separately.

Re:U.S. interest rates have soared everywhere but savings ac... by Asparagirl on Saturday April 23, 2022 @08:52PM (#31140228)
It’s $10k/yr/EIN, too. So if you perhaps have a family trust or a single-member LLC, disregarded on your taxes as Schedule C, that LLC or Trust can create an “entity account” at TreasuryDirect. It has slightly stricter restrictions than an account for a natural person, but certainly has the ability to purchase and hold and sell Treasuries too, including I Bonds.
Re:U.S. interest rates have soared everywhere but savings ac... by wallacoloo on Saturday April 23, 2022 @07:20PM (#31139650)
> > would convert a some portion of my savings into stablecoins

> This is probably the worst choice one can make. It's accepting a 0% nominal yield against an unregulated counterparty. A Bank of America savings account is literally a better choice.

you clipped out half the sentence:

> I would convert a some portion of my savings into stablecoins and spread them out into some interest accounts to try to minimize counterparty risk.

interest accounts. i.e. non-0% nominal yields.

Re:U.S. interest rates have soared everywhere but savings ac... by FabHK on Saturday April 23, 2022 @08:02PM (#31139938)
And have credit risk against some untested crypto-startup without FDIC deposit insurance?
Re:U.S. interest rates have soared everywhere but savings ac... by wallacoloo on Saturday April 23, 2022 @08:16PM (#31140012)
yes.

i'm not taking any stance on the risk v yield profile. i was just bothered by JumpCrisscross's mischaracterization of the earlier comment & wanted to correct that.

Re:U.S. interest rates have soared everywhere but savings ac... by kobalsky on Saturday April 23, 2022 @01:02PM (#31136024)
I was clearly misunderstanding how TIP yields worked, I'll read more about it. Thanks!
Re:U.S. interest rates have soared everywhere but savings ac... by imtringued on Saturday April 23, 2022 @01:40PM (#31136397)
The money illusion got you.

With demurrage currencies, everything works like TIPS. Yields may be negative but they are free from inflation and deflation.

It's kind of weird that people are choosing the money illusion over a negative yield/interest rate. I would rather have no inflation and see that the yield is negative than unpredictable inflation where the yield could be absolutely anything and I simply won't know.

Re:U.S. interest rates have soared everywhere but savings ac... by JumpCrisscross on Saturday April 23, 2022 @01:57PM (#31136583)
> they are free from inflation and deflation

No systemic measure is free from inflation or deflation in a dynamic market.

Prices move, sometimes in a correlated fashion, and credit waxes and wanes organically. Long-run inflation may be theoretically zero in some systems (constant money supply and magically constant velocity), but in reality, we have never observed this. (Even under commodity money systems with relatively constant money supply.)

Re:U.S. interest rates have soared everywhere but savings ac... by dragonwriter on Saturday April 23, 2022 @02:02PM (#31136623)
> With demurrage currencies, everything works like TIPS. Yields may be negative but they are free from inflation and deflation.

Not at all true of historical demurrage currencies, with are subject to inflation/deflation as normal but also have reduced nominal value over holding time.

ISTR the term has been resurrected for crypto products, but I can't find any details of how any crypto demurrage currencies work that would confirm or deny that they are somehow insulated from inflation/deflation and only change buying power by the demurrage charge, though I can't see it being likely to work in practice.

In theory, you could have what is basically a “stablecoin” managed against a price index like the CPI-U instead of an actual fiat currency and then add a demurrage charge on top of that (which could provide stabilization resources, so it's not completely irrelevant to function).

Re:U.S. interest rates have soared everywhere but savings ac... by Raidion on Saturday April 23, 2022 @12:40PM (#31135839)
Aren't stable coins pegged to USD subject to the same inflationary concerns as USD and counterparty risk? You're getting a few extra % return, but aren't the risk adjusted returns the same?

I honestly have the same questions as you though, I feel like if I was 100% sure of big inflation coming, all I'd know I want to do is get out of cash, but I don't know where to put my money. Part of me says Walmart, Dollar stores, and other inelastic merchants, but idk. Physical gold seems ok, but you're right in that if you overpay, you're overpaying for an asset that doesn't return anything.

Re:U.S. interest rates have soared everywhere but savings ac... by Rastonbury on Saturday April 23, 2022 @02:52PM (#31137180)
Bonds prices are going down due to interest rate increases. They traditionally are the hedge against stocks falling. There is no easy answer for this.

Don't make the mistake of increasing your risk appetite to chase perceive erosion of value from inflation. Inflation happen regardless, everyone wishes they could find a 8% risk free investment, they do not exist. If you're not a trader stick to an allocation you're comfortable with. The worst outcome is you try to trade in a bearish market and end up down, while inflation is still going.

Re:U.S. interest rates have soared everywhere but savings ac... by rufus_foreman on Saturday April 23, 2022 @01:14PM (#31136139)
Series I Bonds, although you are limited to $10,000 a year.
Re:U.S. interest rates have soared everywhere but savings ac... by jeffbee on Saturday April 23, 2022 @12:24PM (#31135670)
Consensus opinion seems to be that peak annual inflation already is behind us and mostly it was spectacular because of low March 2021. If inflation increases in the remainder of 2022, all the economic forecasts, and the federal reserve policy, are totally wrong.
Re:U.S. interest rates have soared everywhere but savings ac... by 01100011 on Saturday April 23, 2022 @10:49PM (#31140855)
That should read "Publicly stated consensus at the federal reserve, who massively screwed up by misreading inflation in the first place, is that peak annual inflation is behind us."

The bond market doesn't seem to believe it. The managing director of the IMF just publicly stated that the central banks screwed up and act like "8 year olds playing soccer" who don't anticipate the 2nd order effects of their actions.

20% of shipping is tied up in traffic jams. We're in a economic war with a major commodity producer. It is daft to believe inflation is peaking. Even if that assumption is right, we will end up with inflation well above the fed target rate, so instead of 8%(CP 'lie' bullshit inflation) we get 5% persistent inflation.

Re:U.S. interest rates have soared everywhere but savings ac... by HPsquared on Saturday April 23, 2022 @12:26PM (#31135693)
Inflation continuing to increase doesn't necessarily mean the policy is wrong. You need to consider the counterfactual: how much would it have increased without these measures?
Re:U.S. interest rates have soared everywhere but savings ac... by bezospen15 on Saturday April 23, 2022 @12:43PM (#31135861)
Powell was placed by Trump to feed the rich. It worked and now middle class will suffer
Re:U.S. interest rates have soared everywhere but savings ac... by okaram on Saturday April 23, 2022 @07:15PM (#31139618)
Yearly inflation seems to be going up mainly due to how it is calculated ... Monthly inflation seems to be going mostly sideways (although it has increased the last 3 months).

There's not (yet) been a market crash ... If you look back a month or a year, it's been mostly sideways too.

It may be the beginning of a horrible market crash ... But it may not ;). Trying to time the market, you're just as likely to lose as to win. Diversifying is always good; the stock market has usually provided the most growth long term. Unless you need the money soon, close your eyes and keep your money in the market.

Re:U.S. interest rates have soared everywhere but savings ac... by dehrmann on Saturday April 23, 2022 @01:33PM (#31136320)
> the Fed's increasing of the interest rate is causing a stock market crash

You think this is a crash?!

Re:U.S. interest rates have soared everywhere but savings ac... by 01100011 on Saturday April 23, 2022 @10:43PM (#31140820)
It will be. It isn't yet. Friday was a correction but it's nothing like what is coming. The Nasdaq isn't even below the lows set back in March. Yet.
Re:U.S. interest rates have soared everywhere but savings ac... by flatiron on Saturday April 23, 2022 @12:08PM (#31135521)
Based on the market a lot of people believe “buy some real estate” is the solution. But that bubble IMHO is about to pop.

Maybe look into interest protected bonds? https://www.treasurydirect.gov/indiv/products/prod_ibonds_gl...

Personally I have been just spending what I make assuming saving is moot right now (besides 401k and espp)

Re:U.S. interest rates have soared everywhere but savings ac... by ceejayoz on Saturday April 23, 2022 @12:57PM (#31135985)
> Based on the market a lot of people believe “buy some real estate” is the solution. But that bubble IMHO is about to pop.

I fear we're gonna move to an Australian-style real estate market. Never-ending boom, impossibly high prices for first-time buyers. People have predicted its collapse for 40 years or so, to no avail.

Re:U.S. interest rates have soared everywhere but savings ac... by HWR_14 on Saturday April 23, 2022 @01:28PM (#31136275)
> People have predicted its collapse for 40 years or so, to no avail.

Weird timeframe to claim nothing happened. They collapsed twice since then: 35 years ago and 13 years ago.

Re:U.S. interest rates have soared everywhere but savings ac... by ceejayoz on Saturday April 23, 2022 @01:31PM (#31136300)
Re:U.S. interest rates have soared everywhere but savings ac... by 01100011 on Saturday April 23, 2022 @10:41PM (#31140805)
It may not pop. Supply issues are real. Certainly it will deflate in the near term as mortgage rates rise further and the economy slows, but it doesn't seem likely to crash(and as a cash heavy renter I would love it to crash).

Some markets will likely see a bear market. Real estate is local. Location matters.

The future is very uncertain right now. I could see a scenario where China moves on Taiwan and we suddenly have 5+ million people looking for asylum. I guess it's one way to get TSMC to setup a plant here.

Re:U.S. interest rates have soared everywhere but savings ac... by chii on Sunday April 24, 2022 @02:26AM (#31141741)
> People have predicted its collapse for 40 years or so, to no avail.

you can only tell a bubble after it pops.

Re:U.S. interest rates have soared everywhere but savings ac... by tppiotrowski on Saturday April 23, 2022 @12:12PM (#31135557)
I think rising interest rates should depress the value of housing. With a higher interest rate you can't afford as much principal so you start bidding on cheaper houses.
Re:U.S. interest rates have soared everywhere but savings ac... by lijogdfljk on Saturday April 23, 2022 @12:33PM (#31135761)
I had this debate last night. Where i'm undecided is if this works when a housing market is propped up by cash.

Eg both houses and land purchases (something i'm trying to do) are quite a difficult market due to cash offers being consistently present. Ie a new family won't have 500k in cash and their loan offer isn't as good as a cash offer. It happened to me several times when i was buying my home ~6 years ago, 250k cash offers, 300k cash offers, etc. And ironically it just happened to me 2 weeks ago on a land offer. A 310k land offer (loan) beaten out by a higher value and pure cash offer.

So my question is if prices will really dip that much when seemingly so much of the house and land market are propped up by cash rich buyers. Hypothetically they don't care about high interest rates right?

Perhaps high interest rates will mean the cash rich people can offer less due to less competition, but if cash rich people are also competing against other cash rich people then.. i'm not so sure.

Thoughts?

Re:U.S. interest rates have soared everywhere but savings ac... by imtringued on Saturday April 23, 2022 @01:45PM (#31136438)
> Hypothetically they don't care about high interest rates right?

They care, because when interest rates go up, rich savers buy the dip.

That's one of the biggest ironies when it comes to people shouting that low interest rates make housing expensive. Yeah they make it expensive for those who already have enough money to buy a house outright. The amount of money you are paying on your mortgage in an area with a housing shortage is determined by your salary, not the interest rate.

Re:U.S. interest rates have soared everywhere but savings ac... by ItsMonkk on Saturday April 23, 2022 @01:15PM (#31136145)
Well, what happened in 2008? Stocks down 50%, housing down 30%. Buying housing was a better investment than stocks. But as both were down, simply holding cash was better. But that's only because the wealthy were hedging against a hyper-inflation scenario, and that scenario didn't occur.

In fact you can see this hedging as a reason for the inflation in the first place. Even things like target date funds that need to have 10%(or some other number) bonds have this same issue. When the interest rate rises, the value of bonds gets wiped out. But target date funds need to have a set percentage, so all of these indexes rush INTO bonds at this moment. The more stocks are up in this moment, the more these passive investments are selling stocks and buying bonds.

You can imagine that as stocks go up, the more stocks go up, wealthy money managers buy more and more homes in the exact same way they buy bonds. When they see that we might be about to hit an inflection point with stocks anticipated to go down, they should be selling stocks and buying whatever does better. In 2008, housing did better, so they'll probably do it even more with history on their side. Now that houses are up 30%, maybe they look for another investment. There it is, used cars. There it is, lumber, steel, oil. There it is, commodities futures. All with unprecedented demand, not from common folk, but the wealthy.

Hedging against a stock market crash causes inflation, and inflation causes interest rate rises, which is a positive feedback loop that causes more hedging, which causes more rate rises until the common folk can not handle it, in which case the economy falls over. At the end of the day we get a recession, massive job loss, and the Fed resets the interest rate back to zero and they start selling their assets and re-buying stocks. Cycle starts again anew.

Re:U.S. interest rates have soared everywhere but savings ac... by chii on Sunday April 24, 2022 @02:33AM (#31141771)
But how does purchasing assets by the wealthy (what you call hedging) produce inflation?

Inflation can only be produced if the demands for goods and services cannot be met and the price rises as a result.

Asset price increases are not inflation. A house's price going up is not inflation. Rent going up is. A house's rent is only indirectly related to the price of the house - there's a lot more that directly affect rents such as population growth or movement of people, changing preferences (some people might used to have house mates, but now prefer to live alone due to covid etc).

Re:U.S. interest rates have soared everywhere but savings ac... by ItsMonkk on Sunday April 24, 2022 @03:04PM (#31147159)
Right, inflation is based on consumption. So home prices going up is not inflation, as homes are considered investments. So when Bill Gates becomes the world's largest private farm-owner and buys a billion dollars worth of farmland, there's no inflation there, or is there?

Bill is in it for the short-term capital holding. He's going to do what he can to make as much money as he can, but if he thinks this is just a short-term flip, no need to build a full company around this, it's not worth it. He'll rent out what he can rent, find some sub-contractors to do what they can, and the harder to rent stuff just sits there.

That's the problem here. He's one man, with many responsibilities, hoarding over what might be 4000 different lots worth $250k. He just doesn't have the attention to deal with that. So while normal farmland owners will use everything they have, now we have a bunch of land empty, and that empty land is pushing the supply demand curve of all farmland over. And that's just one man doing a one percent hedge.

This same exact issue is happening in housing, and its happening at a scale much larger than a single billionaire. I bet there are thousands upon thousands of used cars just sitting in a field somewhere. There are legitimate business that need to ensure that they can get oil or steel or lumber or whatever else they need, and the futures markets are all insane because these investors know that the recession will hit before they need to buy, and everything else will drop in proportion to these commodities.

Re:U.S. interest rates have soared everywhere but savings ac... by beowulfey on Saturday April 23, 2022 @01:13PM (#31136131)
Does anyone know the numbers on whether the high cash offers are from corporate investors vs. exceptionally rich individuals? Given the sheer number of cash offers I'm inclined to think it's the former, but I honestly have no idea.

But yes, you're absolutely right that cash buyers should have way fewer concerns about interest rates.

Re:U.S. interest rates have soared everywhere but savings ac... by closeparen on Saturday April 23, 2022 @01:38PM (#31136375)
I would guess they are from otherwise-normal families whose current houses have appreciated in the same way. This makes them exceptionally rich in a sense, but also not, since homeowners are a majority in most metro areas and all homes are worth close to that much.
Re:U.S. interest rates have soared everywhere but savings ac... by bezospen15 on Saturday April 23, 2022 @12:40PM (#31135832)
That's only one piece of the puzzle. Economic hardship means investments stale or fail. All those real estate investors have fire sales, people lose jobs because of economic downturn and foreclosure, etc. It's all a domino effect, cash buyers are just another input to consider
Re:U.S. interest rates have soared everywhere but savings ac... by closeparen on Saturday April 23, 2022 @01:30PM (#31136292)
People have a lot of home equity because of prices taking off. I expect most of the cash in these offers is from equity in the buyer’s previous homes. It only takes little money injected from outside the real estate system to cause a bunch of these transactions between incumbent owners.

Houses are thought to be worth X. One house is available and one labor-rich renter buys it for 2X. This is now the market price of a comparable house. Two houses are available and their owners swap. This is a cash transaction at the same 2X price.

Re:U.S. interest rates have soared everywhere but savings ac... by chii on Sunday April 24, 2022 @02:36AM (#31141790)
The missing factor for real estate is that a lot of regulation and red tape is preventing new builds from coming online (and not just from NIMBYs but other factors related to lack of labour, materials etc).

at 2x the price, you'd imagine supply would grow to meet the demand. And yet, something (that i do not know) is causing the supply to not grow as expected.

Re:U.S. interest rates have soared everywhere but savings ac... by crate_barre on Saturday April 23, 2022 @12:26PM (#31135689)
The monthly payment of 28%-38% of gross monthly pay is harder to get to with the rising interest rate and rising home prices. You’d be looking at over 50% of your net take home pay per month (yes, over half your months paycheck, especially in high cost of living areas). They are fucking pricing everyone out other than investors or existing home owners that can tap into home equity.

And rent is nearing 1900 nationwide. How is that even reality?

If people just started killing landlords and investors I personally wouldn’t give a fuck (I’m kidding, not advocating this, but that’s how bad actors these animals are).

Re:U.S. interest rates have soared everywhere but savings ac... by bezospen15 on Saturday April 23, 2022 @12:41PM (#31135851)
Can't keep at this pace for much longer. We'll know more in 12 months, stay liquid for now
Re:U.S. interest rates have soared everywhere but savings ac... by icelancer on Saturday April 23, 2022 @04:48PM (#31138377)
I-Bonds are getting a lot of attention lately, and with good reason. Still underexplored, and there's a cap on them ($10k/person with limited workarounds), but well worth checking out for everyone reading this.
Re:U.S. interest rates have soared everywhere but savings ac... by MrFoof on Saturday April 23, 2022 @06:23PM (#31139217)
Moreover, if you think the current 7.12% yield is great, if you look at the recently released CPI numbers it may be adjusted to 9.62% in May.
Re:U.S. interest rates have soared everywhere but savings ac... by sb057 on Saturday April 23, 2022 @12:42PM (#31135855)
If the cause of inflation is the same amount of dollars bidding up a lesser quantity of goods, the only way to resolve the situation is to increase the number of goods or decrease demand for them.
Re:U.S. interest rates have soared everywhere but savings ac... by MisterMower on Monday April 25, 2022 @12:13AM (#31150687)
No, the correct way to do it is to reduce the size of the money supply, or at least slow its growth.

Inflation is always and everywhere a monetary phenomenon.

Re:U.S. interest rates have soared everywhere but savings ac... by sb057 on Wednesday May 04, 2022 @12:05PM (#31262353)
All other factors being equal, that would be tantamount to reducing demand. Nominal prices would fall, yes (deflation), but a failure to increase supply would result in shortages. Shrinking the money supply would have quite a similar effect to price ceilings in this scenario.
Re:U.S. interest rates have soared everywhere but savings ac... by keewee7 on Saturday April 23, 2022 @01:02PM (#31136026)
>So if one puts their money into assets, those are decreasing in price due to the fed

Unless you are a day trader (or r/WallStreetBets trader) this should not be a long-term concern.

>Time in the market beats timing the market.

I have my assets in an S&P500 ETF and some Danish funds and stocks. Owning a good home in a first-world country is also a good long-term investment.

Re:U.S. interest rates have soared everywhere but savings ac... by _ink_ on Sunday April 24, 2022 @04:44AM (#31142279)
If you live in America and just want to protect your buying power against inflation: buy I-bonds. You cannot sell them for a year and can only buy 10k per year. But they pay interest roughly the same than inflation. For us plebs from the rest of the world without access to I-bonds I have no idea.
Re:U.S. interest rates have soared everywhere but savings ac... by adam_arthur on Sunday April 24, 2022 @12:45PM (#31145753)
Common misconception is to avoid cash in an inflationary environment. When inflation hits hard, discount rate for assets increases commensurately which pushes down asset pricing.

Better to hold cash up until the point that the discount rate has mostly priced it in, then buy assets

Re:U.S. interest rates have soared everywhere but savings ac... by justincormack on Saturday April 23, 2022 @12:12PM (#31135556)
There isn't one, there is a market and prices are adjusting, the price of temporal work transfer.
Re:U.S. interest rates have soared everywhere but savings ac... by _wldu on Saturday April 23, 2022 @01:42PM (#31136413)
Consider buying stock in companies that produce real products that everyone needs. Food, cleaning supplies, toilet paper, hygiene, etc. It's hard to go wrong doing that.
Re:U.S. interest rates have soared everywhere but savings ac... by astura on Saturday April 23, 2022 @04:42PM (#31138312)
Re:U.S. interest rates have soared everywhere but savings ac... by chii on Sunday April 24, 2022 @02:45AM (#31141820)
But everyone already knows of this fact - and so the price of those stocks would already reflect the value under an (expected) inflationary environment.

The value would only grow _if_ the inflationary environment is worse than expectations, and people sacrifice even more discretionary spending to buy consumer staples. if the inflationary environment isn't as bad as expectations, then these companies would be out-performed by other, higher growth, discretionary goods companies.

There's no such thing as a risk free investment.

Re:U.S. interest rates have soared everywhere but savings ac... by dragonwriter on Saturday April 23, 2022 @01:54PM (#31136546)
> ...stock market crash. So if one puts their money into assets...

“Assets” is much broader than, and other categories don't consistently follow, the stock market.

Re:U.S. interest rates have soared everywhere but savings ac... by 01100011 on Saturday April 23, 2022 @10:31PM (#31140773)
The solution is ask a real professional, not HN amateurs like me.

If you want my crank opinion though, at this stage in the economic cycle you should be in commodities. Sure, you're late to the party and they're going to make you ill with their volatility, but generally that's where you want to be now.

Other options are recession plays like consumer staples. Think about the things people will still have to buy or will downgrade to in a recession. I bought $BUD and $TAP because I think people will drink cheap beer. Cigarette companies are good if you have no conscience and can catch them on a downswing(they're already up). My $KHC bet I made 6 months ago is probably the best thing in my portfolio right now. You have to be prepared for days like last Friday when nearly every stock was down. People are fleeing to dollars, so actually having cash right now isn't a bad thing. Your cash already lost value. We may see a dollar squeeze as people flee to safety and the fed drains liquidity from the financial system before the dollar continues its downward slide(late this year?).

Everything depends on the threat of war right now. Not enough people are talking about the supply disruptions happening. 20% of the world's container ships are currently in traffic jams thanks to Chinese COVID paranoia. Russia, a major commodity supplier, is cut out of the Western financial system. Fertilizer and energy are spiking. Recession may have peaked but it will settle into a steady 5+% rate unless the fed grinds the economy to a halt.

War may already be happening behind the scenes. The FBI is now warning(https://www.ic3.gov/Media/News/2022/220420-2.pdf) of attacks on our food infrastructure, possibly connected to the rash of fires occurring at food processing plants(stuxnet being fed back to us?).

Indonesia just suspended palm oil exports. They make something like 60% of the global supply. Countries are becoming protectionist. We are reverting in some ways to a pre-globalist world.

Sweden and Finland are likely joining NATO. The tensions with Russia aren't going away anytime soon. Even though Putin looks to be in poor health, the Russian aggression is not purely a product of Putin but baked into the national identity of Russia's elites. Maybe a good play, despite already taking off, is defense industry stocks(Lockheed, Raytheon, etc). The world is entering a very unstable period.

One thing you should consider doing as well: buy things you'll need over the next year. They're only going to get harder to buy and they're going up in price. Like a certain brand of shampoo? Why not buy a year's worth. Stockpiling is horrible on a national level, but as an individual it will help you cope with some of the price increases while your dollars would otherwise be stagnating or decaying.

Lets hope the bond market is currently wrong, because they seem to be pricing in many more hikes than the fed thinks will need to happen. There is a risk that inflation becomes unhinged and spirals for a while. The West isn't prepared for that sort of financial doom scenario.

Re:U.S. interest rates have soared everywhere but savings ac... by imgabe on Saturday April 23, 2022 @06:48PM (#31139416)
Monkey jpegs
Re:U.S. interest rates have soared everywhere but savings ac... by naruvimama on Saturday April 23, 2022 @04:34PM (#31138239)
Inflation is high because of supply shortages and lower production, increasing rates would mean increasing the cost of setting up new supplies or production lines.

Manipulating interest rates works when under otherwise normal condition the government wants to prevent overheating economy or to provide stimulus during a down cycle.

It is not immediately clear if the rate increases is going to help increase production or stabilise supply chains, perhaps just the contrary.

Re:U.S. interest rates have soared everywhere but savings ac... by chii on Sunday April 24, 2022 @02:43AM (#31141813)
> Manipulating interest rates works when under otherwise normal condition

back in the oil crisis of the 70's, the inflation was high because oil embargo made everything that need oil (which was everything) more expensive.

Couldn't you make the same argument back then, that increasing interest rates isn't going to end the embargo and lower inflation? And yet, the then Fed chair did increase interest rate to combat inflation (granted, the inflation back then was much worse than now).

So perhaps this time, it's different - covid supply shocks playing out is not going to get resolved by interest increases. By increasing rates, the only result is to reduce demand, which is just another way of saying those who can't afford it will have to sacrifice, and lower their quality of life.

Re:U.S. interest rates have soared everywhere but savings ac... by PheonixPharts on Saturday April 23, 2022 @12:28PM (#31135703)
> Fed's increasing of the interest rate is causing a stock market crash.

Citation needed.

Rate hikes were announced mid-march and I don't think you can even find that info on this chart https://finance.yahoo.com/quote/%5EDJI/

If we do see a crash soon I think it will likely be more related to major tech stocks failing to perform as expected. Of the original FAANG, F and N have both had days where there value dropped ~30% in a single day in the last six months, and that has nothing to do with interest rate hikes.

Re:U.S. interest rates have soared everywhere but savings ac... by sb057 on Saturday April 23, 2022 @04:05PM (#31137968)
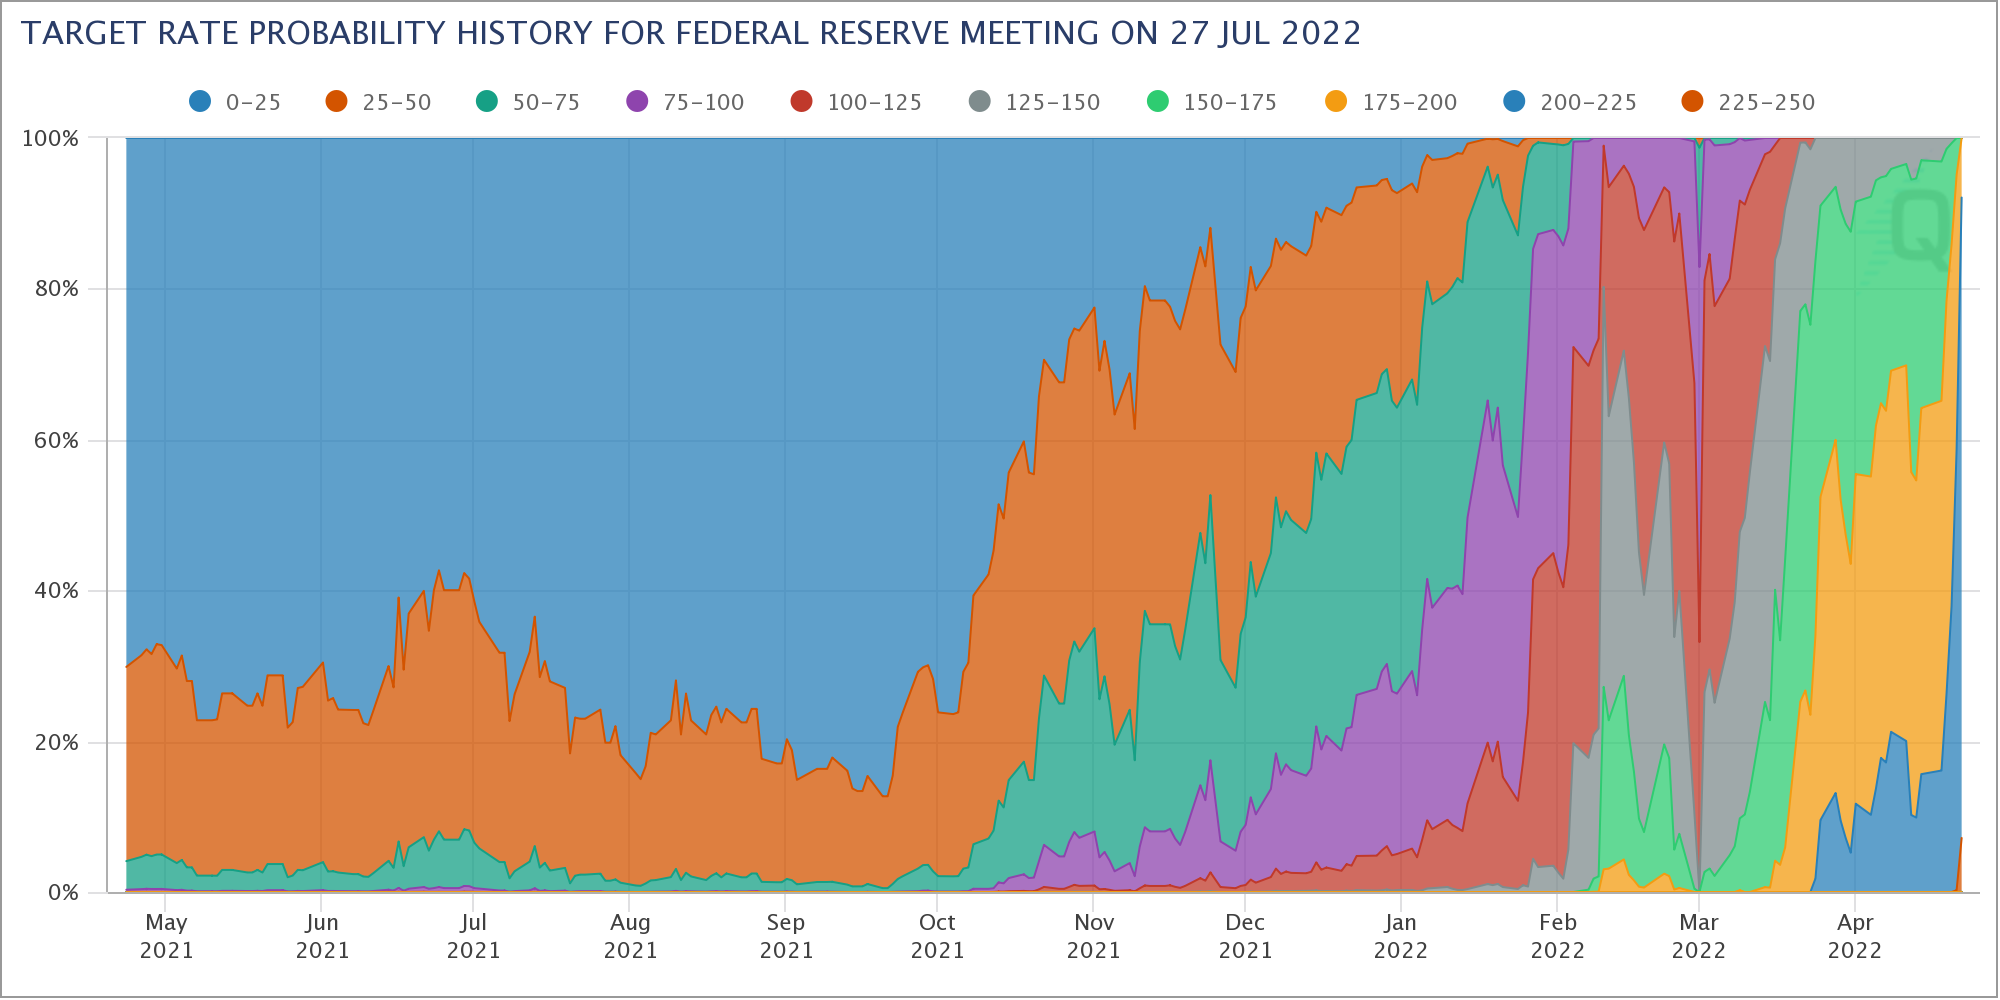
The CME's FedWatch tool shows investors started pricing in rate hikes around November, with a sharp uptick in acceleration starting around February.

https://files.catbox.moe/cs4gtg.png

https://www.cmegroup.com/trading/interest-rates/countdown-to...

Re:U.S. interest rates have soared everywhere but savings ac... by darth_avocado on Saturday April 23, 2022 @01:06PM (#31136064)
Well fed increased rates in March but they announced it long ago and the market corrected accordingly. It is common knowledge by now. The market is expecting 7-8 25 point increases in 2022 which has been priced in the declines so far. Any deviation to that will move the markets further.
Re:U.S. interest rates have soared everywhere but savings ac... by 01100011 on Saturday April 23, 2022 @10:50PM (#31140866)
What the bond market has priced in and what equities have priced in are two completely different scenarios. If the bond market is right, equities are about to get slaughtered.

Remember, the fed folks can't insider trade like they used to, so they have no reason to prop up equities anymore. They made their money.

Re:U.S. interest rates have soared everywhere but savings ac... by cudgy on Saturday April 23, 2022 @10:41PM (#31140807)
How do you know this? My inclination is to think investors are underestimating the effects of inflation and overestimating the Feds ability to counter it without major rate hikes (like above 7-8% or higher). The Fed has created a major problem by keeping rates so low for so long. Who is going to buy the bonds they are going to have to sell in order to back off quantitative easing. Plus now there is the threat to the US dollar remaining the preferred currency with the Biden administration seizing almost a trillion dollars worth of Russian dollar denominated assets. Other countries are likely taking notice of this.
Re:U.S. interest rates have soared everywhere but savings ac... by sanctified384 on Saturday April 23, 2022 @03:22PM (#31137528)
Just because the formal rate increase happened in March doesn't mean people didn't know about it already. Rate hikes are typically speculated on for several weeks (months?) before they actually happen. By the time it actually happens, the market has always priced it in. The decrease in Jan/Feb was in anticipation of the March increase. And the current swings are in anticipation of the May/June increases.
Re:U.S. interest rates have soared everywhere but savings ac... by jimbob45 on Saturday April 23, 2022 @05:33PM (#31138807)
Even if that were true, you necessarily have to hike the interest rate intermittently to ensure you have room to lower it when the crash inevitably happens.
Re:U.S. interest rates have soared everywhere but savings ac... by cwalv on Saturday April 23, 2022 @01:43PM (#31136424)
The valuation of growth stocks (of any sort, not just tech stocks) is very heavily influenced by interest rates