News for hackers. Stuff that matters.
Re:Offline Algorithms in Low-Frequency Trading by hntrader on Saturday January 30, 2021 @09:00AM (#25969112)
What does the tail risk look like on this strategy and what kind of annual return do you expect?
Re:Offline Algorithms in Low-Frequency Trading by im3w1l on Saturday January 30, 2021 @09:53AM (#25969530)
Selling a deep in the money put behaves like owning the stock (probably with margin, but it depends on how many puts you are selling compared to your reserves of cash and short term "safe" bonds) except that you are capping your gains.

The further towards out of the money you go the more it behaves like picking up pennies in front of a steamroller. But an interesting quirk of selling puts compared to calls is that the downside is limited. The stock can't go below 0.

Re:Offline Algorithms in Low-Frequency Trading by hntrader on Saturday January 30, 2021 @01:49PM (#25971754)
That gives me a good intuitive picture. I'd really love a basic online simulator where I can plug in portfolio characteristics (eg percent of calls Vs puts, ATM Vs OTM) and simulate an equity curve over the last ten years. I could build my own of course but I think a tool like this would be generally useful for investors.
Re:Offline Algorithms in Low-Frequency Trading by Schweigi on Saturday January 30, 2021 @10:36AM (#25969881)
I did make my own option trading algo which is similar to the one in the Git Hub repo (but I used Scala, which gave me additional returns, jk :) ). Return totally depends on the delta of the options you write and the option symbols in your basket. Mine could be configured to be between 10-100+%. The higher the return the more volatile.

The idea of using multiple symbols like SPY and TLT is to reduce the tail risk. But in the end there is still tail risk like for example in the crash of 2015. Making the strategy delta neutral with hedging could improve it but I never completed that part.

There is an interesting book with all the math by Euan Sinclair about option writing and how to minimize the risk if you are interested.

Re:Offline Algorithms in Low-Frequency Trading by hannofcart on Saturday January 30, 2021 @01:50PM (#25971766)
Another way to reduce tail risk when selling options is to simply hedge with a protective call/put at a higher or lower strike respectively. Sufficiently far off strikes will have minimal impacts on returns while reducing tail risk.
Re:Offline Algorithms in Low-Frequency Trading by scruple on Sunday January 31, 2021 @02:24AM (#25976886)
These are known as a Poor Man's Covered Calls and Poor Man's Covered Puts.
Re:Offline Algorithms in Low-Frequency Trading by omarhaneef on Saturday January 30, 2021 @09:40AM (#25969421)
You’re taking the tail risk on the down side but you’ve sold it on the upside for extra yield.
Re:Offline Algorithms in Low-Frequency Trading by artemonster on Saturday January 30, 2021 @09:49AM (#25969494)
I undestand words but I have absolutely no clue what you're talking about. Can you recommend some books on the topic?
Re:Offline Algorithms in Low-Frequency Trading by omarhaneef on Saturday January 30, 2021 @10:10AM (#25969661)
I would look up two terms:

Covered calls

Naked puts

If you want to go heavy duty into it I recommend the Hull book (options, futures and other derivatives) but for your purposes the investopedia articles are enough.

Basically naked puts means you’re selling downside insurance so if the stock crashes you eat the loss. Covered calls mean you sell upside risk but have the stock so if it goes up you make a little.

Re:Offline Algorithms in Low-Frequency Trading by beezle on Saturday January 30, 2021 @01:18PM (#25971425)
Hull is a great book and is not too heavy on the math. However, for someone just getting their feet wet, Options as a Strategic Investment by MacMillan is a classic.
Re:Offline Algorithms in Low-Frequency Trading by im3w1l on Saturday January 30, 2021 @10:08AM (#25969645)
The "tail" in tail risk referes to the tails of a probability distribution. A normal distribution has "thin" tails. The probability of huge outliers is pretty low.

If you have tail risk, then it means you have a decent chance of losing a lot more money than the typical variation. Your returns might look like +1.1, +0.9, +1.2 +1.05, -3. So your profit is pretty predictable with little variation, until suddenly you lose a lot of money.

Re:Offline Algorithms in Low-Frequency Trading by wbl on Saturday January 30, 2021 @10:26AM (#25969803)
The only book you should read is John Bogel's. Do what he says like Goldman partners, Bank of America senior executives, almost every economist does with their money and stick it in low cost diversified mutual funds.

Or you can learn stochastic calculus and end up in the same place once you realize half of all active traders do worse than the market, before fees.

Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @12:06PM (#25970748)
None of the kinds of people you listed are good at trading (esp economists). From experience, professional traders do tend to use passive indices for part of their PA, but also actively trade a portion.

But you're right in that if you don't have a passion for it, you'll never be able to truly outperform spy on a risk adjusted basis. However, if you do have the knowledge and the passion, I definitely think you can.

Investing is personal, and just holding spy doesn't fulfill everyone's objectives.

Here's an example of a strategy that outperforms spy in most cases: 1/3 of your portfolio goes to upro (3x leveraged spy) and 2/3s goes to a bond fund/etf. As long as the bond etf returns above the upro expense ratio (~1%), you will outperform. From my backtests, this strategy will earn you an extra 1-2% return a year, while also having a slightly higher risk adjusted returns.

I list the above as a great example because it's the kind of strategy that is great for a PA: easy to manage, doesn't require babysitting, and backed by solid academic research. When people think active vs passive, they think actively trading single stocks vs just holding an index. My point is that you can use some quant-lite strategies that tilt your portfolio to eek out a little return. You don't have to be trading everyday or even holding anything except ETFs.

Re:Offline Algorithms in Low-Frequency Trading by victor106 on Saturday January 30, 2021 @04:05PM (#25972980)
While I always preached just buying the S&P one risk i've been seeing with it is if, a majority of investors just buy the S&P index, since the index is market cap weighted, it would just make the largest stocks in the index more expensive.

This would make the stocks that have less weight in the index or stocks outside the index relatively cheap and obviously offer better returns.

Anyone disagree?

Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @06:04PM (#25973926)
Assuming the amount of tradable shares for each stock is proportional to the free float capitalization (which is not a particularly good assumption), each stock in the index should be pushed up by the same amount, since the weight of each stock in the index is proportional to the market cap of the stock. I don't think this is actually true (i.e the number of shares on the market is not proportional to the market cap), which would imply that some share prices would be affected more than other. Do higher weight stocks in spy get pushed up more? I don't know. But it is certainly possible.

With respect to the stocks just outside the index, I think you could argue that they are probably undervalued and thus should offer better returns. This is what an academic would say. However, the actual reality could be a lot different: if returns are dominated by flows instead of fundamentals (like they are now), maybe going with the crowd is the best investment strategy. Or maybe not, I haven't done the research.

One thing that every market professional is worried about right now is just how dysfunctional valuations and returns seem to be in the modern era. Stocks seem to go up for no reason and returns have been disconnected from both fundamental and quantitative risk premia.

What I can say for sure is that we are in a period of intense change in the financial system. No one knows what the future of finance will look like, 10 years, 20, or 30 years out. Will crypto defi take over? Will traditional finance be disrupted? No one knows, but it is certainly an exciting time to work in the capital markets!
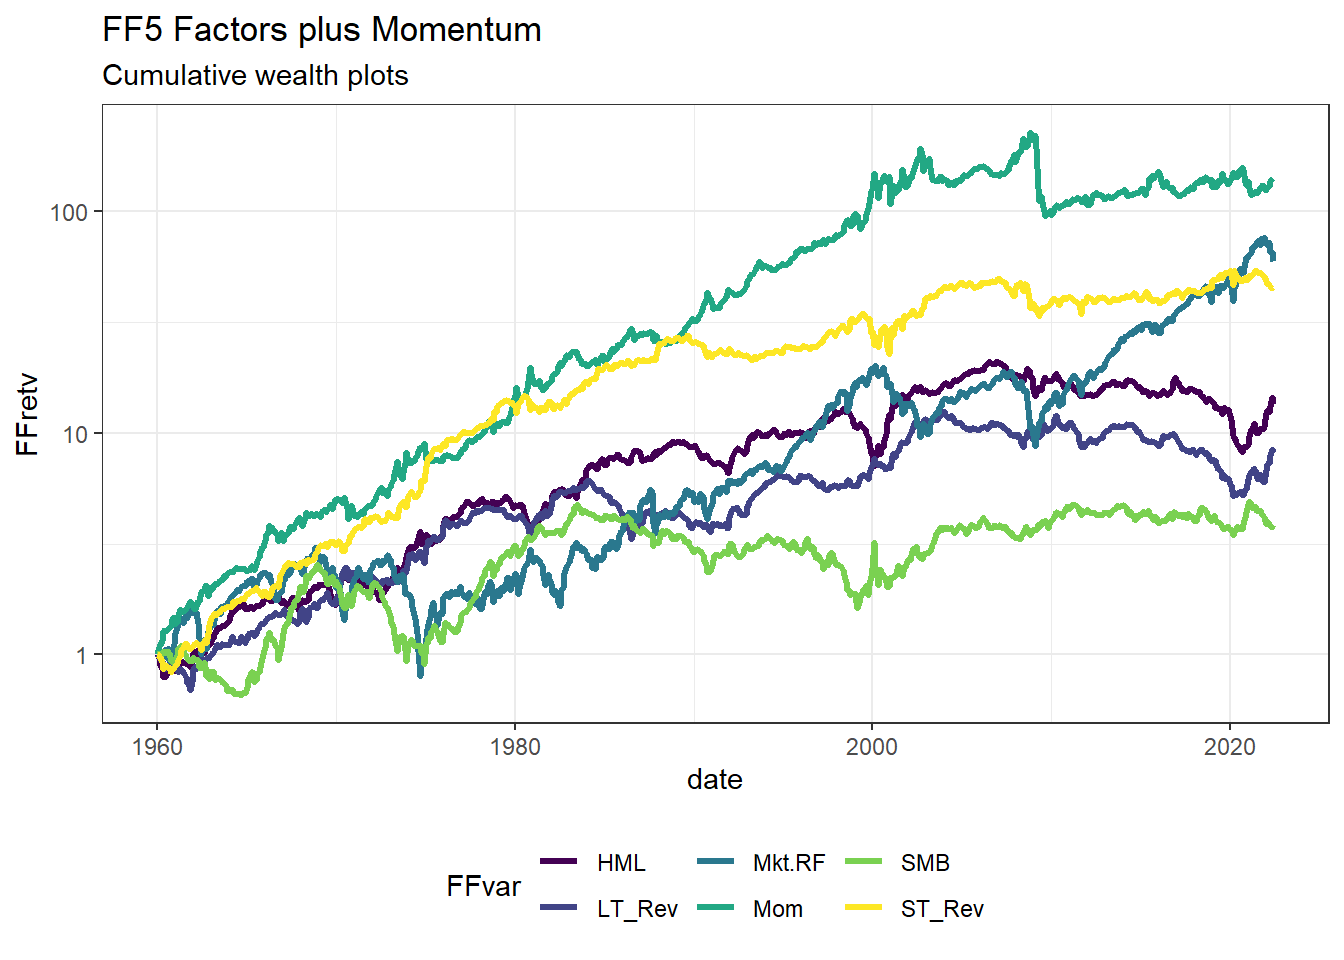
Re:Offline Algorithms in Low-Frequency Trading by kgwgk on Saturday January 30, 2021 @06:41PM (#25974202)
Reality seems to disagree: https://www.sebastianstoeckl.com/post/ffdownload/index_files...

https://en.wikipedia.org/wiki/Fama–French_three-factor_model...

SMB stands for "Small [market capitalization] Minus Big" and measures the historic excess returns of small caps over big caps.

Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @09:00PM (#25975036)
A lot of ff research is not very rigorous and highly suspect imo. it's more likely imo that smb is a risk premia than some sort of alpha factor
Re:Offline Algorithms in Low-Frequency Trading by kgwgk on Saturday January 30, 2021 @09:05PM (#25975066)
The factors in the Fama-French model are risk premia, I cannot make any sense of what you say.

See for example https://www.msci.com/documents/1296102/1336482/Foundations_o...

Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @09:12PM (#25975108)
Sorry, I'm using risk premia incorrectly (quant equities isn't actually my thing).

What I mean is that I don't believe smb truly delivers superior risk adjusted returns. For example, I believe the betting against beta factor (BAB) does, while smb does not.

Re:Offline Algorithms in Low-Frequency Trading by kgwgk on Saturday January 30, 2021 @09:21PM (#25975149)
We agree then, the size factor has not been really outperforming since it was introduced in the nineties. Maybe the drivers of the outperformace were things like transaction costs and lack of information which are less of an issue in recent times.

For what it’s worth, the value factor is not doing well recently either...

Re:Offline Algorithms in Low-Frequency Trading by smabie on Sunday January 31, 2021 @02:05AM (#25976773)
you sound like a quant. are you l? if so, always like to network/talk/make connections

hmu

Re:Offline Algorithms in Low-Frequency Trading by eloff on Saturday January 30, 2021 @01:20PM (#25971452)
This strategy seems to make a lot of sense to me, so I just checked out the performance of UPRO over the last 5 years versus SPY (^GSPC).

UPRO is up 426% (wow) $17.37-$74.01

and

^GSPC is up 192% (talk about a bull run) $1932-$3714

So with UPRO you would have had an average profit of 65.2% per year, and with SPY 18.4% per year. That's even better than x3 returns.

Plus you'd have the bond returns. Interesting idea.

Re:Offline Algorithms in Low-Frequency Trading by StrangeDoctor on Saturday January 30, 2021 @02:14PM (#25971995)
You absolutely do not want to own upro for 5 years. High fees and more importantly beta-slippage will eat you alive.
Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @02:42PM (#25972255)
by beta slippage you mean volatility drag? On a risk adjusted basis, upro is definitely a loser due to volatility drag and high expense ratio. However, you can easily calculate optimal leverage ratio in order to maximize the geometric growth of your portfolio. The equation is:

lev = E(r) / Var(r)

So if the expected return is 10% and the expected volatility is 10%, optimal leverage to maximize geometric growth is 10x.

This of course is much too high and the risk of losing everything due to excessive kurtosis and downside skew is very high. Like the everything else in finance, fundamental sin of that formula is assumption of the log normality of returns.

However, is 3x too high for the long term? I dunno, but over long time periods, a pure 3x leveraged spy portfolio is going to outperform significantly. The problem is most people will be unable to weather the storm as you can easily lose half of your money in a week.

I wouldn't hold pure spy 3x and wouldn't exactly recommend it, but from a mathematical perspective it is a defensible (as in, you can make cogent arguments for it) long term investment.

On the other hand, I would probably recommend 1.5x lev or possibly even 2x lev to certain people.

As a quant, I approach these things like leverage from a mathematical perspective. It's important not to have an emotional reaction. There are very smart people running books that have 10x leverage but you would never be able to guess by looking at their volatility. It's all about the factor exposures, net delta, etc.

For example I've seen 15x leveraged delta neutral books that have absolutely insane Sharpe ratios (>15) and annualized volatility of less than 5%.

Re:Offline Algorithms in Low-Frequency Trading by kgwgk on Saturday January 30, 2021 @07:47PM (#25974598)
> However, is 3x too high for the long term? I dunno, but over long time periods, a pure 3x leveraged spy portfolio is going to outperform significantly. The problem is most people will be unable to weather the storm as you can easily lose half of your money in a week.

You don't define "long time periods" but the storm may be much longer than one week.

If you had invested with 3x leverage (daily rebalanced) in the S&P 500 anytime in 1999 or 2000 you would have been down over 90% in 2009 and you wouldn't have broken even until 2014 or 2016.

Re:Offline Algorithms in Low-Frequency Trading by eloff on Saturday January 30, 2021 @03:32PM (#25972716)
Well you would have done just amazing (as I pointed out) over the last 5 years. Better than 3x the S&P 500.

I'm not saying you don't have a point, but one would need to look at how it performs over longer periods with more varied market conditions to answer your question.

Re:Offline Algorithms in Low-Frequency Trading by kgwgk on Saturday January 30, 2021 @07:07PM (#25974358)
It depends a lot on the period (and I think you didn't include dividends?).

  1 year:   SPY  +15%  -  UPRO   +2%
  3 years:  SPY  +37%  -  UPRO  +33%
  5 years:  SPY +110%  -  UPRO +325%
Since 2016 is in line with the x3 promise. Since 2018 or 2020 definitely not.
Re:Offline Algorithms in Low-Frequency Trading by eloff on Saturday January 30, 2021 @07:19PM (#25974439)
Good catch, I forgot dividends.

Interesting that the last year performance was so bad - I think that stock market drop back in March and the general volatility / reshuffling since then must have hurt the leveraged strategy.

Re:Offline Algorithms in Low-Frequency Trading by smabie on Saturday January 30, 2021 @02:06PM (#25971919)
UPRO is only 1/3 of your portfolio, so you have the same exposure as SPY i.e: you are not going to make those crazy returns.

The idea is to get cheap borrowing by using a leverage ETF and then buying bonds such that the bond yield > cost of leverage.

Re:Offline Algorithms in Low-Frequency Trading by eloff on Saturday January 30, 2021 @03:29PM (#25972672)
You're arguing against a strawman argument that you invented.

I didn't say you would get those crazy returns - merely pointed out that you would have beat the S&P 500 over the last 5 years with the strategy outlined by the parent post.

How well it holds up over a time period that also includes bear markets is another question - you can't just look at a bull market and assume it's representative of all time.

Re:Offline Algorithms in Low-Frequency Trading by hntrader on Saturday January 30, 2021 @01:53PM (#25971801)
Isn't UPRO just a leveraged SPY. Seems different to the above option selling strategy
Re:Offline Algorithms in Low-Frequency Trading by eloff on Saturday January 30, 2021 @03:30PM (#25972686)
You must have skipped over and didn't read the parent post at all. We're not talking about the wheel strategy here.
Re:Offline Algorithms in Low-Frequency Trading by joshribakoff on Saturday January 30, 2021 @10:33AM (#25969862)
Buffet sells 5b in options premium a year
Re:Offline Algorithms in Low-Frequency Trading by atomicnumber3 on Saturday January 30, 2021 @10:59AM (#25970068)
I think a big distinction that retail traders need to come to terms with is that, while yes, technically you can make reasonably good sums of money with various trading strategies of various risk profiles, as one person, so many of them are just not worth the trouble.

If your passion is this sort of thing, by all means, go ahead.

But it's like running a homelab. Yes, you can get pretty decent "savings" (vs running in AWS/DO) but I can guarantee you, you will end up in the basement replugging ethernet cables trying to figure out which one is the bad one while your family and relatives are waiting upstairs, fairly bemused, for you to fix "the internet".

It's possible, but as a person with a life, unless it's your passion, I'd recommend just not. Do the financial equivalent of paying DigitalOcean 5 dollars a month: buy sp500 etfs and sit on them.

Re:Offline Algorithms in Low-Frequency Trading by hntrader on Saturday January 30, 2021 @01:54PM (#25971811)
I wonder if we can invest in a fund manager who does this strategy. And if it's so good then why do pension funds and endowments not allocate to it typically.
Re:Offline Algorithms in Low-Frequency Trading by rusticpenn on Saturday January 30, 2021 @10:00AM (#25969582)
Yes, me too. I just read about someone calle 1ronyman on Reddit, and I am interested too.