News for hackers. Stuff that matters.
Re:Affordable Care by smnrchrds on Friday January 13, 2017 @01:27PM (#13393188)
Seconded. ACA puts a cap on the profits of insurers. They are not just increasing the premiums and pocketing the difference. Most, if not all of the difference is going towards medical care by law.

"MLR measures the share of health care premium dollars spent on medical benefits, as opposed to company expenses such as overhead or profits. For example, if an insurer collects $100,000 in premiums and spends $85,000 on medical care, the MLR is 85%. In general, the higher the MLR, the more value a policyholder receives for his or her premium dollar. The ACA requires an annual, minimum 80% MLR for individual and small group insurance plans, and an annual, minimum 85% MLR for large group plans." [1]

Source: https://fas.org/sgp/crs/misc/R42735.pdf

Re:Affordable Care by ChuckMcM on Friday January 13, 2017 @01:34PM (#13393266)
It is unfortunate it does not put a cap on the profits of medical providers. Hence the 'pain cream' fraud[1] and others.

Sunlight is an amazing disinfectant and it is my hope that our government mandates every doctor and facility publish the total cost of every prescription and procedure they employ. We will collect that data and disinfect the high cost of health care.

[1] https://www.fisherbroyles.com/marketers-for-compounded-pain-...

Re:Affordable Care by CalChris on Friday January 13, 2017 @02:02PM (#13393628)
Just to be clear, medical insurance != medical providers. The cap that the ACA set was on insurance companies. And it would be good to put a cap on the profits of medical providers that are paid by the ACA coverage. That however is very complicated.

By comparison, Bush's Medicare Part D prevented the Feds from even negotiating drug prices. Its author, Billy Tauzin, is now a Big Pharma lobbyist.

Re:Affordable Care by ChuckMcM on Friday January 13, 2017 @02:16PM (#13393785)
Yup, and medical providers (like the compounding pharmacy in the pain cream case) need some attention as well and that is missing in the ACA.
Re:Affordable Care by cmiles74 on Friday January 13, 2017 @03:19PM (#13394343)
I agree wholeheartedly. In my opinion, insurance providers and providers of health care (hospitals in particular) are trapped in a co-dependent cycle. Capping one without the other seems short-sighted to me.
Re:Affordable Care by jrs235 on Friday January 13, 2017 @02:06PM (#13393681)
So insurance is bounded by cost plus pricing now. They have no problem if actual health care costs go up, their bottom line profits go up too! The insurance companies interests are now misaligned. Yeah they want to keep costs down to increase their spread, but if the spread is limited and allowed now they have no problem if hospitals charge $200 for what was a $100 procedure last year because $30 is more than $15 and they'll just increase premiums!
Re:Affordable Care by phil21 on Friday January 13, 2017 @07:40PM (#13396059)
I never understood why this is not glaringly obvious before anyone implements such a plan. Or maybe it was and this was intended? Seems just as likely at this point.

I mean, this is a constant joke in professional circles. If you are hourly billing and you can use your shitty talent to create something in 8 hours that your good talent would create in 1 - it's usually economically beneficial to have the worse employees do the work as it's more profitable overall. Up until the point where you lose the customer - but in this case that's not a concern.

Re:Affordable Care by mooreds on Saturday January 14, 2017 @09:01AM (#13398385)
> but in this case that's not a concern

Why? It seems that if premiums are rising relentlessly for one company that the insured will seek out other companies, and hence that one company will "lose the customer".

Or am I missing something?

Re:Affordable Care by gleb on Saturday January 14, 2017 @12:01AM (#13396984)
Its safe to assume that it was obvious to everybody involved. And therefore was quid-pro-quo for passing ACA.
Re:Affordable Care by will_pseudonym on Friday January 13, 2017 @08:27PM (#13396274)
It's right up there with excess taxes on gambling and tobacco. Governments become dependent on those excesses and are disincentivized to decrease the activities they're ostensibly trying to lower.
Re:Affordable Care by daveguy on Friday January 13, 2017 @10:07PM (#13396606)
> excess taxes on gambling and tobacco

You may be mishearing the term "excise tax". An excise tax is a tax on any specific good, such as tobacco or gasoline. Those taxes are included in the cost of the good (it just costs more at the pump or on the shelf). Yes, they are typically used to reduce consumption, or to pay for costs associated with consumption (eg roads).

Re:Affordable Care by will_pseudonym on Saturday January 14, 2017 @01:27AM (#13397217)
I'm aware of what excise taxes are, but I see why it might seem like that's what I meant, because I wasn't really explaining what I meant by that phrase. By "excess tax", I mean taxes in excess of the cost of the behavior they're trying to regulate. Both of these examples are both excise taxes, the rates of which are in excess of the costs borne to society of those activities.
Re:Affordable Care by sesqu on Saturday January 14, 2017 @10:17AM (#13398733)
Disincentivizing taxes are usually very profitable, because they're targeting goods that are considered overly desired. Their effectiveness is not too clear, but it is commonly accepted that they do reduce consumption. For example, a recent study on soft drink taxes concluded that retailers absorbed half of the extra cost to keep consumption high.

An alternative income source might be luxury taxes. There are a number of luxuries where consumption correlates positively with price - but it would be politically difficult to implement a tax on extravagance.

Re:Affordable Care by jrs235 on Friday January 13, 2017 @09:14PM (#13396443)
To add to this, before, insurance companies tried pushing care costs down and tried to keep premiums lower in order to compete with other insurers. Now with a mandate for coverage the competitive pressure to keep premiums lower in order to steal customers away from others and induce new uncovered buyers went away. A silent industry wide "gentlemen's" agreement now exists. Don't compete on lower premiums, let health care costs go up so they all benefit. It's easier to allow costs to go up and profit more by passing costs onto customers than it is to compete on having lower premiums by reducing costs and being more efficient. You can only cut expenses so much, but the sky is the limit to profits if cost plus pricing is in play and costs go up for the entire industry.
Re:Affordable Care by abalashov on Sunday January 15, 2017 @12:52AM (#13402584)
So insurance is bounded by cost plus pricing now.

They're defence contractors now! :joy:

Re:Affordable Care by jrs235 on Sunday January 15, 2017 @09:38PM (#13407903)
Why repair a tire when it makes "financial sense" to blow up the truck and order a new one?!
Re:Affordable Care by will_pseudonym on Friday January 13, 2017 @04:03PM (#13394681)
ACA puts a cap on the profit margins of insurers. It does not put a cap on the total profit of insurers. Mandatory minimum medical loss ratios (MLR) actually could have the opposite of the desired effect. To maintain $X in profits that they enjoyed before the minimum MLR, an insurance company would just need to increase total premiums and benefits. This means that they're less incentivized to reduce benefits/premiums, since their profits rise when both rise. It also more strongly encourages mergers of insurance companies, reducing competition.
Re:Affordable Care by lxmorj on Friday January 13, 2017 @10:36PM (#13396708)
I used to work for a utility company and there was a huge aversion to any innovation that drove costs down. Guaranteed ROI is incredibly counter-productive as a regulatory measure.
Re:Affordable Care by RA_Fisher on Saturday January 14, 2017 @12:57AM (#13397144)
Gotta keep that cost basis high to apply the ROR against! Build a big nuclear reactor paid for by the rate-payers pass go and collect 8-10% ROR!
Re:Affordable Care by smallnamespace on Saturday January 14, 2017 @02:00AM (#13397303)
There's actually little incentive to do this because increasing the cost basis usually costs more investor dollars.
Re:Affordable Care by RA_Fisher on Saturday January 14, 2017 @10:36AM (#13398817)
Not if they get pre-approval in a rate case. Well and like the OP mentions it's often done by overlooking efficiency gains.
Re:Affordable Care by amluto on Saturday January 14, 2017 @01:04AM (#13397162)
> ACA puts a cap on the profits of insurers. They are not just increasing the premiums and pocketing the difference.

Unfortunately, I think it's percentage cap, not an absolute cap. So, if you're an insurer and want to increase profits by a dollar, you need to increase costs by a few dollars.

Re:Affordable Care by merpnderp on Friday January 13, 2017 @03:13PM (#13394309)
The cap is a percentage of cost, a truly evil incentive to encourage ever increasing health care costs.
Re:Affordable Care by jonlucc on Friday January 13, 2017 @09:23PM (#13396485)
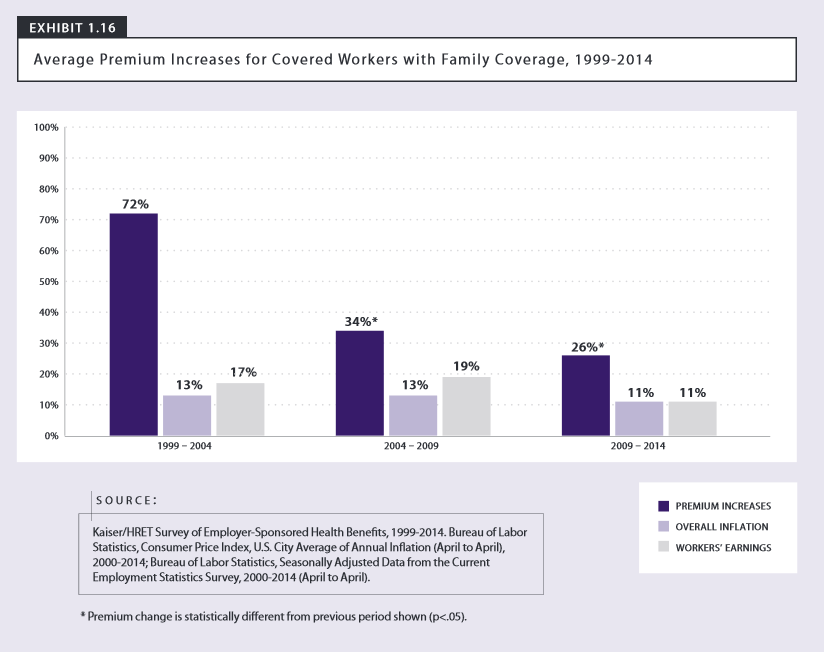
Except that premiums have increased slower in the 5 years after ACA than the 2 5-year periods before [1] and the rate of expenditures, while not decreasing, is basically unchanged after ACA [2].

[1] http://www.factcheck.org/UploadedFiles/2015/02/kff-chart.png [2] http://data.worldbank.org/indicator/SH.XPD.PCAP?end=2014&loc...
Re:Affordable Care by mgkimsal on Saturday January 14, 2017 @07:49AM (#13398164)
This was not my experience at all, at least as someone purchasing directly (not through an employer).

Before ACA, our premiums went up ~5% per year - 8% one year - every year was under 10%. Since ACA, I've seen increases of 25%, 20%, 20%, 25%, then 11% then 13%. This is in NC with Blue Cross - the numbers possibly were different elsewhere (was in Michigan before that but wasn't paying as much attention, unfortunately).

The price increases I was seeing seemed primarily in line with inflationary numbers pre-ACA; post-ACA they seem to have no correlation to inflation, and seem to have more to do with a much larger overall cost for the insurance company covering more people, no lifetime caps, more services covered, etc.

EDIT: On, that factcheck chart - that looks to be showing premium increases for employer-provided health insurance. Employers cutting back their contributions to the premium would account for much/most of those increases. Effectively, it doesn't say anything about the actual insurance premium increases, only what employer-covered workers were having to pay - in my view, that's a big difference.

Re:Affordable Care by gleb on Saturday January 14, 2017 @12:23AM (#13397048)
Disputed at best, the opposite reality at worst (i.e. it bent the cost curve up):

http://blogs-images.forbes.com/theapothecary/files/2016/04/S...

It was the recession.

Re:Affordable Care by basch on Friday January 13, 2017 @02:02PM (#13393626)
a cap on profit as a percentage makes it beneficial for insurance companies when medical costs rise ...
Re:Affordable Care by BurningFrog on Friday January 13, 2017 @01:38PM (#13393313)
The insurers are actually losing billions on the ACA plans. This is why they're abandoning it, and why the system is in its infamous "death spiral".
Re:Affordable Care by cmdrfred on Friday January 13, 2017 @01:32PM (#13393252)
If you've ever run a business 20% profit is gigantic. Your local supermarket runs margins around 2 - 3%
Re:Affordable Care by smnrchrds on Friday January 13, 2017 @01:44PM (#13393398)
20% is not the profit. It's the maximum they are allowed not to pay to healthcare providers. Most of it will probably be spent of the cost of running their business: salaries, office space, advertising, office supplies, etc.
Re:Affordable Care by mythrwy on Friday January 13, 2017 @01:59PM (#13393601)
The huge tower skyscraper in the middle of town...

Seriously, something is wrong with the whole setup. ACA does address some of it but it has jacked my premiums sky high. Single Payer is the answer in my estimation. The sooner we come to this and stop fiddling around trying to make people we shouldn't happy the better off we will be.

Re:Affordable Care by jtuente on Friday January 13, 2017 @01:42PM (#13393359)
That 20% also covers employee salaries, building and maintenance costs, whatever IT infrastructure is needed, etc. That's not net profit like the 2-3% supermarket number you offer.
Re:Affordable Care by cmdrfred on Friday January 13, 2017 @03:53PM (#13394593)
So 10% margin then. Still outstanding.
Re:Affordable Care by abalashov on Sunday January 15, 2017 @12:56AM (#13402592)
I would guess probably something like 2-5%.
Re:Affordable Care by zodiac on Friday January 13, 2017 @08:00PM (#13396154)
> So 10% margin [citation needed]
Re:Affordable Care by reverend_gonzo on Friday January 13, 2017 @01:46PM (#13393415)
You can't just compare margins from different businesses, as what's necessary entirely depends on the business.

Some business (like insurance) have a fair bit of tail risk they need to take into account.

Some are seasonal (like a ski resort) and need to make sure the profits they make in their high season can carry them in the low season.

Some are cyclical (like furniture stores) where people buy one piece and don't buy anything else for years.

Grocery stores have consistent customers and can generally predict their income and expenses day-to-day for the foreseeable future.

Re:Affordable Care by gleb on Saturday January 14, 2017 @12:34AM (#13397074)
Fair enough, the comparable number in car insurance is 97%:

The personal auto insurance combined ratio rose by 1.4 percentage points in 2015 to 97.3 percent for a group of 10 publicly traded insurers.

http://www.insurancejournal.com/magazines/features/2016/03/0...

When interest rates are higher car insurance runs > 100% loss ratio. They stay profitable by earning short term interest on premiums before paying out claims.

In a different insurance vertical fixing loss ratios at 80% would be called a cartel, and would put involved executives into prison for a good long time.

In healthcare the government forms the cartel, fixes the prices, gives money to poor to become consumers, and then fines everybody who won't become the consumer.

said Brer Rabbit. "Only please, Brer Fox, please don't throw me into the briar patch."

Re:Affordable Care by cmdrfred on Friday January 13, 2017 @04:45PM (#13394972)
First. I don't know of a more consistent revenue model than something that is often automatically removed from paychecks monthly.

Second, a profit margin will take into account risk. So for the ski resort or the furniture store that includes the overhead of keeping the store open while you have no customers.

Third, if the risk is so insanely high why are these firms so consistently profitable? Shouldn't we expect to see them coming in and out of existence regularly? Restaurants are a truly high risk business venture, the majority fail to exist after the first year. Perhaps they have longer runways but it's rare to hear of an insurance firm shutting its doors. The large and consistent profit seen on their end of year reports belies the risk claim.

Re:Affordable Care by jsmeaton on Friday January 13, 2017 @08:45PM (#13396335)
I'm not trying to justify insurance company profits. I think it's mostly a load of crap. But the costs of a grocery store are pretty much fixed and easy to predict. The costs for an insurance company are far more complex, because they change with the number and scope of claims.

I don't think you can deny there are cost risks for insurance companies that a lot of other markets don't have. However, to back you up a bit, their profits are extremely good which probably means they are largely overstating the risk in order to gouge their customers.

Re:Affordable Care by ericd on Saturday January 14, 2017 @08:38AM (#13398304)
In aggregate, over a large number of subscribers, insurance should be predictable as well.