https://bankunderground.co.uk/2015/06/30/banks-are-not-inter...
By creating credit faster than the underlying wealth creation of an economy banks are appropriating real goods and services and the wealth generation later (or rather now as they lent for decades like this) and they walk off with the goods whilst we all drown in asset inflation.
I would agree that demographics played a big part. Boomers borrowed heavily as though the demogrpahic inversion were not a problem, and banks played along. Now we have the money supply collapse as we have more olds than young, meaning a collapse in credit supply which is a problem as the model requires that principal + interest is paid back which cannot happen unless more debit is issued into the face of loan expiry which destroys the credit but still requires the interest be paid from some other debt source.
Why else do we need constant QE and ZIRP? To encourage more borrowing to try and maintain the rate of credit creation to keep the money supply up as boomers pay down at their end of life.
What a nuts system and also a terrible one as all productivity gains are soaked up by adaptable pricing on land to capture all gains.
excited for my HN "you're submitting too fast" soon when anything about banks or rentiers is mentioned!
> While money is essential to facilitating purchases and sales of real resources outside the banking system, it is not itself a physical resource, and can be created at near zero cost.
> The fact that banks technically face no limits to instantaneously increasing the stocks of loans and deposits does not, of course, mean that they do not face other limits to doing so. But the most important limit, especially during the boom periods of financial cycles when all banks simultaneously decide to lend more, is their own assessment of the implications of new lending for their profitability and solvency. By contrast, and contrary to the deposit multiplier view of banking, the availability of central bank reserves does not constitute a limit to lending and deposit creation. This, again, has been repeatedly stated in publications of the world’s leading central banks.
The current model of understanding is broken. To issue money nothing has to be created, therefore if one issues money whilst wealth creation stands still one appropriates some of the total wealth through inflation.
Before if you wanted more money you had to have more gold reserves, or the govt/central bank had to lower the exchange rate.
> http://www.econlib.org/library/Enc/GoldStandard.html
Because new production of gold would add only a small fraction to the accumulated stock, and because the authorities guaranteed free convertibility of gold into nongold money, the gold standard ensured that the money supply, and hence the price level, would not vary much.
http://www.shadowstats.com/imgs/charts/m1.gif
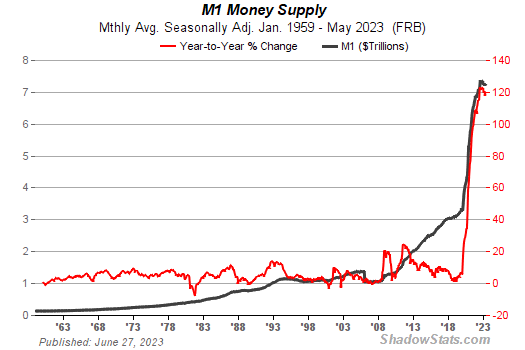
Again the boe blog from above:
> the availability of central bank reserves does not constitute a limit to lending and deposit creation
Private banks decide how much land costs. And they always lend as much as they can, so land will always be as much as people can possibly pay. This means that no amount of efficiency gains will ever improve life. All you will see is inflation and people who bought just before the jump have a gain, but again the next batch are pushed into servitude. Because we haven't had a big step-change in efficiency for a couple of decades (and in part because it's not passed on due to globalisation / migration) it's misery all round, unless you are a usurer.
I never understand why you guys are doing it if you don't gain. You are doing it because it is easy money, an easy way to extract labour.
What are you expecting anyway in terms of an ongoing income stream from this endeavor? It's very low skill, to borrow you need a pulse and a job. To administer you need basic numeracy. Hardly any labour required, certainly not skilled. Sounds like minimum wage for the basic admin required, so what, a few hours a month?
The only "value" here is the ability to borrow to exert monopoly control over other wage earners in order to force them to give you a portion of their labour. That is the main ingredient in the majority of cases. Yes we need a rental sector but as I said it's low skill and the rewards should reflect this instead of dividing society into have and have-nots.
Disipline paying they mortgage! Is that a skill now, taking $1500 from a worker, trousering $300 then handing the rest to a bank.
You are the debt collectors for the banks. Distributed extortion. No skill there yet the rewards for parasites are huge.
The financial trickery you're talking about is caused by deregulation and would happen on the gold standard just as often, but with probably far more disastrous consequences.
In any case it seems you agree that unfettered credit issuance is a huge problem, and perhaps the root cause of the upward pressure on asset prices that inevitably moves in step with productivity gains / more work?
Where is all your labour going? Food? No. Transport? No. Energy? No. Rent? Bingo.
Why is this happening? Because we came off the gold standard and there is no limit to the expansion of fiat money, therefore it expands via mortgage lending to mop up all productivity gains. Get the women out to work! Land prices up. Efficiency gains? Land prices up.
We bid for land. The more we have available after basic living costs the more we can pass over to the rentiers.
We need land value tax to suppress rentier activity.