Of course. That doesn't mean governments follow a simple zero-sum model. Government economics is it's own beast, with (hopefully) it's own solutions.
re: fsck the theories - you may find this[1] interesting, which is a summary of where we stand right now on many aspects of government economics by econ prof Mark Blyth that he gave at a recent q&a session. It might be one of the most succinct explanations of just how badly we're fscked.
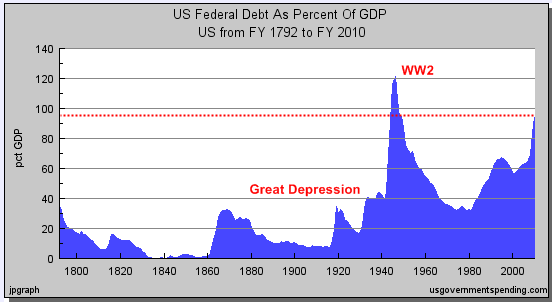
http://www.mybudget360.com/wp-content/uploads/2010/12/us-pub...
Japan (at the time, primarily a few zaibatsu) had serious financial problems when their export bubble popped in the 1920s. Unfortunately, they bought into myth that austerity lowers debts really badly, and decided it was a good idea to cut out 30% (!) of their GDP in two years. When that only made the situation worse, they doubled down and tried to cut another ~10%.
The zaibatsu and 37 banks went under in the inevitable bank-run, and quite a few financial leaders were assassinated when the military realized their budget was about the only thing left that could be cut.
Compared to that mess, the US has done a relatively good job of inflating away it's debts. Our gridlock blocked most of the austerity "fixes", so while we still have a mess of an economy, at least it isn't slashing a third of our GDP.
You've had your quote of unsustainable private debit, but not public.
How so, other than you don't like it? The data over the past 9 years seems to have confirmed a Keynesian analysis of the global economy.
"but it allows the governments to spend as much as they want"
No, that's not how it works. Keynes' theory is about how a general glut can happen, due to the role of money and bonds as a second and third variable in markets (vs the usual supply and demand curve). There are various techniques to get out of it, the only time government should spend money is when we've basically dropped interest rates to 0% - free money! - and companies still aren't spending it.
"Furthermore, it devalues the money in our wallet everyday we don't spend"
You mean by inflation? The inflation that doesn't currently exist? http://www.usinflationcalculator.com/inflation/current-infla...
Deflation on the other hand, has always been scary, for hundreds of years.
Now I know the necessity to do that has been dismissed by modern economists but actual Keynesian policies still have to be implemented by politicians who get elected. During recessions there tends to be a reluctance on the part of electorates to deliberately take on more debt which IMHO leads to Keynesian responses which are never quite robust enough to do the job they're intended to do.
Whereas if you did actually run a surplus during good economic times or at least during some of the good economic times then the public would likely be a lot more likely to back a real Keynesian response.
How much of "normal" GDP should you spend in a crisis in order to avert it? 5%? 10%? 20%? 50%? 100%? 500%? I've never heard a solid answer, mostly just "however much we spent wasn't enough" which seems a little tautological.
The only reason I'm picking on you is you said "never quite robust enough" as though you just plug a number into a formula and get an answer.
In terms of how much I would say between 5 and 10% depending on the severity of the recession and that need not all be in the form of government spending per se, it could also be a mix of tax cuts as well.
By your own numbers, that should have been enough, and yet you've complained it wasn't. What gives?
QE is complimentary to but not a replacement for a Keynesian response.
If you want loads of shiny new gadgets every year, and want it so most people spend their entire lives working just to pay rent and only a lucky few escape with "fuck you" money, then it's the system for you.
If you want the average person to have the economic freedom to work less, and actually get time to enjoy their discretionary purchases, then debt-based slavedriving is not what you want.
It's a deliberate policy choice, but gets obscured as authoritative "science" by centralization-supporting economists who are compensated with money and stature.
Deflation isn't scary, only the transition to it is (like any change). Deflation is actually the natural tendency, as doing things cheaper is precisely what market competition is based on (see: the entire technology sector).
This sounds made up. How is optimized production different from efficiency? How is growth unsustainable? An economy without growth is by definition zero-sum; is that what is sustainable, no more Pareto efficiency, that someone must lose for another to gain?
"If you want loads of shiny new gadgets every year, and want it so most people spend their entire lives working just to pay rent and only a lucky few escape with "fuck you" money, then it's the system for you. If you want the average person to have the economic freedom to work less, and actually get time to enjoy their discretionary purchases, then debt-based slavedriving is not what you "
Keynesianism has nothing to do with private debt or private spending habits, nor weekly work hours. You can blame many for such problems, I don't know why Keynes would have anything to do with this.
"Deflation isn't scary, only the transition to it is (like any change). Deflation is actually the natural tendency, as doing things cheaper is precisely what market competition is based on (see: the entire technology sector)."
That's not deflation.
Deflation is when the entire broad based market across products and services lowers their prices for the same products and services. It in practice causes depressions very similar (and deeper) than what we just experienced.
The tech sector lowers prices in a specfic sector by using new technology. By definition this is about classic creative destruction and reallocating of resources.
Deflation is what happens when there is not enough demand for the supply, and therefore everyone stops spending money, people lose their jobs. Interest rates fall to 0, and prices fall across the board. In other words, very close to what happened in 2008-2009.
Deflation was something that theoretically shouldn't happen by classical models until Keynes showed it does, and we saw it in earnest in Japan during the 90s.
Erm, this is a well known general trade off. Driving 55mph vs 80mph on the highway - the former uses less fuel for the same distance, the latter gets you further in the same amount of time.
> How is growth unsustainable?
If something is growing, eventually it becomes constrained by some sort of limit. If the expectation is that it is continually growing, hitting a limit means that it has "failed". Both of these general juxtapositions are quite common, so your picking apart of them seems quite defensive rather than understanding.
> Keynesianism has nothing to do with private debt or private spending habits, nor weekly work hours ... I don't know why Keynes would have anything to do with this.
Which is it - are you sure Keynesianism has nothing to do with them, or do you not know?
When interest rates are low (or nonexistant, like the past 6 years), people are discouraged from saving in cash. If they have a significant surplus, they budget month to month and put the surplus into opaque long-term "investments" (retirement fund at the wall st casino, etc). They don't perceive the cash value and treat the account like a lock box, so they base their spending power on monthly income rather than savings. Their utility curve remains fixed (they need that monthly income), giving them less bargaining power with employers so their wages remain low.
> An economy without growth is by definition zero-sum ... that someone must lose for another to gain?
Zero-sum is an awfully strong term, given that we're talking about production rates. Durable goods stick around - if a person receives 1 house/yr for a single year, and then someone else receives that 1 house/yr instead, are you really going to characterize this as "zero-sum" ?
In general, it seems that you're conflating production with the integral of production. This is a general theme of Keynesianism, given that it is explicitly about maximizing output by maximizing work. Given that the major economic phenomenon of our time is robots taking over historically human work, we should probably rethink this goal.
My point regarding deflation is that what happens in the tech sector is just a more pronounced version of what should be happening everywhere. Prices may rise in the short term (eg a discontinuity from depleting a source of a natural resource), but in general market competition should cause all prices to be trending down in the long term.
If you're using "production" as a synonym for "output", that's my misunderstanding of the words used. I get that it's a resource vs. output tradeoff. I had thought we were talking about productivity, i.e. lower rate of a unit of resource for the same output.
"If something is growing, eventually it becomes constrained by some sort of limit. If the expectation is that it is continually growing, hitting a limit means that it has "failed"."
Are limits fundamental and eternal? I mean, economic growth is basically the science of human achievement, the ability to accomplish more for fewer resources. And while certainly there are physical limits on Earth, which will temporarily halt growth at some point, is there a limit on innovation or on seeking out new resources? It's a big universe.
"Both of these general juxtapositions are quite common, so your picking apart of them seems quite defensive rather than understanding."
No, I genuinely find your point of view fascinatingly bizarre.
"Which is it - are you sure Keynesianism has nothing to do with them, or do you not know?"
I am quite sure about what Keynesianism thinks on this matter, and find your arguments confusing.
"In general, it seems that you're conflating production with the integral of production. This is a general theme of Keynesianism, given that it is explicitly about maximizing output by maximizing work. Given that the major economic phenomenon of our time is robots taking over historically human work, we should probably rethink this goal."
I'm not so convinced the current wave of robots taking over human work is all that different as the early industrial revolution in the late 18th century through Fordism and Taylorism in the late 19th/early 20th century.
However, I'll admit, if this time it truly is different, i.e. we're heading for an AI singularity or whatnot, we do need to rethink the goals of economic policy.
"My point regarding deflation is that what happens in the tech sector is just a more pronounced version of what should be happening everywhere. Prices may rise in the short term (eg a discontinuity from depleting a source of a natural resource), but in general market competition should cause all prices to be trending down in the long term."
I really can't agree with deflation as a desirable goal in our lifetimes, as it incentivizes doing nothing with capital.
Of course, as above, if diminishing returns to capital accumulation vanishes due to basically free automation, this may be worth considering. I think it's overly optimistic about technology to expect this, however.
I know this disagree with mainstream economics, and almost all niche economics theories. But it's happening again and again, so fuck the theories.