News for hackers. Stuff that matters.
Re:It Is Not About the Money, Silly, It Is All About the Time by charlieflowers on Wednesday August 27, 2014 @11:30AM (#8232631)
OK, well look around. Do you know a lot of people (is it possibly even most of the people you know) who have 2 or more car loans, and at least one home loan?

That's the "norm". That's what "everyone" does (everyone who is in a first world country and has a decent job).

Is that somehow "smart debt"? Really? What's so smart about it?

It is smart for whomever loaned that money out ... they get back free money paid consistently over the years. How is it smart, in 90% of the cases, for the borrowers?

Our culture tends not to see this in the same way fish don't see water.

Re:It Is Not About the Money, Silly, It Is All About the Time by kenrose on Wednesday August 27, 2014 @11:47AM (#8232722)
> Is that somehow "smart debt"? Really? What's so smart about it?

Regarding a mortgage and 2 car loans, I'd like to offer a defense of why it's smart / good debt.

The primary reason that your mortgage is considered "good debt" is because the asset you purchase with that debt (your house) will typically appreciate faster than the interest you pay. I'm not including black swan events like the 2008 crisis. When you eventually sell, you'll be in the black.

Regarding car loans, the only type of "smart" car loan is 0% financing. A 0% loan lets you keep your money in your pocket for longer (and in that time, you can invest it however you see fit). 0% loans can be found depending on when you see the dealer. End of the month? Quota wasn't reached yet? Perfect time to negotiate.

I'm certain jaquesm's point is that lots of people get in over their head with their purchases, especially large purchases like homes and vehicles. However, DontBeADick's point has some validity: Taking on debt can allow you to realize further gains than you would have otherwise seen (basic leverage).

Re:It Is Not About the Money, Silly, It Is All About the Time by webwright on Wednesday August 27, 2014 @12:41PM (#8233052)
"The primary reason that your mortgage is considered "good debt" is because the asset you purchase with that debt (your house) will typically appreciate faster than the interest you pay."

Any money manager will tell you that what you just said is false. Excepting a few cities, when you look at the data and adjust for inflation, owning a house is not a particularly good investment ( http://files.foreclosureradar.com/images/foreclosuretruth/Hi... ). Add in that the average home loan lasts about 6ish years before folks sell/refi, the fact that interest/fees are front-loaded into the first 5 years of the loan, and that avg. annual maintenance on a house (NOT improvements) tend to average about 1% of the value of the home per year, it gets worse.
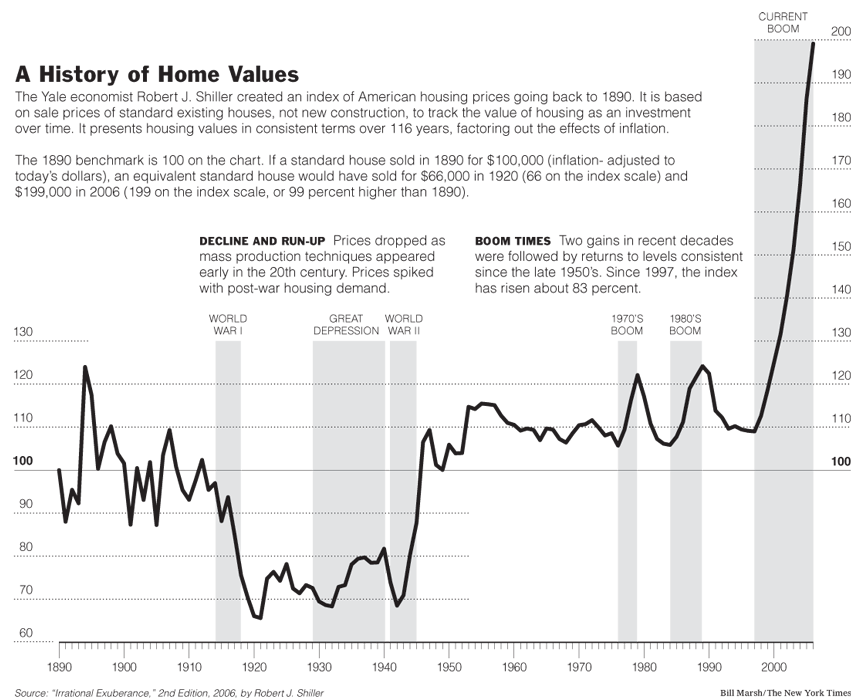
What it CAN be (if you're disciplined and lucky) is leverage and liquidity. Example: I have my house paid off. I get a mortgage on it, essentially getting a loan at 4% for $700k. Now I have $700k that I can make work for me-- a worthwhile idea if I can find a way to make more than 4% on that $700k via other investments (which are not remotely risk-free, but can pay off). Of course, what most people do when they re-fi their house is self-indulgent stuff-- buying a vacation home, a boat, home improvements that don't pay for themselves, etc.

Re:It Is Not About the Money, Silly, It Is All About the Time by seanflyon on Wednesday August 27, 2014 @07:47PM (#8235265)
It is fair to count maintenance as a cost but it is also fair to count rent you don't have to pay as a savings.

Compare (+equity -mortgage -maintenance -taxes) to (-rent)

Re:It Is Not About the Money, Silly, It Is All About the Time by dpina on Wednesday August 27, 2014 @11:58AM (#8232792)
Most people don't usually get two car loans just because that's what other people do or because it seems smart/cool. They do it because both people living in the same household need a personal car to get to work. Granted that maybe they could leave their white collar high paying jobs, find some other job at the groceries store in the street and trash the car loan. But the salary difference doesn't pay off. Also, for a lot of people public transportation doesn't pay off either.

As for a mortgage, as others have explained in this thread, it could be a smart debt given the right conditions. For example, if I had a bank loan to buy a house with the similar value to the one I currently rent, I would be paying a smaller amount of money to the bank than what currently is being transferred to my landlord monthly. I could live forever without a mortgage, but in 30 years time would find that I had spent a lot more then if I did.

It's not all 'several loans = bad money management vs no loans = good money management' sadly.

Re:It Is Not About the Money, Silly, It Is All About the Time by smackfu on Wednesday August 27, 2014 @11:41AM (#8232681)
>It is smart for whomever loaned that money out ... they get back free money paid consistently over the years.

Now explain why the same logic doesn't apply to a landlord being the smart one, and a renter being the dumb one.

Re:It Is Not About the Money, Silly, It Is All About the Time by JoeAltmaier on Wednesday August 27, 2014 @11:37AM (#8232666)
Really there's only car and house debt. The rest are small fry. And both of those can be problematic.
Re:It Is Not About the Money, Silly, It Is All About the Time by jacquesm on Wednesday August 27, 2014 @11:40AM (#8232679)
Don't forget about credit cards and buying on credit. That's not necessarily 'small fry' and neither are student loans.
Re:It Is Not About the Money, Silly, It Is All About the Time by chrisBob on Wednesday August 27, 2014 @11:55AM (#8232764)
The average US household has $15k in credit card debt. A mortgage can be a sound investment, but paying over 10% APR on credit card debt is almost always a bad decision.

http://www.nerdwallet.com/blog/credit-card-data/average-cred...

Re:It Is Not About the Money, Silly, It Is All About the Time by seanflyon on Wednesday August 27, 2014 @07:55PM (#8235290)
It's still terrifying, but according to your link $15k is the average indebted household credit card debt. The average credit card debt is about half that because only half of households have any credit card debt.
Re:It Is Not About the Money, Silly, It Is All About the Time by DontBeADick on Wednesday August 27, 2014 @11:47AM (#8232716)
A mortgage can be an extremely good investment, and a 0% car loan is essentially free money if you were going to buy the car anyway. My point is that there's no one-size-fits-all financial advice, and trying to promote the hip, rebellious "debt-free" lifestyle rather than educating people about debt really isn't doing them any favors.
Re:It Is Not About the Money, Silly, It Is All About the Time by jacquesm on Wednesday August 27, 2014 @11:53AM (#8232752)
Getting people to be more debt free would - in my circle of family and acquintances - do absolute wonders for their quality of life as perceived through their own eyes indicated by the level of bitching that I'm confronted with. Hence the post, it's not aimed at people like yourselves that are smart enough to figure this all out for themselves and that are capable of deciding between investing in a 7% average ROI annually real estate fund (read that small print), the impact of inflation and paying off a 4.1% mortgage.

If you can do that great.

But if you're about to finance your second new car (0% is not free money, that means that you're paying more for the car than you should have to because I can always get a better deal paying cash than someone that takes a 0% loan, and that's an indication that you don't understand this stuff nearly as well as you claim) or if you plan on getting a third credit card to pay off the previous one and you wonder where all your money goes then this post is for you.